R.M. Nunes/iStock via Getty Images
Summary
Northview Residential REIT (NRR.UN:CA) has been our top pick since initiating on the name back in October 2023. Since then, we have seen promising but slow progress on our deleveraging thesis. The recent Q1 2024 report showed strong operating performance across the portfolio but seasonally weaker financial results. Payout ratios for the quarter were stretched due to the weakness in FFO/AFFO (Q1 is a seasonally weak quarter for cash flow), and ~$16MM of the credit facilities were repaid. We have revised our NAV estimate up by ~$2/unit (n.b., ~11%) to ~$20.8/unit, but are now applying a 10% sensitivity to our NAV to derive our target price (n.b., ~$18.7/unit). We see ~29% upside to our target price (n.b., ~43% to NAV @ 100%). This remains well below the price implied by Canadian multifamily comps’, mean and median yields and AFFO multiples. We maintain our Buy rating.
Earnings Update
The suite count was largely unchanged QoQ (n.b., increases YoY reflect the portfolio acquisitions from the recapitalization), with the exception of the loss of 14 suites in Northern Canada due to damage from last year’s wildfires.
Average monthly rents (“AMR”) grew QoQ robustly, with standout performance seen in the Maritimes, Ontario, and Alberta. AMR in the Northwest Territories increased ~1.3%, a fairly significant improvement compared to the ~0.3% average quarterly growth in 2023.
Occupancy improved to 70bps across the portfolio, with Northern, Atlantic, and Central Canada effectively near full occupancy. Western Canada has seen the most marked improvement in occupancy on the back of strong population growth and improvements in the natural resource markets (n.b., the key economic driver for this region). Despite this improvement, there is still room for further occupancy gains with this portfolio at ~93%.
Earnings Update | Operations (Empyrean; NRR)
Expenses for the quarter are best compared to the prior year, given the seasonality in utilities spending. NOI is up +40% from Q1 2023, largely a function of the portfolio acquisitions. The consolidated NOI margin improved ~280bps YoY, a solid improvement.
FFO and AFFO also came in light compared to the prior quarter, as expected due to seasonality, but were significantly ahead of the prior year. The FFO payout ratio remained well below 100%, though the AFFO payout ratio crossed above 100%. We expect this to be transitory, as Q1 is a seasonally weak quarter, and for the full year 2024, the AFFO payout ratio will come out slightly below 100% as cash flow improves throughout the year and the company makes further repayments on the credit facilities.
Earnings Update | Financials (Empyrean; NRR)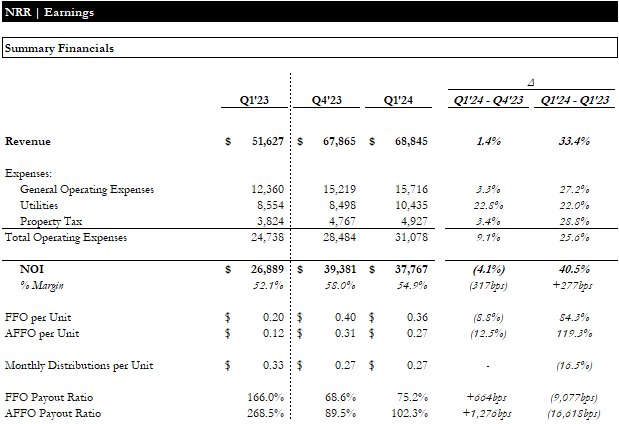
As discussed in our previous reports, leverage is Northview’s most significant consideration. During the quarter, the company reduced the balance on its expensive (n.b., ~8.7-9.9% all-in rate) credit facilities by ~$15.5MM / ~4.4%. This reduced the average cost of debt by ~10bps to ~4.9%. Overall leverage remained fairly stable at ~65-66% of GBV.
Earnings Update | Leverage (Empyrean; NRR)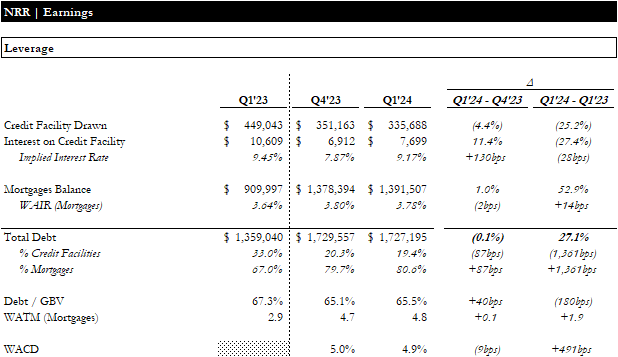
Overall, this was a phenomenal operational quarter for Northview. We are pleased by the strong occupancy and rent trends. As expected, the AFFO payout and leverage remain stretched. However, we are seeing progress towards paying down the credit facilities, reducing the company’s cost of debt, and ultimately reaching a sustainable payout.
Valuation
Northview trades for ~10x FFO and ~14x AFFO with a yield of ~7.5% and ~70% of our NAV estimate (n.b., implied ~7.2% cap rate). We see a ~43% upside to our NAV estimate of ~$20.8/unit, or ~29% upside to 90% of NAV.
We revised our NAV estimate up by ~$2/unit / ~11% on a higher NTM NOI of ~$144.3MM residential and $26.4MM commercial with a 6.5% cap rate.
Valuation Summary (Empyrean)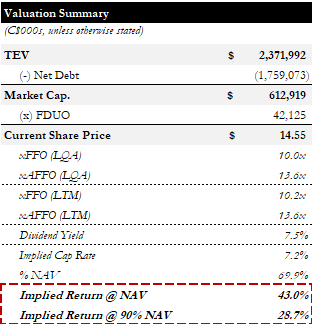
Northview continues to trade at a massive discount to the Canadian multi-family peer group due to its heavy exposure to secondary and tertiary markets, high leverage, and stretched payout ratios. These are valid reasons for Northview to trade at a discount. However, our NAV estimate implies a share price that is ~40% / ~12% below the price implied by the median comp on a yield / AFFO multiple basis.
Canadian MF Comps (Empyrean)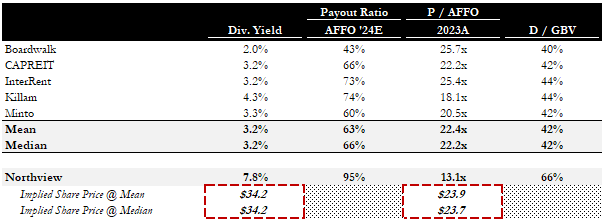
While leverage remains a concern, we do not view this as an existential risk to the REIT. Cash flow will be tight, likely for the next year, but we see a path to a sustainable capital structure. Northview is also well positioned to benefit from future rate cuts, given its high floating rate exposure via the credit facilities. These and low trading liquidity remain the primary risks/catalysts, as outlined in our previous reports.
Conclusion
While the critical risk of elevated and high-cost leverage and stretched payout ratios are lingering, we are seeing sufficient progress towards fixing these and believe the current price still provides a wide margin of safety relative to intrinsic and relative value. We believe Northview offers the most attractive risk/return we have seen in the entire multi-family universe. We maintain our Buy rating.
Editor’s Note: This article discusses one or more securities that do not trade on a major U.S. exchange. Please be aware of the risks associated with these stocks.
Credit: Source link