
Phanphen Kaewwannarat/iStock via Getty Images
It may be difficult to remember, but just six months ago, the S&P 500 had dropped 19% from its early-year highs, the Nasdaq was down more than 25%, and investors were concerned that stock prices were entering a sustained free-fall. Since then, indexes have regained their losses and moved on to new all-time highs.
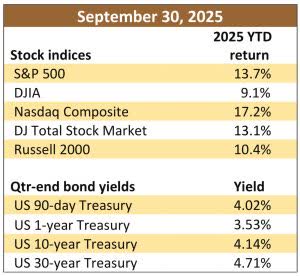
The stocks in our equity portfolio increased 12.3% in the first 9 months of the year. Your equity return may differ from these figures due to legacy positions, liquidity needs/constraints, and/or rounding.
This year’s market schizophrenia highlights (at least) three important points:
Short-term price movements are unpredictable.
- Both market corrections and recoveries can happen very quickly.
- It doesn’t take much to turn investor confidence into fear—the first hint of uncertainty can send prices tumbling.
- It doesn’t take much to turn investor confidence into fear—the first hint of uncertainty can send prices tumbling.
Points one and two are perennial market truths, regardless of the economic climate or valuations. Point three, however, is more environmentally dependent. In some market environments, investors might have more critically evaluated the likely effects of the threatened tariffs that wreaked havoc on markets in late March and early April. (We did evaluate what we believed to be a likely worst-case scenario and determined that, if fully implemented, the threatened tariffs would have increased consumer prices by a meaningful amount, but less than the effect of inflation in 2022. That is, the costs would have been noticeable but less severe than what the economy had only recently experienced.) Instead, the mere threat of a trade war—without much understanding of the likely consequences—caused a significant investor panic.
This points to a potential market fragility: investor attitudes toward risk can swing sharply, often on the basis of emotion rather than analysis.
We aren’t in the attitude-predicting business, but we are in the valuation business. And stock prices remain generally well above reasonable valuations—and substantially so in certain sectors.
“Objects in the rearview mirror may be closer than they appear”
As Moon Capital Management celebrated its third birthday in 1998, a cyclical peak in stock prices was forming, although that’s the sort of thing that is only knowable in hindsight. What was possible to know, however, was that investors’ attitudes about risk had collectively become reckless. Attractive, well-run, profitable companies like Walmart (WMT) and Coca-Cola (KO) were selling at ridiculously high multiples of earnings. Meanwhile, an entire new breed of companies with no profits—the dot-coms—were trading at prices that could only be rationalized with fancifully creative metrics like “price-per-eyeball.” Federal Reserve Chairman Alan Greenspan had warned of “irrational exuberance,” but his words were roundly dismissed as stodgy and out of touch with the new economy.
In 1998 and 1999, the Nasdaq Composite (COMP:IND) skyrocketed a total of 161%. The S&P 500 (SPY), led by a handful of its largest components, increased 56%. If you don’t believe that investors had decided profits were irrelevant, consider this: in 1999, the NYSE-listed companies with positive earnings collectively had negative returns, while unprofitable companies produced positive ones.
Value investing had fallen so far out of favor that Barron’s famously ran a cover story posing the question, “What’s Wrong, Warren?” As someone youthfully ignorant (or arrogant) enough to invoke Buffett’s name when explaining his investment philosophy, it was an awkward time to be a young value investor.
Of course, as economist Herb Stein famously observed, “If something cannot go on forever, it will stop.” And stop it did. Investors, a notoriously manic/depressive bunch, eventually remembered that the purpose of a business is to produce earnings for its shareholders—and in March 2000, the U.S. stock market began a two-and-a-half-year correction that cut the S&P 500 in half and crushed the Nasdaq by nearly 80%. Our equity return from 2000 through 2003 was a cumulative positive 54%, far outpacing the S&P 500’s loss and helping cement a significant period of growth for our young investment firm.
We would love to claim that our positive performance during this period of steep decline reflected a series of brilliant, well-timed investment decisions—but the truth is simpler. Our underperformance in 1998–1999 and our outperformance in 2000–2003 were both driven by the same discipline: we avoided the most overpriced pockets of the market. In the late ’90s, that meant dot-coms and mega-cap blue chip darlings. And when the hype deflated, investing in companies based on actual fundamentals suddenly made sense again.
As Mark Twain is said to have quipped, “History doesn’t repeat itself, but it does rhyme.” And lately, the rhyme has been unmistakable.
The purpose of this walk down memory lane is that today’s market environment feels a lot like the market of the late 90s. (Our job is to think, not feel. While we will never make an investment decision based on a feeling, it is impossible not to sense some of the similarities between now and the late 1990s.)
With the minor exception of the brief trade-war sell-off earlier this year, investors seem to have once again decided that almost all risks are irrelevant—except for one: the risk of missing out on the “next big thing.”
That “next big thing,” of course, is artificial intelligence. Like the internet in 1999, AI represents a genuine technological revolution. But just as the early internet boom priced in decades of growth long before it arrived, today’s enthusiasm for AI has driven valuations to levels that far exceed any realistic expectations.
And just as corporate executives in 1999 insisted that failing to bet big on the internet would be catastrophic, today’s tech leaders express the same sentiment about AI. Google’s CEO recently remarked that “the risk of underinvesting is dramatically greater than the risk of overinvesting.” Mark Zuckerberg was even more direct: “If we mis-invest a couple hundred billion, so be it.”
The four major hyperscalers—Microsoft (MSFT), Amazon (AMZN), Google (GOOGL), and Meta (META)—are collectively pouring hundreds of billions of dollars into AI infrastructure. In the second quarter of 2025 alone, these companies spent roughly $88 billion on AI-related capital expenditures, an increase of 67% from the year before. Microsoft alone is expected to spend over $100 billion this year just on AI initiatives.
Meta, not to be outdone, began construction on a data center reportedly large enough to “cover a significant part of Manhattan.” Analysts at Morgan Stanley and Citigroup estimate that cumulative AI investment could reach $3 trillion in data centers and $1.4 trillion in R&D by 2029. The scale is unprecedented, and, for now, the returns remain largely hypothetical. (OpenAI’s $13 billion annual run rate is meaningful, but it’s dwarfed by the $500 billion it envisions investing through its Project Stargate.)
Even the insiders concede the excesses are mounting. Sam Altman, CEO of OpenAI, recently cautioned that “someone will lose a phenomenal amount of money.” Jeff Bezos has gone further, calling the AI buildout an “industrial bubble.” Bain & Company estimates that by 2030, technology executives will need to generate $2 trillion in new revenue every year to achieve acceptable returns on these massive investments.
The venture capital world is in a similar state of frenzy. A former OpenAI employee’s startup, Thinking Machines, recently raised a record $2 billion of equity at implied business valuation of $10 billion. Keep in mind, this $10 billion is for an AI venture without a single product, or even a stated plan. (Re-read the previous sentence.) OpenAI (OPENAI) itself just completed a private secondary sale that valued the company at $500 billion, even as it continues to burn significant amounts of cash.
The similarities to 1998 and 1999 are undeniable. Well, they are to us, anyway.
There are also unsettling parallels to the financial engineering last witnessed during the dot-com bubble. Veteran short-seller Jim Chanos has pointed out that many AI suppliers are engaging in “vendor financing,” a tactic reminiscent of the telecom bubble, in which companies lend to customers to help manufacture demand. Meanwhile, chipmakers such as AMD have exchanged equity stakes for multi-year supply deals, boosting valuations in a cycle that feels unsustainably self-reinforcing.
To manage the optics of massive spending, some of the largest technology companies have even begun moving AI capital expenditures into special-purpose vehicles, which conveniently hide their impact on the balance sheet. These structures echo the off-balance-sheet arrangements that defined another, very different kind of bubble two decades ago.
The current speculative mania extends beyond AI into related fields like quantum computing. Firms including IONQ (IONQ), Rigetti Computing (RGTI), D-Wave Quantum (QBTS), and Quantum Computing (QUBT) now command combined market caps over $50 billion. Yet, as Rigetti’s own CEO admitted, the technology behind quantum is still in research and development mode. In simple terms, these are overhyped research projects with stock tickers.
Meanwhile, the market itself has become heavily concentrated. Also reminiscent of the late 1990s, the “Magnificent Seven” now make up roughly 36% of the S&P 500’s total market capitalization. A sharp AI-related stock correction could jolt the broader economy, as Reuters estimates AI-related activity drove one-third of U.S. GDP growth over the past two quarters.
Echoing then-Federal Reserve Board Chairman Alan Greenspan’s “irrational exuberance” warning from the 1990s, current Fed Chair Jerome Powell recently remarked that U.S. equities are “fairly highly valued.” And, just like Greenspan’s, Powell’s caution has mostly been ignored. When the market is racing higher, it’s easy to overlook warnings, especially when everyone around you is making money.
Markets have a habit of pricing in the promise of transformative technologies long before that promise is fulfilled. The internet did eventually change the world, but only after years of overbuilding and a painful reset. Many of the most celebrated names of the late 1990s disappeared entirely, with a few survivors like Google and Amazon emerging as winners only after the bubble had burst.
There’s no question that AI will leave a lasting mark. It’s already changing how work gets done, and over time it will reshape entire industries. But the path won’t be smooth. There will be periods of excitement and periods of disappointment, with a lot of noise in between.
It is always risky to write about risk, because some investors and clients may (very erroneously) assume we are making a prediction about the stock market. We’re not. Making an observation about investor behavior is not the same as making a forecast about prices. This is especially true in an environment where investors are quick to dismiss any fears of permanent capital loss and are quick to act on their fear of missing out.
Of course, neither of those fear-driven responses has anything to do with the actual value of businesses.
Our investment approach has and will remain unchanged. We will continue to evaluate actual business fundamentals such as earnings and cash flow and avoid the temptation to chase the “next big thing.” During the dot-com bubble, this discipline helped us navigate a turbulent market successfully. It did the same earlier this year during the market’s brief, but sharp, sell-off. We expect the same approach will serve us well in the years ahead.
| © 2025. Moon Capital Management, LLC is a Registered Investment Adviser with the Securities & Exchange Commission. SEC registration does not constitute an endorsement of the firm by the SEC nor does it indicate that the adviser has attained a particular level of skill or ability. SEC file number: 801-49240. |
Original Post
Editor’s Note: The summary bullets for this article were chosen by Seeking Alpha editors.
Credit: Source link