shapecharge
Early each year, I like to check in on how annuity sales trended for the previous year. Survey says: Another record. According to LIMRA, 2023 marked the second consecutive year of record sales for annuities. The increase was +23% compared to 2022 as retirement numbers continue to show more older workers exiting the labor force. These are tailwinds for Jackson Financial (NYSE:JXN).
I reiterate my buy rating on the stock after starting coverage a year ago. Shares fell big in March 2023, but I had outlined a ‘buy the dip’ strategy given the company’s valuation but weak chart. Now, the valuation is not as compelling, though still fair, while the chart situation has improved.
Record Annuity Sales
LIMRA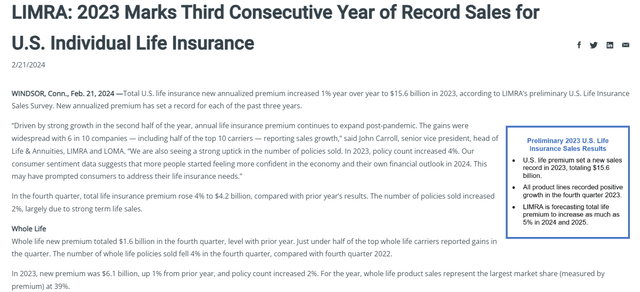
For background according to CFRA Research, Jackson Financial Inc. through its subsidiaries, primarily provides a suite of annuities to retail investors in the United States. The company operates through three segments: Retail Annuities, Institutional Products, and Closed Life and Annuity Blocks. The Retail Annuities segment offers various retirement income and savings products, including variable, fixed index, fixed, and immediate payout annuities, as well as registered index-linked annuities and lifetime income solutions.
JXN’s next earnings report is not due out until May. As it stands, data from Option Research & Technology Services (ORATS) show a somewhat modest 5.6% earnings-related stock price swing when analyzing the current at-the-money straddle expiring soonest after the report. Per-share profits are expected to come in near what was earned in the same period last year, but Jackson has traded higher post-reporting in each of the previous three quarters, despite a miss last month.
JXN Volatility Drifts Lower
ORATS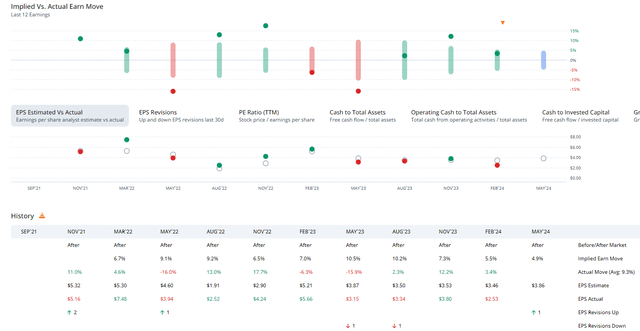
On valuation, the current consensus forecast reveals very strong EPS growth over the coming quarters. For 2024, 22% operating per-share profit growth is expected with an 11% EPS advance rate in the out year. By 2026, the firm may earn $20 per share in non-GAAP EPS. The top-line, meanwhile, is forecast to hold just under the $7 billion mark annually.
Shares trade at just 0.36 times its forward price-to-book ratio. Its historical P/B is 0.34 compared with the sector median of 1.1 (trailing). Thus, I am neutral on the valuation today despite the strong earnings growth expected, but given the solid growth tailwinds and share-price momentum, I like this play for a continued rally over the coming months.
JXN: Favorable Valuation Metrics, Near Its 5-Year Average P/B
Seeking Alpha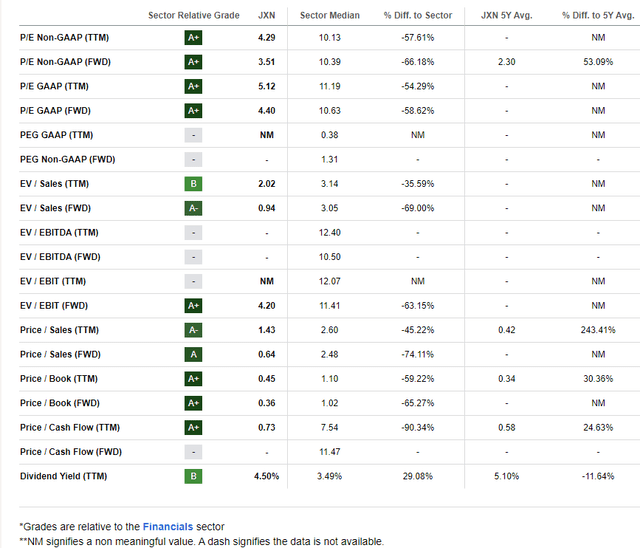
Jackson Financial: Strong 2023 Operational Performance
Jackson Financial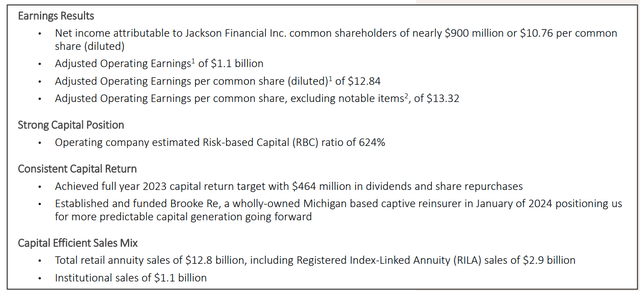
Compared to its peers, JXN features a strong valuation quant grade while its growth trajectory appears low. Again, since the company stands to benefit from rising demand for annuities as retirements rise in the country, I assert growth should be strong. Its profitability rating is weak, but insurance-related firms are generally valued and analyzed differently compared to traditional Financials-sector companies. There have been two EPS upgrades of the stock in the last 90 days compared with a pair of downgrades, but share-price momentum continues to impress technicians. I will outline key price levels to watch later in the article.
Competitor Analysis
Wall Street Horizon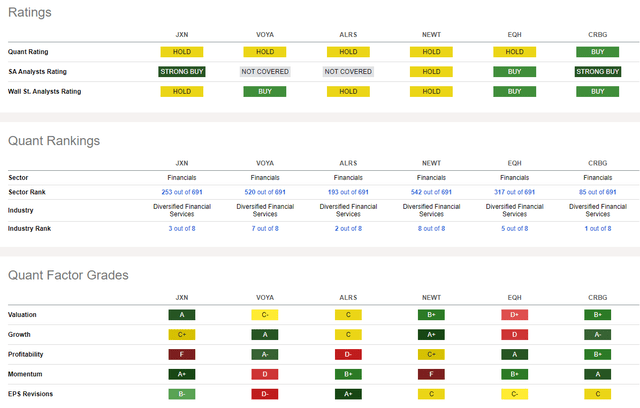
Looking ahead, corporate event data provided by Wall Street Horizon show an unconfirmed Q1 2024 earnings date of Tuesday, May 7 AMC. Before that, shares trade ex-dividend on Monday, January 11.
Corporate Event Risk Calendar
Wall Street Horizon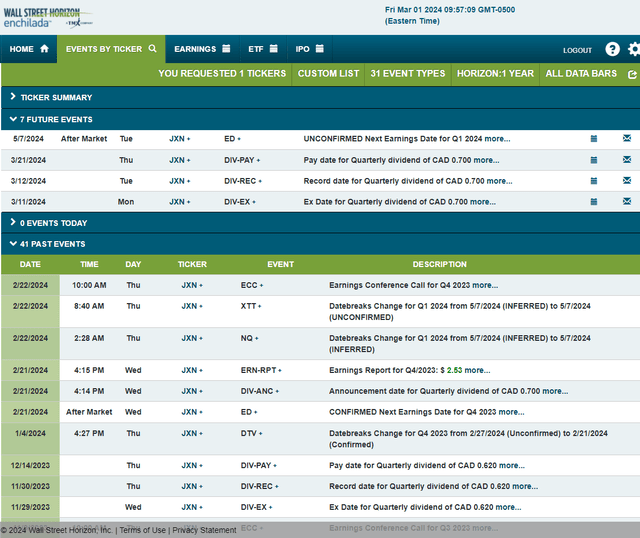
The Technical Take
With a fair valuation and fundamental growth tailwinds, the technical chart is favorable. Notice in the graph below that shares recently broke out to all-time highs on a momentum surge. The previous resistance range between $48 and $50 was a tough area for JXN – a zone I noted in the first quarter of 2023 as a spot of selling. Following a plunge to under $27 around the final bouts of US regional banking turmoil, Jackson Financial rallied to a high of $53 by late last year – about doubling from the 2023 nadir.
Today, with a rising long-term 200-day moving average and a significant jump post-earnings last month, this is among the best-performing stocks in the sector of late. One cautious indicator is seen with the RSI momentum gauge at the top of the chart – it’s printing a lower high compared to the peak from December. That is bearish RSI divergence, and bears watching as we head into what can be a volatile month. Based on the height of last year’s range, an upside measured move price objective to the low $70s is in play.
Overall, the trend is solid, and I see support in the high $40s.
JXN: Upside Breakout, Support in the High $40s
Stockcharts.com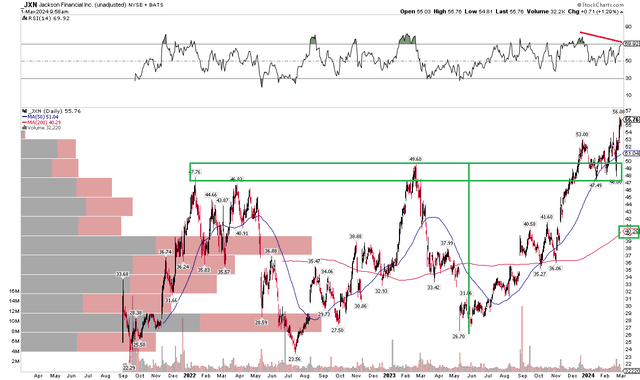
The Bottom Line
I reiterate my buy rating on Jackson Financial. I see the stock as about fairly valued today, but there are fundamental industry growth tailwinds that should sustain this high-momentum stock in 2024.
Credit: Source link