SDI Productions
Most investments end up running their course at some point or another. Either the fundamental condition of the business in question deteriorates to the point that it no longer makes sense to own, or shares appreciate enough that additional upside is limited. An example of the latter occurring involves a bank by the name of Bank7 (NASDAQ:BSVN). Back in early October of last year, I ended up writing a bullish article about the firm. Despite contending with challenging industry conditions, the company had experienced significant growth when it came to loans, deposits, cash, and securities. What made the institution unique was the absence of any debt on its books. There were also some other positive fundamental indicators such as rising revenue and profits.
All of these factors, combined, made me bullish about the bank. At the end of the day, I ended up rating it a ‘buy’ to reflect my view at the time that the stock should outperform the broader market for the foreseeable future. Fast forward to today, and that is precisely what has transpired. While the S&P 500 is up 23.4% since the time that article was published, shares of Bank7 have seen upside of 26.5%. With this increase, it might be tempting for investors to hold on for additional upside. And given the quality of the assets we are looking at, I don’t think I can blame somebody for thinking that way. But for a value-oriented investor like myself that prioritizes affordability, shares have gotten to the point where a downgrade is justified.
Time for a downgrade
In most respects, Bank7 has demonstrated itself to be a high-quality institution. But before I get into some of those figures, I would like to touch on some of the reasons why I’ve decided to downgrade the bank. For starters, as of late, we have seen some weakness when it comes to deposits. Despite concerns in the banking sector last year that caused a flight of capital from depositors to other assets, the value of deposits at the institution had grown from $1.43 billion in 2022 to $1.51 billion in the second quarter of 2023. By the third quarter of the year, deposits had grown further to $1.59 billion. But by the end of 2023, they pulled back slightly, about $2.2 million in all. This still rounds out to $1.59 billion. But in the chart below, you can see the dip. It is worth noting, by the way, that while deposits have fallen, they do remain below the threshold that I prefer when it comes to uninsured deposits. I typically prefer a reading of 30% or less. And at 28.2%, Bank7 fits the bill.
Author – SEC EDGAR Data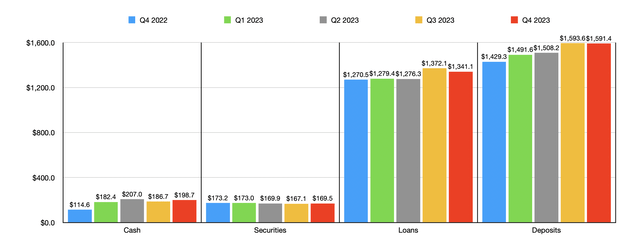
The value of loans saw a more noticeable drop. At the end of 2022, loans at the bank totaled $1.27 billion. By the third quarter of the year, they had grown to $1.37 billion. But then, by the final quarter, we saw a drop to $1.34 billion. I do understand that one thing many investors are worried about in the banking sector right now is exposure to office assets. The good news for investors is that, as of the end of the most recent quarter, only about 8.2% of the value of loans on the firm’s books are dedicated to office properties. Over this same window of time, both cash and securities has remained in a fairly narrow range. There is not a clear trend when it comes to either of these. Another important topic would be debt. Many institutions in the financial sector carry that. And during the banking crisis, many took on additional debt in order to boost liquidity and assure investors that they would have capital in the event of a potential bank run. However, Bank7 has remained debt free throughout that time.
Author – SEC EDGAR Data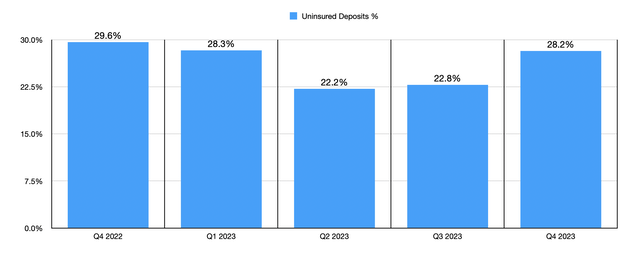
In terms of the balance sheet, there are few institutions as healthy as Bank7. However, I am not a fan of the decline in deposits, even though it is fairly small and is not necessarily the start of a trend. If this were the only problem that I had with the company, I would still keep it rated in a bullish manner. However, there are some other weak spots worth mentioning. Consider the final quarter of the 2023 fiscal year. During that time, net interest income totaled only $5.8 million. That’s well below the $18.8 million the institution generated during the final quarter of 2022. Some of this pain undoubtedly came from a decline in the firm’s net interest margin. During the final quarter of 2023, this totaled 4.85%. That’s down from the 5.25% reported one year earlier.
Author – SEC EDGAR Data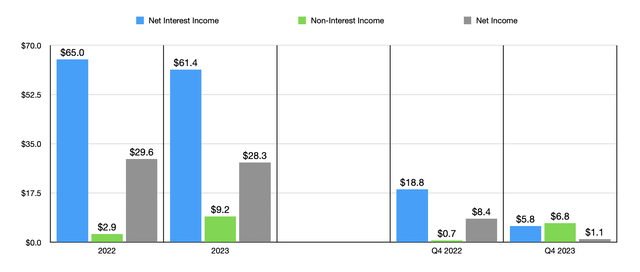
Having said that, an increase in time deposits from $157.2 million as an average balance in the final quarter of 2022 to $254.5 million as an average balance in the same quarter of 2023, combined with a surge in the average rate paid on those deposits from 1.49% to 4.47%, was instrumental in pushing interest expense for the institution up from $0.6 million to $2.9 million. Transaction accounts saw an even greater increase from $4.5 million to $8.2 million for the amount of interest the institution had to pay. And that’s because, in addition to seeing a rise in net interest expense, the firm also reported an increase in the balance of these transaction accounts from $798.1 million to $849 million.
While net interest income declined rather significantly, non-interest income saw a rebound. It went from only $0.7 million in the final quarter of 2022 to $6.8 million the same time of 2023. But even this meaningful improvement did not stop net profits from tanking from $8.4 million to a paltry $1.1 million. It is worth mentioning that, even with that bottom line pain, net profits for 2023 as a whole we’re not entirely sunk. For the year, the company booked a profit of $28.3 million. That’s only a slight decline from the $29.6 million reported one year earlier.
Author – SEC EDGAR Data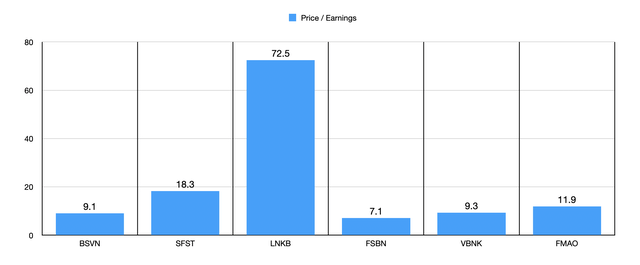
With the profits generated in 2023, we can see that Bank7 is trading at a price to earnings multiple right now of 9.1. That’s typically within the range of what I like to see. When it comes to this space, I prefer price to earnings multiples of between 6 and 10. And in fact, as you can see in the chart above where I compare Bank7 to five similar firms, only one of the five institutions ended up being cheaper than it. But that picture changes when we use other profitability metrics. In the chart below, you can see Bank7 stacked up against the same five companies. But this time, we are looking at both the price to book multiple and the price to tangible book multiple. In both scenarios, Bank7 ended up being the most expensive of the group.
Author – SEC EDGAR Data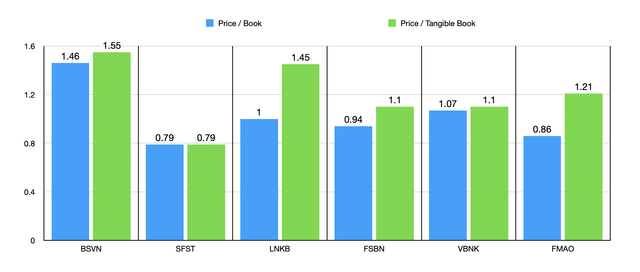
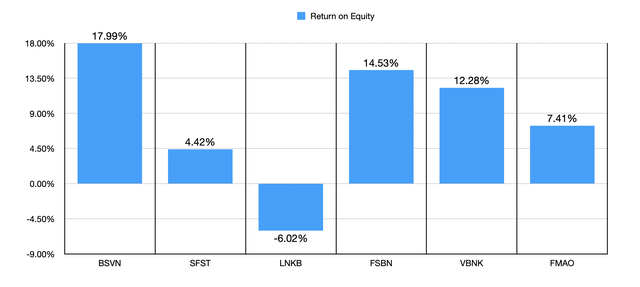
Some might argue that being expensive relative to book value is justified because of the absence of debt and because of the price to earnings multiple. The argument they would make is that, in addition to having those benefits, the company also has high quality assets. In the first chart below, I compared Bank7 to the same five companies using the return on assets. In this case, with a reading of 1.60%, Bank7 ended up out on top. With a reading of 17.99% for return on equity, as shown in the subsequent chart, our candidate was also at the top of the list.
Author – SEC EDGAR Data Author – SEC EDGAR Data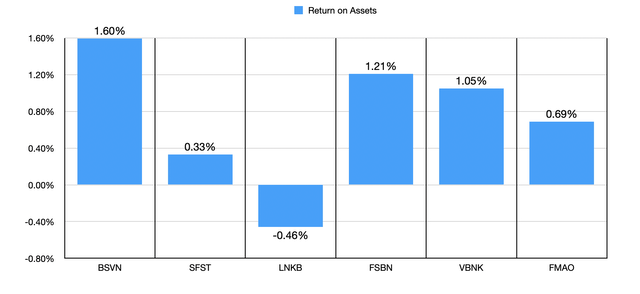
Takeaway
I want to be very clear when it comes to my thoughts on Bank7. The data we looked at throughout this article demonstrates that this is a very high quality institution. Its debt picture, combined with how cheap shares are relative to earnings, and how high both its return on assets and return on equity are, all bode well for investors. It’s also worth noting that, in October of last year, management renewed a 750,000 share repurchase program that is expected to last up to two years. So management is optimistic enough to be buying back stock. But on the other hand, you have an institution that has recently seen declines in both deposits and loans, even though they are fairly small. I also have a problem with how pricey the stock is relative to book value. While it does have high quality assets to its name, it’s not like those assets are bringing in significant non-interest income. If the institution had a much larger share of revenue typically coming from those activities, that picture might be more reasonable. Add on top of this how much shares have already appreciated in such a short window of time, and I believe that, while Bank7 should have a bright future ahead for it, the time for a downgrade has finally come. Because of that, I am now rating the company a ‘hold’, but it wouldn’t take much to justify a revision higher.
Credit: Source link