
Sundry Photography
Strong Q3 But Concerning Q4 Guidance
Atlassian (NASDAQ:TEAM) released its Q3 2024 earnings report on April 25, delivering strong revenue and EPS growth of 30% and 65% YoY, respectively (see below).
Atlassian Q3 earnings (Seeking Alpha)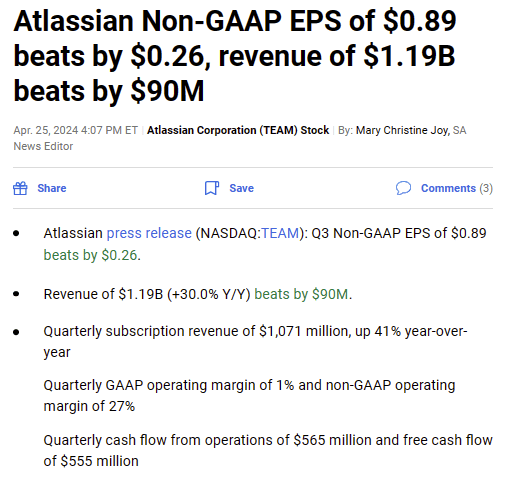
However, the market didn’t like the report, as the stock price declined due to concerns over Q4 guidance, and surprise Co-CEO step down.
In our previous article, dated March 1, we noted that Atlassian’s revenue deceleration was stabilizing, but warned about its high valuation. However, we held a Hold rating, believing the company was on the right track strategically.
March 1 Article (Seeking Alpha)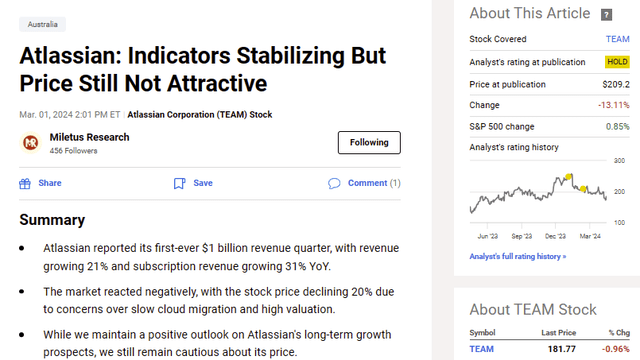
We maintain our original stance on the company’s growth potential; however, we continue to find the stock unappealing at its current price levels. Meanwhile, we’re now seeing some new red flags. The company’s SMB business is facing challenges that are impacting its cloud growth. We believe this is due to the changing market dynamics and intensifying competition.
Atlassian’s Path to $10B Revenue
Atlassian held its annual Investor Day on May 1st to share its strategic vision and its big bets. The company shared its long term financial objectives and outlined its strategy to achieve $10 billion revenue in the next five years. The company also shared its three-year financial targets until FY27 (See below).
Atlassian three-year targets (Atlassian Investor Day)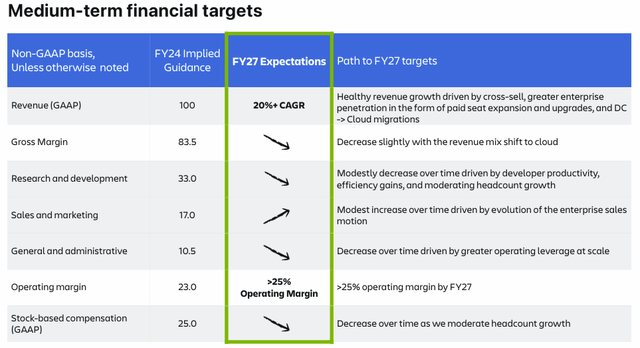
The key takeaway here is that the company is planning to grow at 20%+ CAGR over the next three years. This growth is projected to be driven by the following initiatives:
- Cross-selling to existing customer base.
- Enhanced product capabilities through AI
- Enterprise growth initiative.
- Upgrades to higher-value and premium service tiers.
- Ongoing Data Center to Cloud migrations
We think Atlassian can reach $10 billion in revenue in five years. It’s a realistic target, given its current momentum and its strategic bets. To hit this target, the company will need to grow at a rate of 18% per year, which is achievable if it can successfully execute its plans around AI, service management, enterprise growth, and cloud computing.
Strategic Initiatives on Track
We want to check on the progress of the company’s strategic initiatives based on the latest update.
- Cloud Migration: The Cloud migration initiative is ongoing. The Server product has been sunset in Q3 as part of the Cloud Migration program and the company says that the program has been an overall success. Cloud is now 61% of total revenue, up from 43% when the Server EOS was announced back in 2020. The company says that it has exceeded its original expectations and believes that many customers are moving first to the Data Center and then to the Cloud. Management thinks that there are still plenty of growth opportunities to keep migrating Data Center customers to the Cloud in the upcoming years (see below).
Atlassian Cloud Migration (Atlassian)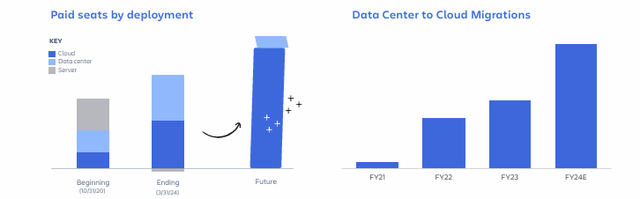
- Enterprise: Atlassian has been investing heavily on its enterprise capabilities in terms of product and GTM in order to better serve enterprise customers, as part of its growth strategy. As per the company’s Q3 report, the enterprise segment had another strong quarter, which resulted in large multi-year deals. We think that the company is successful on its Enterprise growth strategy, as large customer metrics continue to grow (see below).
Atlassian Large Customer Growth (Atlassian Investor Day)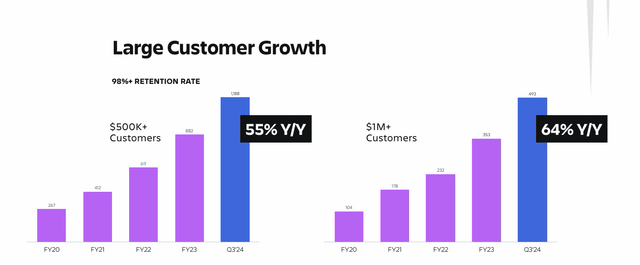
-
Service Management: The company is aiming high for its Enterprise Service Management (ESM) business. As of Q3 24, the company has now over 50,000 ESM customers with a $600 million revenue run rate (It is the company’s fastest growing scale product). We think that Atlassian has a strong value proposition on the ESM front, and we expect it to become a key growth driver for the company in the long term.
-
AI: We think the company is doing a good job on the AI front as it focuses on improving the customer experience and user productivity. As of Q3, it has added 30 AI features across its products and platforms. The company has also announced Atlassian Rovo, which is an AI-based knowledge discovery tool that integrates localized information, conversations, and AI agents into workflows. In the enterprise segment, there is high demand from customers to have specialized LLMs that are tailored for internal use with localized knowledge, customization and control capabilities. Atlassian Rovo looks to fulfill this need and the company is planning to sell this tool separately. We expect to see significant returns on the company’s AI investments especially in the enterprise segment.
Atlassian Roko (Atlassian)
The SMB Weakness
Atlassian operates in three main markets; software development, service management, and work management. According to the company’s market research, each market has the following growth attributes:
- The software development sector is valued at $17 billion, with an annual growth rate of 9%.
- The service management sector is estimated at $15 billion, expanding at 13% per year.
- The work management sector is projected to be $35 billion, increasing at a rate of 14% annually
Atlassian TAM (Atlassian Investor Day)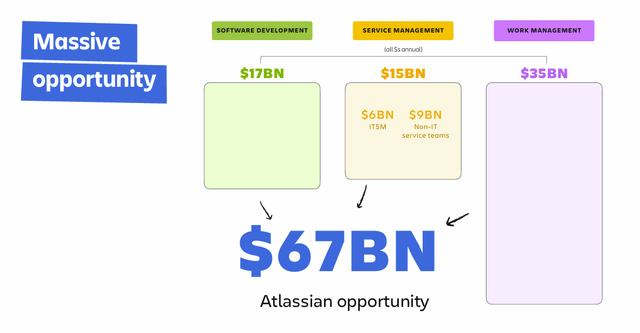
In total, Atlassian’s potential market size is $67 billion, with an overall growth trajectory of 13%. The company thinks that it’s well-positioned to capture these opportunities because of its unique competitive advantages, such as its comprehensive product platform and large sales ecosystem. However, we have some concerns based on our observations of how these three markets are evolving.
As organizations increasingly focus on technology, the boundaries between software development, service management, and work management are blurring. This leads to a more crowded market and a highly competitive environment.
Also, the AI advancements are bringing new productivity players into the market, which offer cost-effective and innovative solutions (e.g. Zapier, Notion, Creately, copy.ai, Mem.ai, Personal.ai, Airgram, etc.). This AI trend is making the markets more overlapping, and crowded, which we see as a risk for Atlassian.
Over the last two quarters, the company management has shared their concerns regarding the weak performance of its SMB segment. Since SMB’s constitute a significant portion of the cloud business, its underperformance creates a significant risk to the company’s growth strategy. From the Q3 Earnings call;
Joe Binz (CFO):
The macro impact on SMB, on the other hand, continued to be challenging, although also in-line with expectations. And that macro headwind in SMB lands primarily in cloud, given SMB makes up a significant part of that business.
We acknowledge the challenging macro environment, but we also think that Atlassian’s SMB segment has started to face competitive challenges due to the high compete environment and the evolution of new AI led productivity companies. Unlike the enterprise segment, the switching costs for productivity tools in the SMB space are relatively low. So we think that its SMB customers might be attracted to these new cost-effective solutions offered by other companies.
Operating Metrics Improved
Atlassian’s non-GAAP operating margin rose to 27% in Q3, a 5 percentage point increase from the same quarter last year. This was due to the ongoing cost management efforts across the business and its operating leverage. The outperformance on Data Center and marketplace revenue also benefited operating margins by 5 points. Non-GAAP Gross margin was 85% and flat YoY.
The company expects gross margins to decrease gradually, driven by the continued revenue mix shift to Cloud.
Atlassian Q3 margins (Atlassian)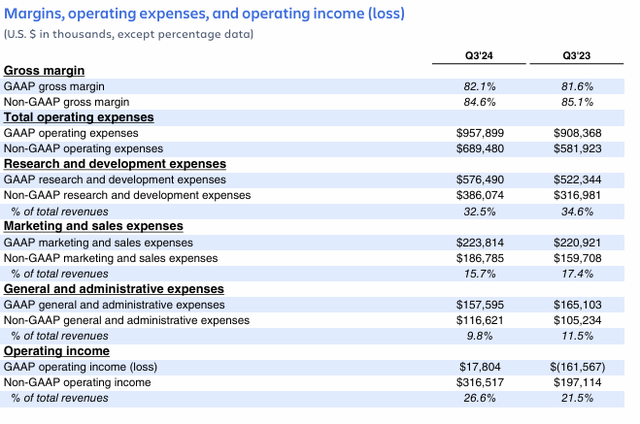
Atlassian’s long-term goal is balanced growth and profitability, with operating margins over 25%. We think the company can do even better, as there is plenty of room to increase its operating margins. By streamlining costs and focusing on higher-value service tiers, we think that the company can drive further efficiency and increase profitability.
Valuation Still Not Attractive
Atlassian’s market cap is around $48 billion, and its sales and earnings multiples are quite high considering its growth rate and industry averages.
- Forward P/E ratio : 64
- Forward: P/S ratio : 11
The company’s high valuation reflects its strong growth prospects and innovation potential, but the problem is that revenue growth has leveled off around 20% and the company is projecting similar growth rates for the next several years. Additionally, we see an increased risk of competition in the SMB space due to the changing market dynamics and AI disruption.
Atlassian valuation metrics (Seeking Alpha)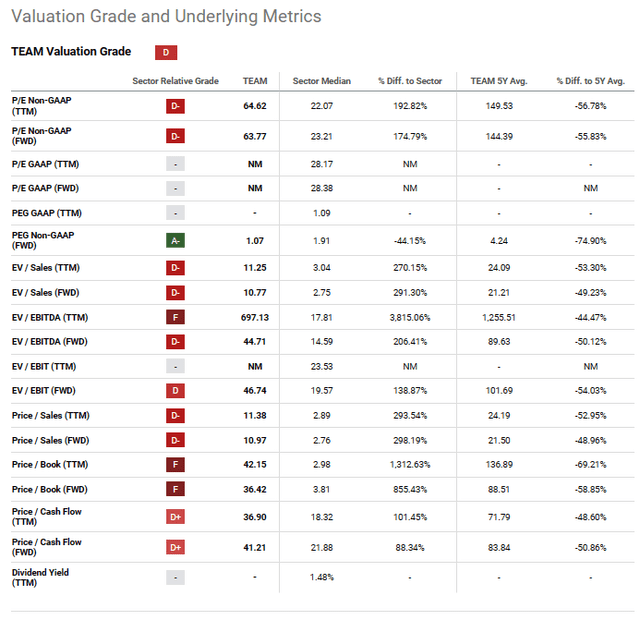
Despite recent sell-offs, Atlassian remains an expensive stock. We believe that the company needs to show revenue acceleration to deserve its 11 times sales multiple. Although revenue deceleration has stabilized and customer metrics are looking better, we are not seeing any revenue acceleration in the near term.
Conclusion – We remain cautious
Atlassian had a good quarter, with strong enterprise sales, rapid growth in its ESM business, and many AI integrations. However, we can’t ignore the increasing competition in the SMB space – it’s a risk to its long-term growth plan.
While we maintain a positive outlook on Atlassian’s long-term growth potential, we remain cautious regarding its risk/reward ratio. To justify its current price, the company needs to deliver stronger revenue growth in the coming quarters. We recommend investors keep a close eye on Atlassian’s performance, especially where AI and market competition meet.
We maintain our Hold rating on TEAM stock for now.
Credit: Source link