
Pekic
Investment Thesis
Zoom Video Communications, Inc. (NASDAQ:ZM) delivered fiscal Q4 2024 results and fiscal 2025 guidance that saw its shares sizzle higher by more than 10% premarket. However, I declare that this rally is little more than a relief rally that Zoom’s outlook is not worse.
Even though the business continues to deliver very strong free cash flows, while carrying a massive amount of cash on its balance sheet, I declare that its stock isn’t worthwhile chasing, even as there are a few alluring nuggets to draw investors to this name.
Rapid Recap
Last month, I said in a neutral analysis, I said:
[…] For investors, what truly matters is whether the stock offers investors a compelling risk-reward. No investor gets all stock picks right. But our job is to deploy capital, and to do so selectively, only when we believe that the stock offers investors a very compelling risk-reward.
Given Zoom’s current prospects, I do not believe this stock offers investors a compelling risk-reward. Therefore, I remain neutral on this name, as I’ve been for a while.
Author’s work on ZM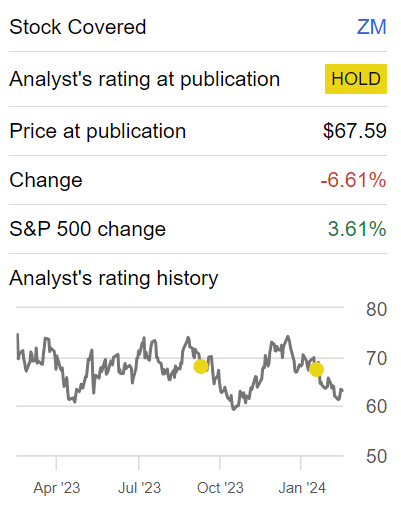
Zoom had been sliding as it headed into this earnings report with the stock underperforming the S&P 500 (SP500) in a very strong market environment. However, even as I am able to remark on some positive elements in this report, there’s not enough here to get me to assert a bullish rating on this name.
Why Zoom? Why Now?
In the near term, Zoom remains focused on the expansion of product offerings. The introduction of the Zoom AI Companion has not only demonstrated the company’s commitment to innovation but has also provided customers with a tool to enhance their productivity.
Notably, Zoom Team Chat has experienced a remarkable 130% growth in usage across paid accounts over the past year, showcasing its widespread adoption. As customers migrate from other chat platforms to Zoom, the company is positioned as a comprehensive workplace solution, driving customer loyalty.
Despite the challenging macroeconomic backdrop, Zoom has demonstrated financial resilience in fiscal 2024, with a 24% y/y increase in free cash flow (more on Zoom’s free cash flow below).
However, Zoom also faces challenges related to its growth rates. Zoom’s fiscal Q4 2024 total revenue growth of 3%y/y indicates a lack of reacceleration is on the cards for fiscal 2025.
Moreover, the company’s acknowledgment of a trough in year-over-year growth in fiscal Q2 2025 suggests a need for strategies to reinvigorate its trajectory. The challenges are further underscored by the relatively flat performance in the EMEA region and a decline in APAC, indicating potential saturation in these markets.
Given this background, let’s now discuss its outlook for fiscal 2025.
Revenue Growth Rates Expected to Reach 3% to 5% CAGR
ZOOM revenue growth rates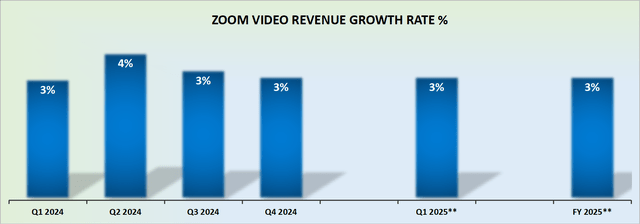
Zoom’s outlook for fiscal 2025 points to approximately 3% to 5% top-line growth. To substantiate this contention, keep in mind the following table.
SA Premium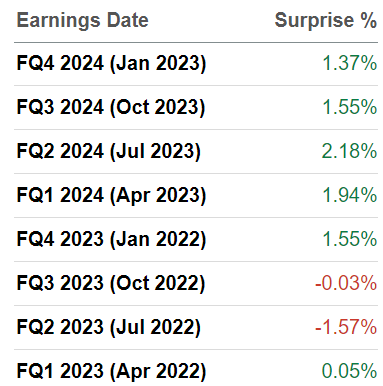
Zoom, for the most part, beats revenue estimates by approximately 1% to 2%. The days when Zoom could be counted on to massively beat revenue estimates are now a distant memory.
Despite comparing with a lower revenue growth rate hurdle with the prior year, Zoom is no longer a rapidly growing tech business. Therefore, its likely shareholder base is more likely than not going to come from the value camp.
Consequently, for Zoom to attract value investors to its name, it will convincingly demonstrate that it has what it takes to grow its underlying free cash flows, beyond just one-off cost-cutting measures. Given this context, we’ll now turn to discuss its valuation.
ZM Stock Valuation — 12x Forward Free Cash Flows
On the one hand, there’s a lot to like about Zoom. After all, Zoom has no debt on its balance sheet and a whopping amount of cash. More specifically, including the premarket jump, 35% of Zoom’s market cap is made up of cash and equivalents.
Needless to say that this is a tremendous amount of cash for a business that is clearly highly free cash flow generative. However, the problem here I assert has to do with tackling these two considerations:
- What Zoom plans to do with this excess cash?
- How long will it take for this cash to return to shareholders?
Even if Zoom mindlessly repurchases its shares, the time it takes for investors to get hold of those repurchases matters to investors’ return.
After all, Zoom’s share buyback presently stands at $1.5 billion, which is a paltry figure compared with $7 billion of cash on its balance sheet. And on top of that, the share repurchase program is open-ended, with no due date.
And then, further confounding matters, the outlook for fiscal 2025 points to approximately $1.5 billion of free cash flow, which is practically identical to fiscal 2024. Consequently, it shows investors that most of the cost-cutting that was possible to take place has already taken place in fiscal 2024 (the year just reported).
The Bottom Line
In summary, Zoom Video’s fiscal Q4 2024 results led to a premarket surge, yet this seems more like a relief rally than a strong endorsement.
Despite robust free cash flows and a significant cash reserve, the stock lacks an enticing proposition for investors.
The forecast for fiscal 2025 indicates modest revenue growth rates of 3% to 5%, pointing to a more mature growth stage. Valuation-wise, Zoom’s stock trades at approximately 12 times forward free cash flows, but questions arise about the company’s plans for excess cash utilization and the timeline for returning it to shareholders.
Overall, I remain neutral on Zoom Video Communications, Inc. stock.
Credit: Source link