
MarkGillow/E+ via Getty Images
Investment thesis
On the 24th of August, I wrote an article about Utz Brands, Inc. (NYSE:UTZ) and I stated that the risk/reward was unattractive. Since then, the share price has risen significantly. However, I personally think that the fundamentals of UTZ have not necessarily improved.
Despite the fact that UTZ is a very small position in my portfolio (approximately 1%) I thought it was a good moment to sell. I really love the buy and hold strategy, but I don’t see any potential in the company at the moment, especially not at these price levels.
Nevertheless, it is sometimes good to say goodbye to certain positions, especially if the conviction is not there.
Of course, it is always a personal decision to make, but today I am going to take you through my reasoning process why I think UTZ is a “SELL” at current prices.
UTZ share price development (Seeking Alpha)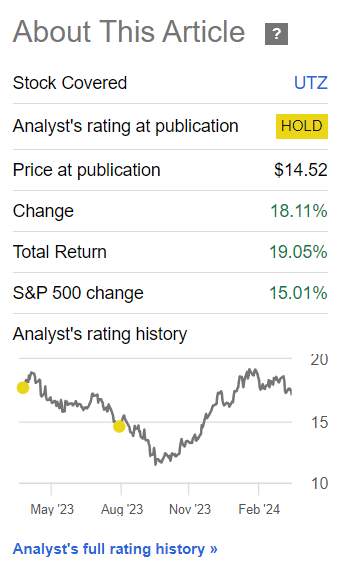
Financials
One of the reasons I decided to sell UTZ is the lack of growth. I think that the overall interest in the company came from the growth story. A company that has existed for more than a hundred years and is coming to the stock exchange in order to be able to expand nationally.
From the moment that UTZ went public in 2020, they grew their revenue with a CAGR of 10.5%. Not bad, but to be expected from a growth company. However, it is important to mention that the growth in revenue has been helped by inflation. It is striking that growth has fallen sharply in the last year, and it is clear that UTZ hasn’t been able to keep up margins.
UTZ financials (YCharts)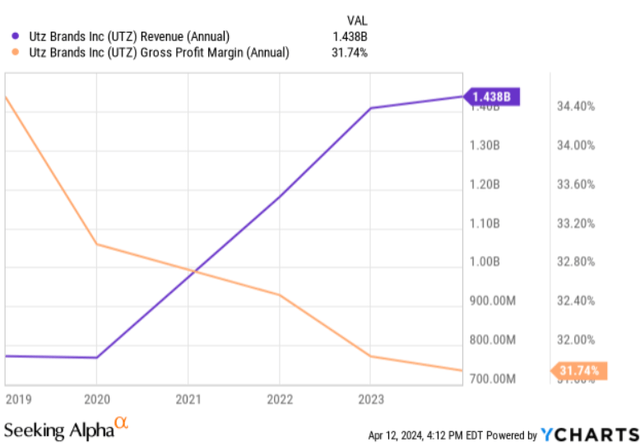
So, let’s take a look at the latest quarterly results and FY 2023 results. Just as the chart suggests, the net sales growth in FY 2023 was just 2%.
Net sales were actually lower in Q4 2023 compared to Q4 2022 (-0.7%). However, UTZ had experienced growth in volume/mix of 3%, this was negatively offset by SKU rationalization (-2.5%).
Q4 2023 net sales bridge (UTZ quarterly results presentation)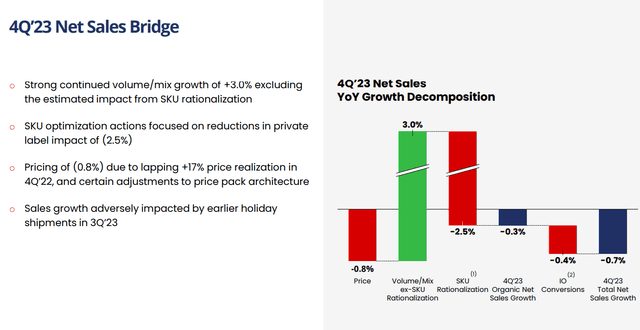
The outlook for 2024 is also on the poor side when it comes to organic net sales growth (around 3%). Of course, the numbers are negatively affected by the disposition of Good Health and R.W. Garcia Brands.
UTZ FY 2024 outlook (UTZ quarterly investor presentation)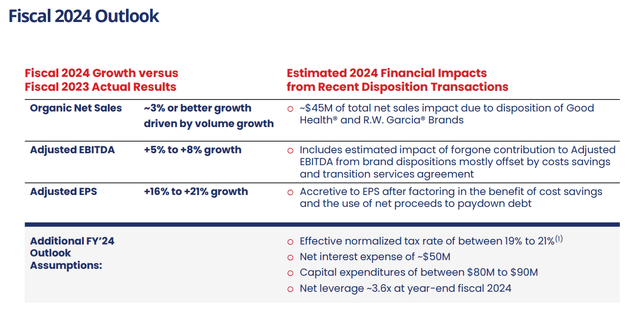
From a profitability perspective, UTZ is also struggling. Earlier in the article, we saw that the gross margin is still dropping. The company itself prefers to report adjusted EBITDA and adjusted earnings per share growth.
UTZ growth numbers (Full year overview presentation)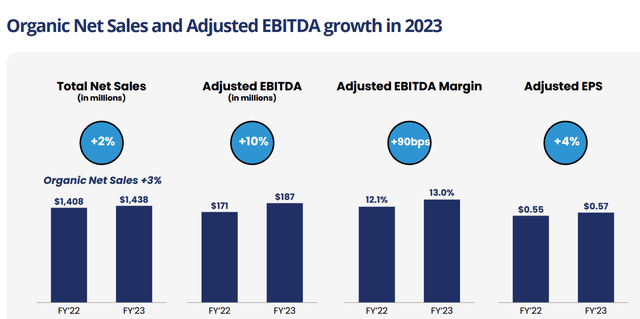
Over the past year, the company was able to grow adjusted EBITDA by 10% and adjusted EPS by 4%. Based on the outlook, they expect to grow their adjusted EBITDA between 5-8% and the adjusted EPS in the 16-21% range. The company is trying to increase profitability through cost savings and focus more on their power brands.
Personally, I don’t like the large amount of “adjusted” metrics. This can give a distorted picture of UTZ’s capacity to generate cash flow.
UTZ Net income and EBITDA (Q4 2023 press release)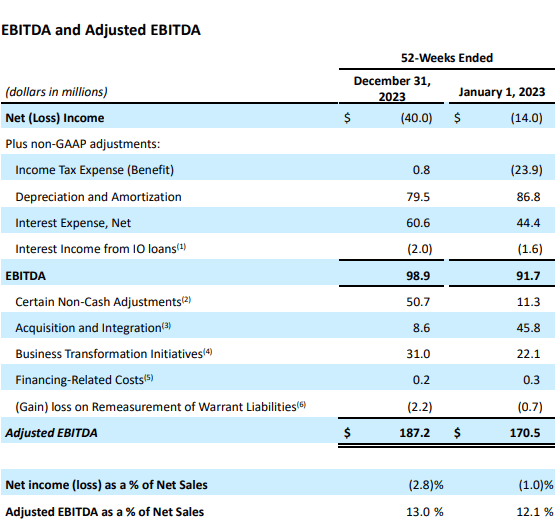
Based on the Q4 2023 earnings release, UTZ is still making a net loss of $40 million. This is a significant increase compared to the previous year, but the main difference was the income tax expense benefit.
If we follow the steps from net income to EBITDA, the high interest expense is also very noticeable. This also puts enormous pressure on profitability and is something that is, of course, not taken into account in EBITDA.
The free cash flow is also far from stable, but it is improving a bit lately.
UTZ FCF development (YCharts)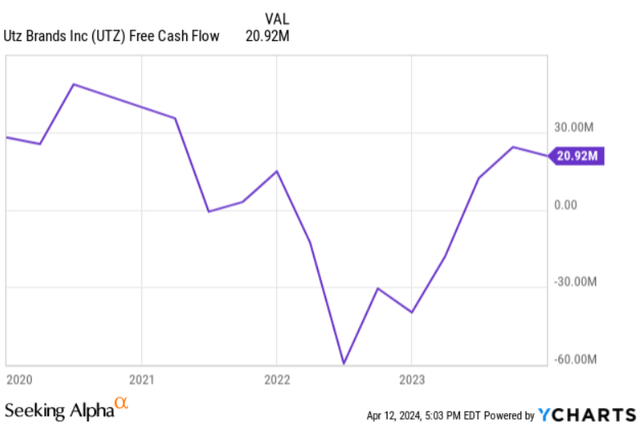
UTZ’s cash from operations is growing steadily over the years, and they had less CapEx in FY 2023.
UTZ Cfo and CapEx (Seeking Alpha)
In the latest earnings call, the CFO, Ajay Kataria, said that they expect the free cash flow will be around $20-$30 million in FY 2024. This is also related to an expected increase in CapEx (approx. $80 million). This could indicate the lack of significant growth in free cash flow next year.
Balance sheet
This is a point I have written about several times. UTZ has a vulnerable balance sheet, which leads to high interest expense.
UTZ balance sheet highlights (UTZ Q4 earnings presentation)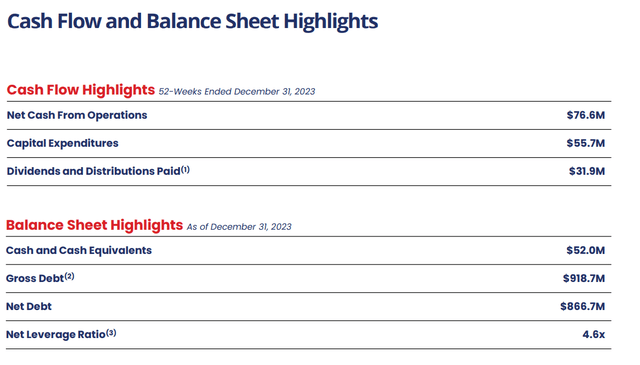
What I like from management is that they used the $150 million of net proceeds to pay down long-term debt and, as a result, the net leverage ratio has fallen from 5.0x to 4.6x.
UTZ net leverage ratio goals (UTZ Q4 earnings presentation)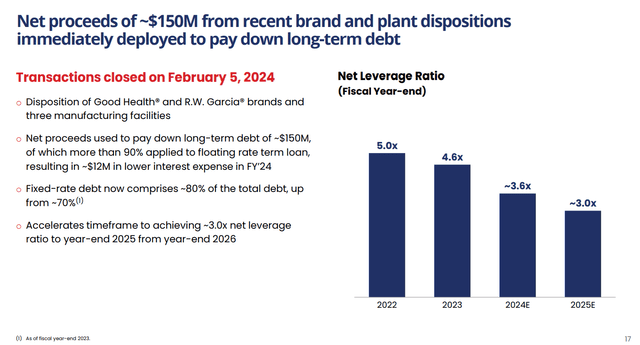
However, it must be noted that the leverage ratio is based on adjusted EBITDA and there is a possibility that the current Net leverage Ratio overstates the ability to pay down debt. In addition to this, the company isn’t generating enough FCF to bring down debt in a sustainable way. The FCF of $20.9 million is also not enough to outweigh the interest expenses of $60.5 million. This could also make investing in longer-term growth more difficult.
Dividend
Since I am a dividend growth investor, the dividend was also part of my original investment thesis. Considering the dividend grades on the Seeking Alpha website, it now seems anything but attractive.
Dividend grades (Seeking Alpha)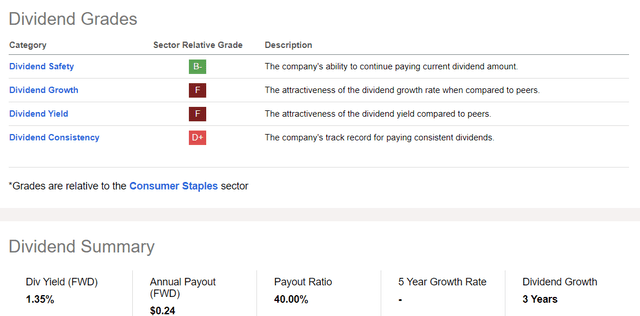
Currently, UTZ has a dividend yield of 1.35%, which isn’t that high. Of course, this does not have to be a problem if it is combined with high dividend growth. This is just not the case, as the company increased its dividend by 3.5% lately. And let’s be honest, at this point it wouldn’t be wise to increase it quickly as the total dividend paid out ($31.9 million) is currently higher than the FCF ($20.9 million). From a capital allocation perspective, it might even be wiser not to grow the dividend at all but to use it for other purposes such as investing in durable growth or reducing debt.
Valuation
In short, I am not enthusiastic about UTZ and I also think the company is too richly valued.
UTZ Valuation grade (Seeking Alpha)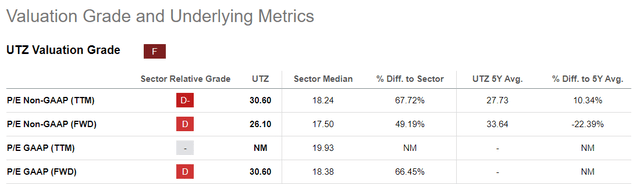
Personally, I don’t think this is justifiable as their growth is below par and the company still struggles to generate cash. I don’t mind paying a high multiple for a company, but that the moment UTZ doesn’t have the characteristics of a high-quality business.
To be able to make an estimate of the fair value, discounted cash flow analysis has been used.
For the analysis, I used an FCF of $25 million. As previously described, the expectations for next year are an FCF between $20-$30 million. Based on the earnings estimates on the Seeking Alpha website, analysts seem to be positive with regard to the development of the EPS.
Earnings estimates UTZ (Seeking Alpha)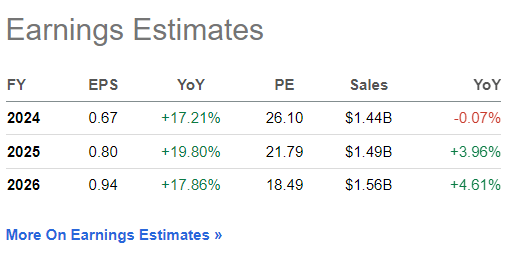
I expect that UTZ will be able to improve its FCF in the coming years. Based on their current track record, I will be conservative in my assumptions.
I think a 5Y FCF growth of 12% is reasonable because I think there is room for improvement in operational efficiency. I used 8% for the 5 years thereafter because it is more difficult to make assumptions further into the future.
A terminal multiple of 20 has been used because, in my opinion, the P/E of UTZ should be closer to the sector median of 18. However, the company still has quite a bit more growth potential, so I have valued it somewhat higher.
Finally, I used a discount rate of 10% as a personal hurdle rate I demand for a consumer staple stock like UTZ.
DCF analysis (Google spreadsheets)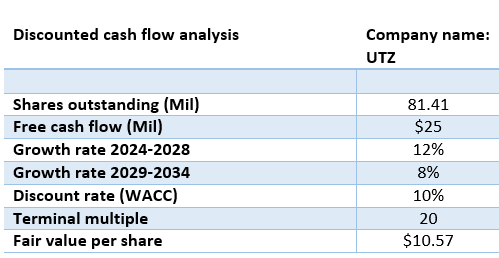
If we do the math, this comes to a fair value of $10.57 per share, which is significantly overvalued compared to the current share price of $17.15.
Conclusion
Based on the arguments above, I decided to give UTZ a “SELL” rating. Personally, I think the fundamentals and the share price have grown too far apart. The disappointing top-line growth, poor profitability metrics and high debt levels weighed heavily on this decision.
I do expect that UTZ’s profitability will improve in the future, but this does not outweigh the high valuation at which it currently trades. UTZ will also have to prove that it is capable of growing towards sustainable FCF generation. This is important to reduce debt and to potentially build a sustainable dividend track record. It is certainly possible that my DCF assumptions are too conservative, but given the outcome, the results will have to be considerably better to justify the current share price.
Despite the fact that UTZ is a long-term play, I don’t think it’s a bad thing to sit on the sidelines until these fundamentals improve or the share price drops again.
Hopefully, this article has given you some food for thought, and I am very curious about your views on UTZ.
Happy investing everyone!
Credit: Source link