
hapabapa
Introduction & Investment Thesis
Twilio (NYSE:TWLO) is a customer engagement platform that provides communications application programming interfaces (“APIs”) so that businesses can drive targeted engagement with their customers, creating loyalty and customer value. The company has underperformed the S&P 500 and Nasdaq 100 YTD. I initiated a “hold” rating on the stock in early April, and my thesis was predicated on my belief that the risk-reward did not look attractive, as the management had yet to prove that it could successfully reignite growth as it was seeing a declining net-dollar expansion rate while simultaneously optimizing for profitability.
The company reported its Q1 FY24 earnings, where revenue and earnings grew 4% and 54% YoY, respectively, beating estimates. While the management has raised its profitability guidance for the full year, it has kept its revenue guidance unchanged. As a result, investor sentiment continues to remain dampened, with the stock declining close to 9% since the time of my writing, underperforming the indices.
However, I believe that the Q1 FY24 earnings report demonstrated the management’s commitment towards improving profitability while driving targeted innovation to natively embed Segment into its Communications products, thus accelerating its customers’ time to value and deepening adoption as a result. Meanwhile, it is leveraging its global partners to land larger deals as well as drive cross-sell momentum. I believe this may have contributed to stabilizing its net-dollar expansion rate, which remained unchanged month over month. While we are yet to see a re-acceleration in growth, I believe the management is taking the steps in the right direction to create the required foundation.
Assessing both the “good” and the “bad,” I believe the stock is attractively priced from a risk-reward perspective to deliver significant returns over a 3-year investment horizon, especially should growth re-accelerate in the low teens range, making it a “buy”.
Revenue growth is still slow, but management is making progress on profitability.
Twilio reported their Q1 FY24 earnings, where they saw their revenue grow 4% YoY to $1.05B. While its Communications business contributed 92.5% of Total Revenue growing 4% YoY, its Segment business contributed the remaining 7.5% of Total Revenue, while growing at a slower pace of 2%. Meanwhile, its non-GAAP operating income is close to 54% YoY to $159.6M, with a margin of 15.2% driven by its Communications business, which did all of the heavy lifting with a margin of 25.6%, as opposed to its Segment business, which dragged down the overall figure as it is operating at a loss with a margin of -28%.
During the earnings call, management reiterated its commitment to breaking even on Twilio Segment in Q2 FY25 on a non-GAAP operating income basis, as it focuses on operating with greater financial discipline and rigor while driving superior product innovation through targeted R&D investments. Plus, the management also raised its profitability guidance for the full year FY24 from the previous range of $550-$600M in non-GAAP operating income to a range of $585-$635M.
Q1 FY24 Earnings Slides: Revenue growth across quarters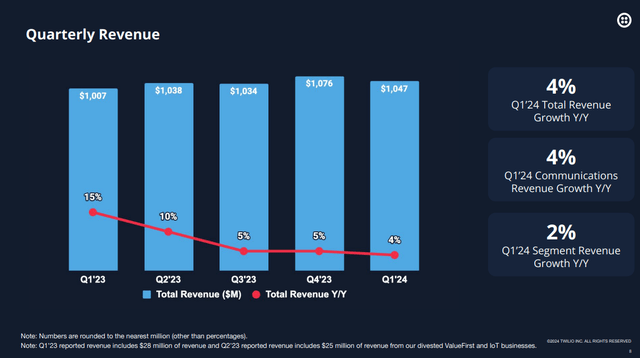
Targeted product innovations to accelerate time to value and drive business growth
In terms of their go-to-market strategies, the company is expanding their network of global partners to drive cross-sell momentum while simultaneously innovating their product roadmap to build better synergies between their Communications and Segment products to win larger deal sizes. During the quarter, Twilio announced Agent Copilot in beta, which will natively embed Segment into Twilio’s Communications products, leading to higher agent productivity and reduced resolution times through intelligent routing and providing actionable insights for customer interactions. I believe that as the company focuses on reigniting growth in its Segment business, these kinds of targeted innovations will enable customers to realize faster time-to-value. At the same time, the company has been getting positive responses from customers who are using their Voice Intelligence, which it launched in beta in Q4 to extract insights from call recordings and provide personalized communications based on the sentiment of the overall conversation.
Dollar-based Expansion declined from the previous year, while management kept its revenue guidance unchanged
However, dollar-based net expansion continues to shrink from 106% in the previous year to 102% in the latest quarter, indicating that customers are not extending their usage or adoption of new products at the rate that they once used to. However, I will note that the figure remains unchanged from the previous quarter, indicating that there might be some stabilization along the way. During the earnings call, Aidan Viggiano, CFO at Twilio, mentioned that they are seeing year-over-year growth in most of the industries they operate in; however, they are hesitant to raise revenue guidance as growth in internationally terminating traffic is still low, while they also sunset their Zipwhip software product, which will be a headwind to growth.
Q1 FY24 Earnings Slides: Net dollar expansion rate across quarters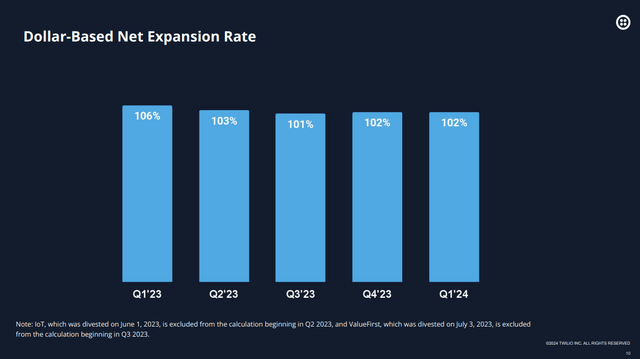
Revisiting my valuation: Twilio provides an attractive buy point.
Looking forward, the management has kept its revenue guidance for FY24 unchanged at 5–10% while raising their guidance for non-GAAP operating profit to approximately $610M. Assuming that the management’s focus on accelerating their AI-driven product launches throughout the year continues to natively embed Segment into its Communications products, thus accelerating time to value for customers and enabling them to deepen adoption among existing customers while acquiring new ones as the macroeconomic environment improves, it should go back to growing in the low teens range over the next two years, resulting in a total revenue of approximately $5.5B by FY26.
Simultaneously, I believe that the company will continue to see margin expansion as it drives targeted product innovation and go-to-market strategies with global partners, enabling them to land larger deals and unlock operating leverage in the process. Assuming that non-GAAP operating margin improves from a projected 13.7% in FY24 to at least 15% in FY26, it should generate $824M in non-GAAP operating income, which is equivalent to a present value of $680M when discounted at 10%.
Taking the S&P 500 as a proxy, where its companies grow their earnings on average by 8% over a 10-year period, with a price-to-earnings ratio of 15–18, I believe that Twilio should trade at least at 1.25 to 1.3 times the multiple, given the growth rate of its earnings, during this period of time. This will translate to a PE ratio of 22, or a price target of $86, which represents an upside of 53% from its current levels.
Author’s Valuation Model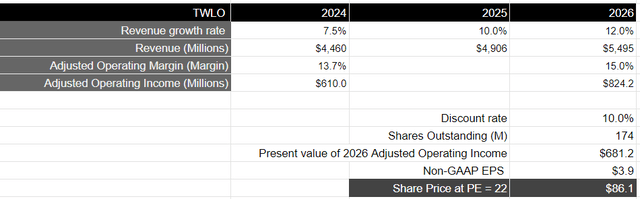
My verdict and conclusions
Although the management has yet to see an acceleration in revenue growth from its strategic initiatives so far, I believe we may be at an inflection point, where we are seeing some stabilization in the dollar-based expansion rate, especially, as the company drives its AI-led production to natively embed Segment into its Communications products to accelerate time to value for customers. Simultaneously, I am also optimistic about the growing profitability landscape given increased financial discipline, which will enable the company to produce free cash flow to drive targeted R&D-related investments. Assessing both the “good” and the “bad,” I believe that the stock is trading at an attractive valuation given the risk-reward at the moment to initiate a small position as we continue to monitor the progress of the management’s initiatives to reignite growth in the business.
Credit: Source link