
Erik Isakson
By Yan Taw (YT) Boon
Asia is fast becoming a data-center powerhouse, supported by rapid infrastructure growth, significant investment and favorable government policies.
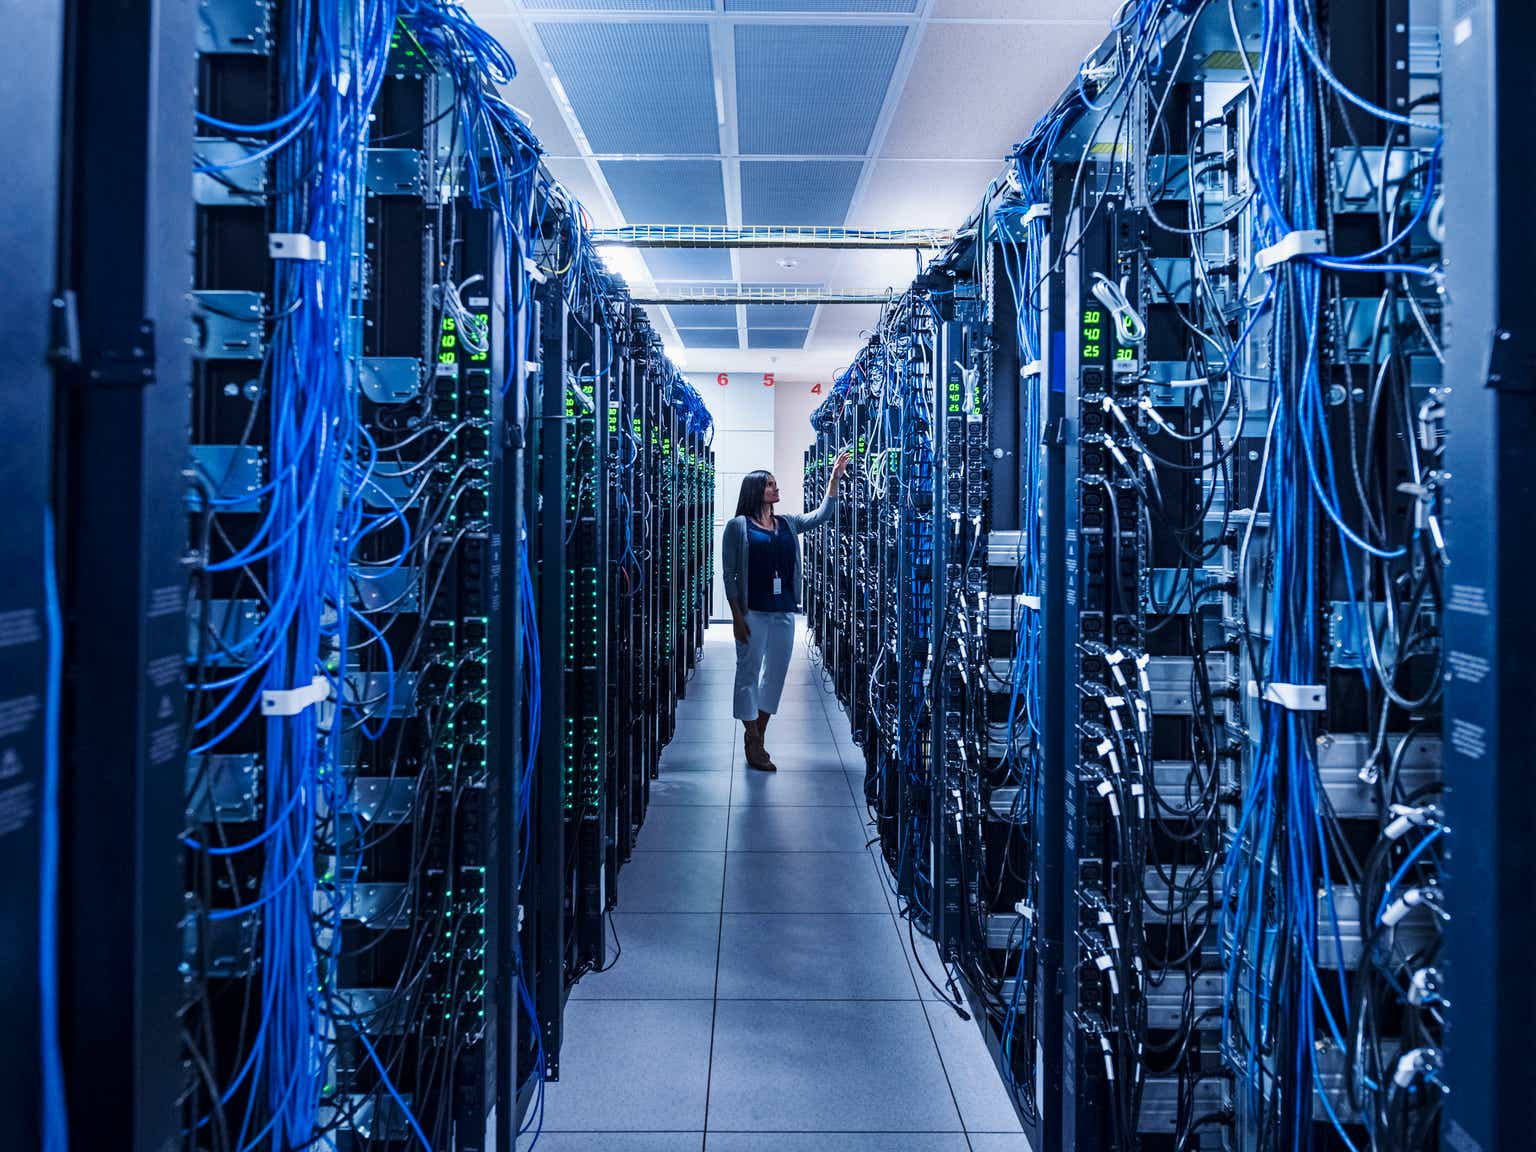
Data centers are increasingly becoming the backbone of our digital future. While the U.S. still boasts the most data center sites globally, an even more exciting story is unfolding in Asia, where rapidly growing economies, increasing population density and the rapidly unfolding AI revolution are spurring the rise of new data center players and regional clusters.
Because AI data centers require vast amounts of space, energy and water for cooling, we believe Asia’s affordable energy and land costs—coupled with supportive government policies—make many Asian outposts ideal locations for these facilities.
Global tech giant Nvidia (NVDA) has partnered with companies in Singapore, Indonesia, India, Vietnam, and Malaysia to strengthen the data center supply chain across the region by leveraging its full-stack AI platform.1 Nvidia’s comprehensive suite of hardware and software solutions is designed to optimize performance and ensure seamless integration among data centers.
Meanwhile, Malaysia’s Johor, located near Singapore, has become a hotspot for data center development, while the cooler and breezier regions of Hokkaido and Tohoku in Japan—which have embraced wind power generation—are also gaining prominence.
Asia’s favorable conditions have attracted global tech leaders seeking to reduce costs and bring services closer to end-users, minimizing latency and enhancing the quality of service. Google (GOOG)(GOOGL) has announced a $2 billion investment to build its first data center and a Google Cloud hub in Malaysia,2 and Microsoft (MSFT) is reportedly investing $3.7 billion in the construction of data centers in Telangana, South India.3
We expect these investments will inject fresh life into the market: According to consultancy Renub Research, the Asia Pacific data center market is projected to surge to roughly $72 billion by 2032, up from nearly $25 billion in 2023—a CAGR of 12.6%.4
Asia’s chip-making prowess already made it a crucial player in the AI revolution. Becoming a data-center powerhouse, in our view, should only further solidify its position as a cornerstone of the global digital landscape.
Sources: (1) Neuberger Berman Research; (2) AP, “Google to invest $2 billion in Malaysian data center and cloud hub”, May 30, 2024; (3) Coin Geek, “US tech majors invest in India data centers, AI innovation”, June 27, 2024; (4) Renub Research, “Asia Pacific Data Center Market Report.”
This material is provided for informational purposes only and nothing herein constitutes investment, legal, accounting or tax advice. This material is general in nature and is not directed to any category of investors and should not be regarded as individualized, a recommendation, investment advice or a suggestion to engage in or refrain from any investment-related course of action. Investment decisions and the appropriateness of this material should be made based on an investor’s individual objectives and circumstances and in consultation with his or her advisors. Information is obtained from sources deemed reliable, but there is no representation or warranty as to its accuracy, completeness or reliability. All information is current as of the date of this material and is subject to change without notice. The firm, its employees and advisory accounts may hold positions of any companies discussed. Any views or opinions expressed may not reflect those of the firm as a whole. Neuberger Berman products and services may not be available in all jurisdictions or to all client types. This material may include estimates, outlooks, projections and other “forward-looking statements.” Due to a variety of factors, actual events or market behavior may differ significantly from any views expressed.
This material is not intended as a formal research report and should not be relied upon as a basis for making an investment decision. The firm, its employees and advisory accounts may hold positions of any companies discussed. Specific securities identified and described do not represent all of the securities purchased, sold or recommended for advisory clients. It should not be assumed that any investments in securities, companies, sectors or markets identified and described were or will be profitable.
Investing entails risks, including possible loss of principal. Investments in hedge funds and private equity are speculative and involve a higher degree of risk than more traditional investments. Investments in hedge funds and private equity are intended for sophisticated investors only. Indexes are unmanaged and are not available for direct investment. Past performance is no guarantee of future results.
This material is being issued on a limited basis through various global subsidiaries and affiliates of Neuberger Berman Group LLC. Please visit www.nb.com/disclosure-global-communications for the specific entities and jurisdictional limitations and restrictions.
The “Neuberger Berman” name and logo are registered service marks of Neuberger Berman Group LLC.
© 2009-2024 Neuberger Berman Group LLC. All rights reserved.
Original Post
Editor’s Note: The summary bullets for this article were chosen by Seeking Alpha editors.
Credit: Source link