
• bitcoinBitcoin(BTC)$83,917.00-0.38%
  • ethereumEthereum(ETH)$2,698.03-0.96%
  • tetherTether(USDT)$1.00-0.01%
  • binancecoinBNB(BNB)$769.700.57%
  • rippleXRP(XRP)$1.520.23%
  • usd-coinUSDC(USDC)$1.00-0.01%
  • solanaSolana(SOL)$119.71-0.07%
  • tronTRON(TRX)$0.3401821.43%
  • zcashZcash(ZEC)$1,430.00-0.49%
  • Figure HelocFigure Heloc(FIGR_HELOC)$1.030.00%
  • HyperliquidHyperliquid(HYPE)$86.78-2.19%
  • dogecoinDogecoin(DOGE)$0.0961910.65%
  • chainlinkChainlink(LINK)$14.42-6.18%
  • moneroMonero(XMR)$541.33-0.23%
  • USDSUSDS(USDS)$1.000.08%
  • whitebitWhiteBIT Coin(WBT)$83.93-0.27%
  • cardanoCardano(ADA)$0.248615-2.06%
  • RainRain(RAIN)$0.012430-0.41%
  • leo-tokenLEO Token(LEO)$9.06-0.08%
  • stellarStellar(XLM)$0.228322-3.15%
  • nearNEAR Protocol(NEAR)$5.298.77%
  • bitcoin-cashBitcoin Cash(BCH)$311.08-0.60%
  • uniswapUniswap(UNI)$8.88-2.88%
  • litecoinLitecoin(LTC)$67.68-1.93%
  • CantonCanton(CC)$0.125182-4.00%
  • avalanche-2Avalanche(AVAX)$11.16-4.82%
  • Ethena USDeEthena USDe(USDE)$1.00-0.02%
  • hedera-hashgraphHedera(HBAR)$0.108495-8.83%
  • suiSui(SUI)$1.16-2.13%
  • quant-networkQuant(QNT)$319.7427.81%
  • daiDai(DAI)$1.00-0.03%
  • USD1USD1(USD1)$1.00-0.03%
  • the-open-networkGram (prev. Toncoin)(GRAM)$1.50-5.46%
  • BittensorBittensor(TAO)$306.62-3.37%
  • shiba-inuShiba Inu(SHIB)$0.0000060.32%
  • tether-goldTether Gold(XAUT)$4,186.470.73%
  • crypto-com-chainCronos(CRO)$0.067049-6.84%
  • Global DollarGlobal Dollar(USDG)$1.000.00%
  • BitwayBitway(BTW)$1.17-11.25%
  • paypal-usdPayPal USD(PYUSD)$1.000.03%
  • Pump.funPump.fun(PUMP)$0.0057465.77%
  • EthenaEthena(ENA)$0.2542420.53%
  • okbOKB(OKB)$120.28-0.71%
  • Ripple USDRipple USD(RLUSD)$1.000.00%
  • aaveAave(AAVE)$160.94-6.46%
  • OndoOndo(ONDO)$0.51-3.17%
  • Circle USYCCircle USYC(USYC)$1.140.01%
  • MemeCoreMemeCore(M)$1.04-1.50%
  • mantleMantle(MNT)$0.693.37%
  • Ondo US Dollar YieldOndo US Dollar Yield(USDY)$1.15-0.08%
TradePoint.io
  • Main
  • AI & Technology
  • Stock Charts
  • Market & News
  • Business
  • Finance Tips
  • Trade Tube
  • Blog
  • Shop
No Result
View All Result
TradePoint.io
No Result
View All Result

The Eurozone’s Summer Tourist Boom Should Give Way To A Significant Slowdown

September 1, 2023
in Market & News
Reading Time: 4 mins read
A A
The Eurozone’s Summer Tourist Boom Should Give Way To A Significant Slowdown
ShareShareShareShareShare

Karl-Friedrich Hohl/iStock Unreleased via Getty Images

YOU MAY ALSO LIKE

This leg condition that’s overlooked in women can raise heart attack, stroke risk – The Washington Post

AMD: Expensive, But Growth Is Still Fast Enough To Keep The Bull Case Alive (NASDAQ:AMD)

By Peter Vanden Houte

Business sentiment in contraction territory

In spite of heatwaves and wildfires, the tourist season seems to have been strong in Europe. It has continued to support growth in the third quarter following a better-than-expected growth figure in the second quarter. However, with the end of the summer in sight, we’re now beginning to see a more sobering economic outlook emerge.

The composite PMI survey for August was certainly a cold shower, falling to the lowest level in 33 months at 47 points. While the figure has already been in contraction territory in industry for some time, it has now fallen below the boom-or-bust level in the services sector. Deteriorating order books weighed on confidence in both the manufacturing and the services sector, which also explains why there were job losses in manufacturing while hiring plans in the services sector were put on a slow burner. This will probably stop the decline in unemployment in the eurozone.

Disappointing external demand

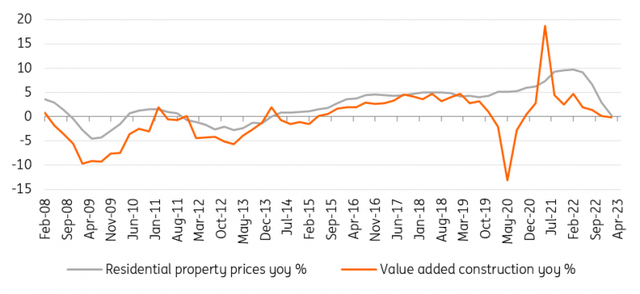
A softer labour market might lead to higher savings rates, thereby countering the positive impact on consumption of rising purchasing power. At the same time, the much-anticipated export boost is unlikely to materialise as the US economy eventually starts to cool while the Chinese recovery continues to disappoint. Finally, with a rapidly cooling housing market on the back of tighter monetary policy, the construction sector is also likely to see a slowdown. All of this explains why we still don’t buy the European Central Bank’s story that economic recovery will strengthen on the back of falling inflation, rising incomes and improving supply conditions. We expect the winter quarters to see close to 0% growth, resulting in 0.6% annual GDP growth for both this year and next year.

Cooling housing market is likely to weigh on construction activity

LSEG Datastream
LSEG Datastream

Inflation is coming down, slowly

While inflation is clearly trending down, the pace might still leave the ECB uncomfortable. Industrial goods prices have started to fall, but services prices are still growing monthly above 4% in annualised terms. Negotiated wage growth seems to have reached a plateau just below 4.5%. Still, given the slow productivity growth (with the decline in hours worked as one of the important drags), final demand will have to be very weak to prevent higher wages from feeding into higher prices.

We expect headline inflation to hit 2% by the end of 2024, but over the coming months, core inflation remains likely to hover around 5%. As the recent trend in underlying inflation is one of the key determinants of monetary policy, this would lead to an additional rate hike.

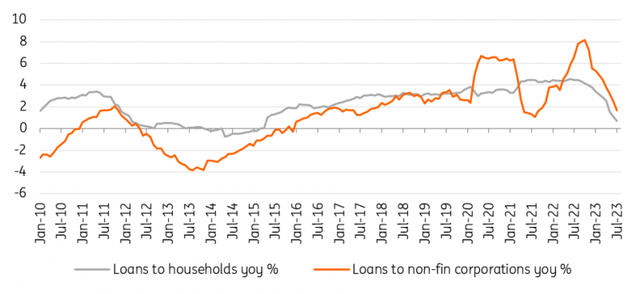
Loan growth is close to stalling

LSEG Datastream
LSEG Datastream

The ECB’s job is almost done

With credit growth now close to a standstill and money growth negative, there remains little doubt that monetary policy is already sufficiently restrictive and that the monetary transmission mechanism is working. On top of that, the median consumer inflation expectation for the period three years ahead fell back to 2.3% in June. So, it looks as though the job is nearly done. For now, we’re still pencilling in a final 25 basis point hike for the ECB’s September meeting – but it’s a very close call. A pause would likely mean the end of the tightening cycle, as the faltering recovery will make it harder to continue raising rates afterwards.

While we see the first rate cut by the summer of 2024, we can’t imagine the central bank loosening aggressively next year. In her speech at Jackson Hole, President Christine Lagarde mentioned a number of structural changes that make the medium-term inflation outlook more uncertain, and we think that the ECB will keep short rates relatively high for some time to come. That will probably limit the potential for the bond market to rally strongly in the wake of the expected economic stagnation later this year.

Content Disclaimer

This publication has been prepared by ING solely for information purposes irrespective of a particular user’s means, financial situation or investment objectives. The information does not constitute investment recommendation, and nor is it investment, legal or tax advice or an offer or solicitation to purchase or sell any financial instrument. Read more

Original Post

Credit: Source link

ShareTweetSendSharePin

Related Posts

This leg condition that’s overlooked in women can raise heart attack, stroke risk – The Washington Post
Market & News

This leg condition that’s overlooked in women can raise heart attack, stroke risk – The Washington Post

September 30, 2026
AMD: Expensive, But Growth Is Still Fast Enough To Keep The Bull Case Alive (NASDAQ:AMD)
Market & News

AMD: Expensive, But Growth Is Still Fast Enough To Keep The Bull Case Alive (NASDAQ:AMD)

September 30, 2026
SkiStar AB (publ) 2026 Q4 – Results – Earnings Call Presentation (OTCMKTS:SSKRF) 2026-09-30
Market & News

SkiStar AB (publ) 2026 Q4 – Results – Earnings Call Presentation (OTCMKTS:SSKRF) 2026-09-30

September 30, 2026
‘Violent incident’ between pilots sparks diversion of Israel-bound flight to Saudi Arabia, sources say – CNN
Market & News

‘Violent incident’ between pilots sparks diversion of Israel-bound flight to Saudi Arabia, sources say – CNN

September 30, 2026
Next Post
Complexity of Online Business Stifles Tech Growth, Says Stripe Co-Founder

Complexity of Online Business Stifles Tech Growth, Says Stripe Co-Founder

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

Search

No Result
View All Result
Invesco Senior Floating Rate Fund Q2 2026 Commentary (OOSAX)

Invesco Senior Floating Rate Fund Q2 2026 Commentary (OOSAX)

September 24, 2026
Sell The House To Pay For His Son’s College

Sell The House To Pay For His Son’s College

September 29, 2026
Don’t Wait For Cheaper Stocks — Rebecca Walser On Stocks To Buy Now

Don’t Wait For Cheaper Stocks — Rebecca Walser On Stocks To Buy Now

September 24, 2026

About

Learn more

Our Services

Legal

Privacy Policy

Terms of Use

Bloggers

Learn more

Article Links

Contact

Advertise

Ask us anything

©2020- TradePoint.io - All rights reserved!

Tradepoint.io, being just a publishing and technology platform, is not a registered broker-dealer or investment adviser. So we do not provide investment advice. Rather, brokerage services are provided to clients of Tradepoint.io by independent SEC-registered broker-dealers and members of FINRA/SIPC. Every form of investing carries some risk and past performance is not a guarantee of future results. “Tradepoint.io“, “Instant Investing” and “My Trading Tools” are registered trademarks of Apperbuild, LLC.

This website is operated by Apperbuild, LLC. We have no link to any brokerage firm and we do not provide investment advice. Every information and resource we provide is solely for the education of our readers. © 2020 Apperbuild, LLC. All rights reserved.

No Result
View All Result
  • Main
  • AI & Technology
  • Stock Charts
  • Market & News
  • Business
  • Finance Tips
  • Trade Tube
  • Blog
  • Shop

© 2023 - TradePoint.io - All Rights Reserved!