OntheRunPhoto/iStock Editorial via Getty Images
The Cheesecake Factory Incorporated (NASDAQ:CAKE) is going to report the company’s Q2 results on the 31st of July, where analysts expect a sequential improvement from Q1 in growth.
After my previous article on the stock, published on the 3rd of April with the title “Why Cheesecake Factory’s Growth Hasn’t Translated Into Stock Appreciation”, CAKE has reported solid Q1 results amid a challenging industry backdrop. The stock has had a total return of 9% compared to S&P 500’s return of 8% in the same period after my article was published with the Hold rating.
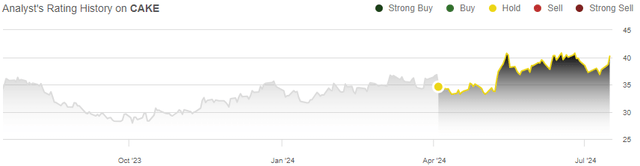
My Rating History on CAKE (Seeking Alpha)
Cheesecake Factory Q2 Earnings Preview: A Mixed, Cautiously Optimistic Outlook
CAKE is going to report the company’s Q2 results on the 31st of July in post-market hours. Wall Street analysts are estimating revenues to grow by 5.0% year-over-year into $909.4 million, and for the normalized EPS to grow by eleven cents into $0.99. The stock has had some traction from Wall Street, as in late May Wedbush added the stock into a “Best ideas list”, outlining CAKE’s recently good performance. Wedbush anticipates CAKE’s comparable restaurant growth to be 1.5% in Q2, whereas the Wall Street consensus stands lower at 1.0%.
Wall Street seems to expect quite good industry trends in Q2. The company communicated in the Q1 earnings call to expect revenues of $890-910 million in Q2 with the assumption of February and March trends continuing, with Wall Street estimating the upper part of the range. It seems that the estimates follow stronger trends that the industry saw during the earlier months in Q2 – for example, Shake Shack (SHAK) and Red Robin (RRGB) have noted a traffic pick-up in April and May (sources: Shake Shack, Red Robin).
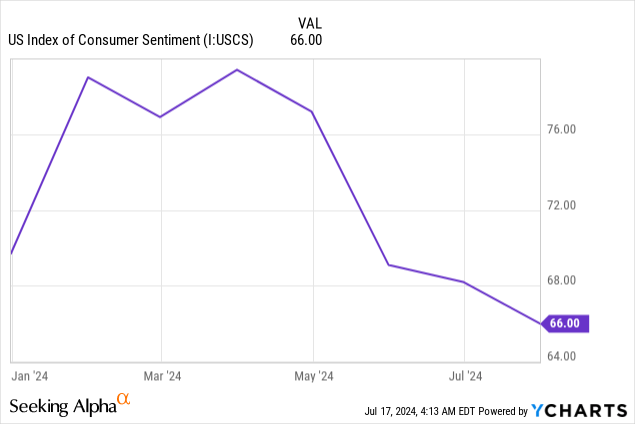
The quarter is still going to be reported against a challenging industry backdrop as customer spending remains more restricted – I believe that investors shouldn’t yet assume a very good result, as the more positive industry remarks in April and May seem to have turned into a more cautious tone recently. CAKE should see a sequential improvement with good trends continuing from February forward into a good part of Q2, but especially then June outlook seems cloudy, which investors should beware of. The consumer sentiment trend has been especially poor in June.
Q1 Results Showed a Solid Performance in Challenging Industry Backdrop
The Q2 earnings release is coming after CAKE reported fairly good Q1 results – while the results weren’t great, they compared to a challenging industry. Revenues grew by 2.9% in the quarter, led by a -0.6% decline in comparable restaurant sales that CAKE’s CEO David Overton communicated to have outperformed the industry. CAKE’s comparable sales growth of -0.6% in Q1 compares to Bloomin’ Brands’ (BLMN) -1.6%, Brinker International’s (EAT) +3.3%, and Denny’s Corporation’s (DENN) -1.3%, for example, beating two of the three larger chains supporting the notation of a strong performance in the industry.
While the revenues were roughly in line with Wall Street analysts’ expectations, the normalized EPS of $0.73 beat estimates by $0.09, as CAKE’s gross margin saw a healthy 1.0 percentage point leverage from the level a year ago. I believe that the cost control represented in Q1 provides a good foundation for the expected Q2 profitability improvement, although ultimately, comparable restaurant sales growth drives the profitability level.
I believe that the Q1 results provide a good backdrop for Q2 in terms of the performance against the industry. On the other hand, very good improvements are expected sequentially – Wall Street’s Q2 estimates anticipate a sequential jump from the -0.6% Q1 comparable sales growth into a positive 1.0% in Q2. While the industry outlook seems to have been better during the early quarter with gradual improvements from February forward, the industry backdrop still highlights the potential for a negative surprise in the quarter due to likely worse June trends.
CAKE Stock Updated Valuation
While no major updates are needed, I slightly adjusted my discounted cash flow [DCF] model assumptions. I estimate similar revenues as before, but due to CAKE’s good margin improvement in Q1, I estimate the EBIT margin 0.1 percentage points higher going forward at 4.7% in 2024 and at 5.1% afterwards. The company’s growth investments look to again worsen cash flows moderately in the coming years.
For more thorough explanations of the assumptions, I refer to my previous article on the company.
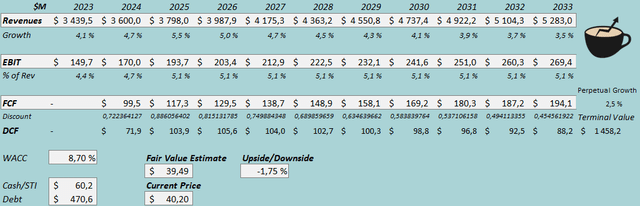
DCF Model (Author’s Calculation)
The estimates put CAKE’s fair value estimate at $39.49, very near the stock price at the time of writing – going into the earnings, I believe that CAKE’s risk-to-reward is very balanced especially in the long term. The fair value estimate is up from $31.88 previously, predominantly due to a lower used cost of capital.
CAPM
A weighted average cost of capital of 8.70% is used in the DCF model. The used WACC is derived from a capital asset pricing model:
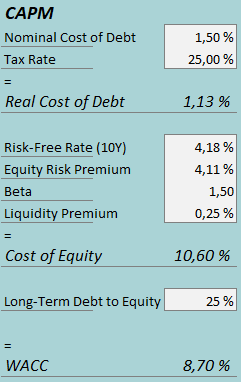
CAPM (Author’s Calculation)
In Q1, CAKE had $1.8 million in interest expenses, making the company’s interest rate 1.50% with the current amount of interest-bearing debt. I continue estimating a long-term debt-to-equity ratio of 25%. To estimate the cost of equity, I use the 10-year bond yield of 4.18% as the risk-free rate. The equity risk premium of 4.11% is Professor Aswath Damodaran’s estimate for the US, updated in July. I have kept the beta estimate at 1.50. With a liquidity premium of 0.25%, the cost of equity stands at 10.60% and the WACC at 8.70%.
Takeaway
CAKE is going to report Q2 results in late July. Wall Street estimates a great sequential improvement as the industry seems to have been healthier during April and May, but I believe that there is still potential for a negative surprise as well – a very good sequential comparable sales jump is expected with a cloudy industry outlook, especially in June. The profitability is also expected to improve well, being a reasonable assumption with CAKE’s good recent cost management and the anticipated comparable sales growth. With a very balanced stock valuation, and a mixed Q2 outlook, I remain at a Hold rating for The Cheesecake Factory.
Editor’s Note: This article covers one or more microcap stocks. Please be aware of the risks associated with these stocks.
Credit: Source link