
PM Images
Summary
I am recommending a hold rating for The Brink’s Company (NYSE:BCO), as the current share price is not attractive. BCO provides cash and value management (core business), ATM managed services [AMS], and digital retail solutions [DRS]. The core business includes the secure transportation of currency, precious metals, and securities for financial institutions and governments, and ATM services include cash replenishment, transaction processing, and the and the installation and maintenance of bank-owned ATM networks.
DRS essentially leverages technology platforms to make cash available to customers in a faster manner (including helping in the collection, management, settlement, and reconciliation of digital payments). The nature of BCO services also meant long-term recurring revenues, as core services often have multi-year contracts establishing service levels and pricing.
Comments
Scale matters a lot in this industry, and I believe BCO’s market share leadership confers significant competitive advantages and scale economies. For market share information, BCO is the market leader of cash management services globally and will be worth ~$20.53 billion in 2023 with around 20+% market share, followed by the 2nd player, Loomis, and Prosegur Cash, who both have around low-teens percentage market share.
Scale is important because it provides strong route density that increases collection efficiency (per route), improves service turnaround times (easier to revisit the same point of collection if it is near the next or previous job), increases fuel efficiency (fuel cost per service drops), and enables better servicing of national accounts. The last point in servicing national accounts and large enterprises is an important point to note because subscale competitors cannot compete against large players like BCO. National accounts typically have a presence across the nation, and they naturally want to just deal with one single vendor as it reduces security risk (cash transfers across multiple hands tend to have more points of failure) and also makes accounting easier since reporting and related stuff can be consolidated before sending to BCO.
From the point of view of the service provider, without route density across the region of focus, it would not be economically viable to service all of the nation’s accounts (e.g., player A only focuses on region A, but the client requires service for regions B, C, and D where player A does not have any routes). BCO brand and history represent additional competitive advantages in an industry that places a premium on risk management, in my opinion, noting that BCO has been in the CIT business for more than a hundred years.
The bear thesis revolving around BCO is that the world is moving toward cashless payments, and as such, cash collection services might not be as important anymore. While I agree with the broader trends, I think there are sufficient growth opportunities for BCO to continue growing healthily (at least in line with consensus growth) forward because of:
- Plenty of market share left to capture: BCO is the largest player, and if the broader secular headwind were to impact the industry, subscale players would tap out first, giving up market share for BCO to capture.
- Developing countries are still seeing a 20-30% mix of transactions in cash, which means there is still a large market of accounts to service for BCO. I would further note that management commented that their AMS still sees a “growing pipeline” of opportunities in 2024.
- While cash transactions will go away, cash will not go away, which means ATMs must continue to exist if consumers have no way to withdraw cash when needed. This becomes a “liability” for banks because they need to spend resources to manage these machines. For BCO, this is music to its ears because it has the right solutions and route density to solve this problem. I could argue that the decreasing usage of cash actually benefits BCO from this point of view.
BCO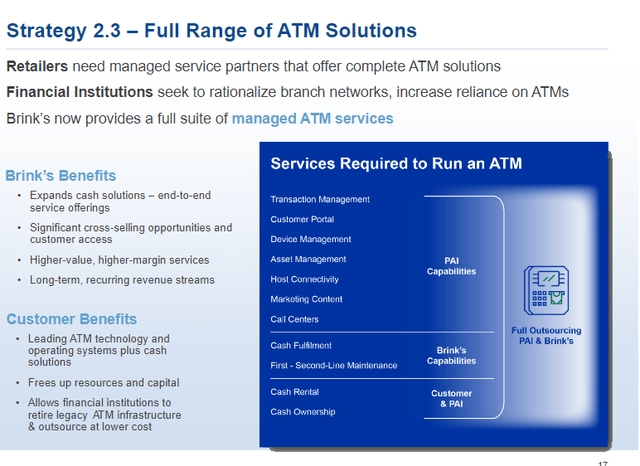
It is very apparent from 4Q23 results that BCO is not facing strong headwinds given that DRS and AMS revenue grew 17% organically on a combined basis in 4Q23 which is of similar magnitude as 3Q23 (18% growth). These business segments have also grown to represent 21% of BCO revenue mix, further diversifying BCO away from its previous core business.
I believe that DRS’s growth momentum will persist, as the company is currently experiencing a robust start to 2024 with installations in North America and an impressive traction in Europe with new customer onboarding. The sales pipeline is also up 50% year-over-year across all regions.
As BCO scales up, I would expect margins to expand since there are a lot of fixed costs in the business. Management guidance is for 80 bps of EBITDA margin expansion at the midpoint in 2024, driven by productivity enhancements, operating leverage, and a greater mix of high-margin DRS and AMS solutions. This should flow through nicely to more FCF generation to support capital returns-both dividends and share repurchases.
As per consensus estimates, we are looking at a potential $1 DPS in FY24 ($44.7 million cash required), which combined with a share buyback of 2.2% ($85 million cash required) in FY24 (based on the past 5 years share repurchase trend-a 11% reduction between FY18 and FY23), I am expecting a capital return yield of ~3.3%. To facilitate this, BCO needs ~$130 million of cash, which can be easily provided by existing FCF generation. As for the remaining FCF, I expect it to be allocated to M&A (BCO acquired 8 targets over the past 5 years) to scale the business up.
Valuation
Based on author’s own math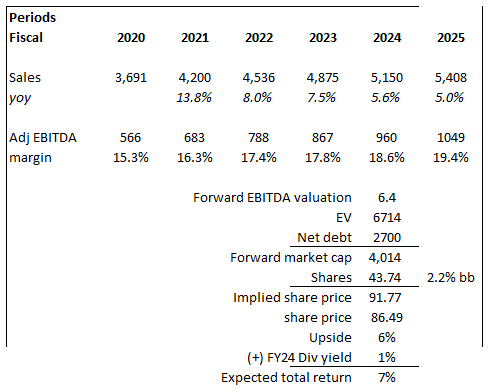
Based on my view of the business, BCO should be able to grow at mid-single digits (5.6/5% for FY24/25) with no issues given the various growth drivers that I have noted in my comments section above. For note, 5.6% is in line with management guidance, and I extrapolated the mid-single-digit trend into FY25. I assumed EBITDA margins would expand by 80 basis points following the guide and by the same magnitude in FY25 as I expected similar growth rates.
Given the relatively slower growth expectation vs. FY21/22/23, I think it’s hard to justify a higher multiple in the near term (despite the high margin profile); hence, I assumed the current multiple valuation would stay. After including share buybacks and a 1% dividend yield, I derived an expected total return of 7%, which is not compelling. Therefore, I recommend a neutral rating, putting this on the watchlist until the share price gets cheaper.
Risk
Inflation in Argentina could cause a big swing in EBITDA, as BCO might not be able to match the cost increase as quickly as it would like, given that pricing growth typically lags input cost growth. Regarding growth headwinds, BCO is currently shedding contracts in North America that have unfavorable pricing economics, which is going to have a negative impact on volumes and revenue in FY24.
Conclusion
I am recommending a hold rating. While BCO boasts a strong market share and growth potential in its core business and emerging digital solutions, current share price is not an attractive entry point. Headwinds like inflation and shedding of contracts could cause near-term revenue growth to be volatile – which could cause some pressure on the share price (providing a better entry point).
Credit: Source link