
HeliRy
Note:
I have covered Teekay Corporation (NYSE:TK) previously, so investors should view this as an update to my earlier articles on the company.
Shares of Teekay Corporation are up by 30% since my last update on the company three months ago due to the strong recent performance of its main consolidated subsidiary Teekay Tankers Ltd. (TNK).
Yahoo Finance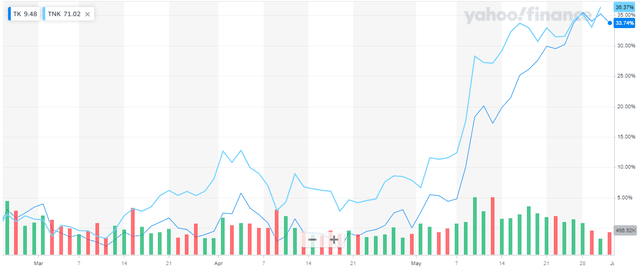
Teekay Tankers reported decent Q1/2024 results and rewarded shareholders with a special cash dividend of $2 per share after the company’s net cash position increased to approximately $370 million:
Teekay Tankers Press Release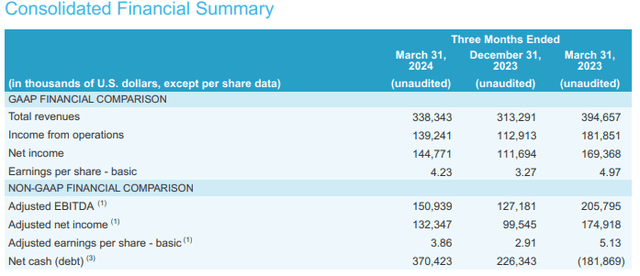
In combination with Teekay Tankers’ $0.25 regular quarterly cash dividend, parent Teekay Corporation will pocket approximately $22 million in dividends in the current quarter, which should lift the company’s cash position well above $300 million by the end of Q2.
Not surprisingly, Teekay Corporation’s shares have appreciated in value alongside Teekay Tankers and even narrowed the discount to net asset value (“NAV”) to the lower end of its long-standing 10% to 20% range:
Company Press Releases / Regulatory Filings / Yahoo Finance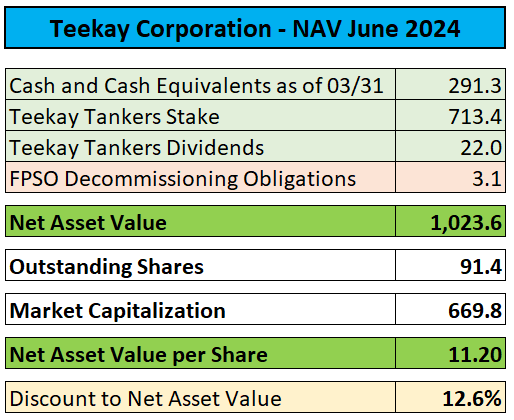
Given ongoing uncertainties regarding Teekay Corporation’s future capital allocation decisions and considering the unnecessary and costly dual listing structure, a discount to net asset value appears warranted.
With approximately 93% of Teekay Corporation’s revenues derived from the consolidation of Teekay Tankers, the company’s small marine services operations should be considered immaterial:
Company Press Release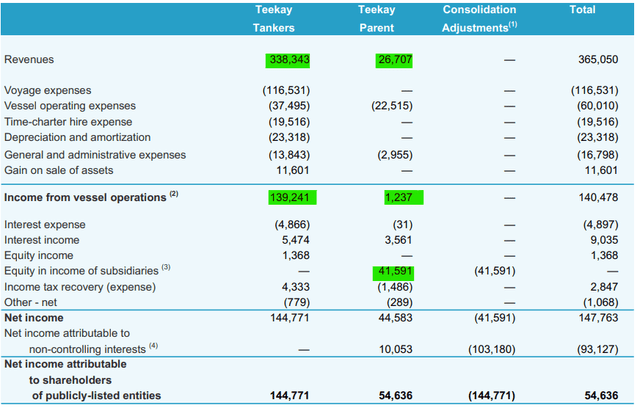
As of the end of Q1, Teekay Corporation owned 5,168,785 Class A common shares and 4,625,997 Class B common shares of Teekay Tankers, representing a 28.8% economic interest and the majority of voting power.
Over the past two years, Teekay Corporation has repurchased more than 10% of outstanding shares. However, the increase in the company’s stock price has resulted in immaterial buyback activity during Q1.
At least in my opinion, Teekay Corporation should divest its marine service operations, distribute virtually all of its cash to common shareholders and ultimately merge into Teekay Tankers but, admittedly, there’s very little incentive for Teekay Corporation’s management to eliminate their well-paid jobs.
With Teekay Corporation’s shares now trading at the lower end of the long-standing discount range, I wouldn’t chase the shares aggressively at current levels and rather wait for a pullback similar to the drop experienced in February after investors punished Teekay Tankers for weaker-than-expected Q4 results and management’s refusal to increase shareholder capital returns.
However, with the outlook for the tanker market still strong, the stock remains a solid “Hold” position.
Teekay Tankers Presentation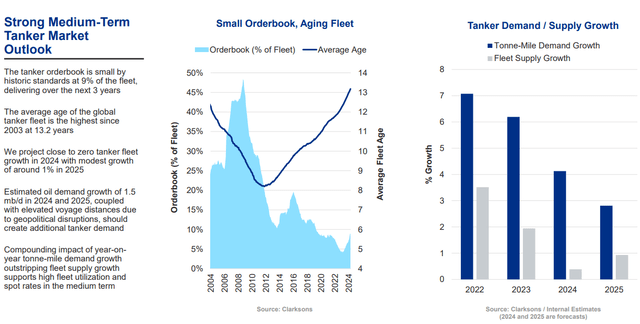
Bottom Line
Teekay Corporation’s stock price has appreciated by approximately 30% in recent months thanks to renewed strength in shares of subsidiary Teekay Tankers. As a result, Teekay Corporation’s discount to net asset value has narrowed to the lower end of its long-standing 10% to 20% trading range.
While I wouldn’t chase the shares aggressively at current levels, the strong outlook for the tanker market makes the stock a solid “Hold” position.
Credit: Source link