urbancow
Tanger Inc. (NYSE:SKT), incorporated in 1981 and headquartered in Greensboro, NC, develops, acquires, owns, leases, manages, and operates outlet and open-air centers across the country.
This REIT enjoys the same positive market dynamics as most retail REITs, but due to its lease structure, attractive performance, dividend growth, and valuation, I think that it stands out. In this article, I will go into more detail about all of those points to help you understand my bullish thesis.
Portfolio and Outlook
The REIT’s portfolio consists of 40 properties that aggregate 15.6M square feet and are spread across 18 states.
Investor Presentation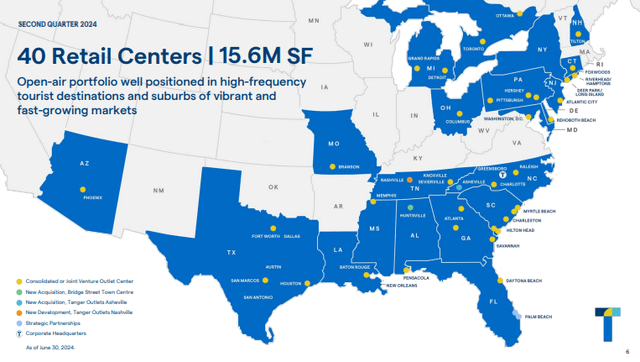
As of December 31, 2023, 13% of the portfolio was concentrated in South Carolina, the highest state exposure based on square feet, with New York coming second at 12%. I think this is important to reflect on as many REITs launch operations in more and more markets in an attempt to expand their operations and geographically diversify at the same time, but more often than not you don’t see a lot of progress regarding limiting their exposure to one or two states. Tanger, a 43-year-old REIT, has had the time and fortitude to efficiently diversify their operations and this is probably attractive to shareholders who want broad retail real estate exposure and very limited concentration risk through one REIT to keep their portfolios simplified. But I digress.
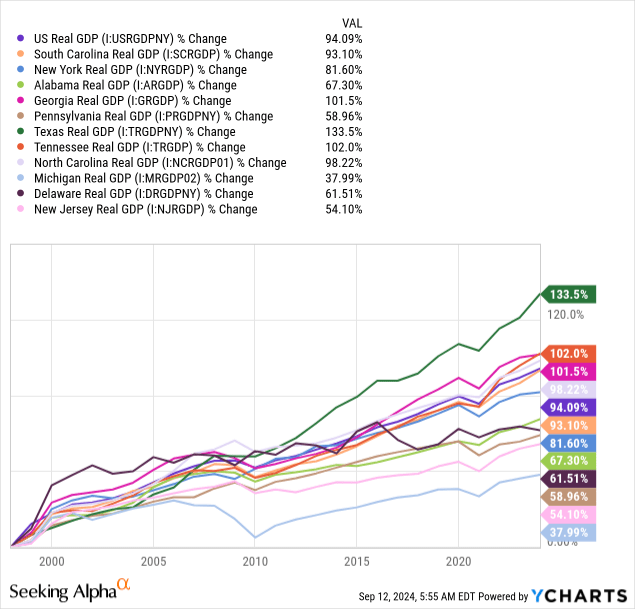
I would say that based on real GDP growth, the portfolio’s markets score about average, with some of its most important markets below the U.S. average over the long term and others above it.
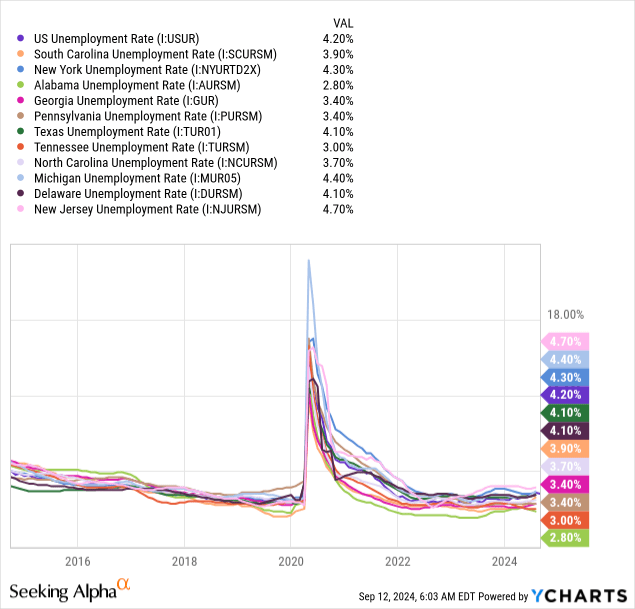
That being said, the portfolio is very well positioned based on employment level with most of the top states having below-average unemployment rates:
Regarding its tenants, Tanger has done an equally good job in diversification as its top tenant by ABR, The Gap, accounted for only 5.7% of ABR as of June 30, 2024.
Now, because of the short-term nature of its leases, about half of the REIT’s leases expire in the next 3 years. Past leasing spreads have been strong (12% for renewals and 37% for new leases in 2023), fueled by favorable market dynamics that still persist today, offering a good opportunity for significant short-term internal growth.
Demand is strong as shopping centers aren’t threatened by e-commerce to the same degree that other single-tenant retail properties are, so the lack of alternatives keeps tenants renewing their leases, often at higher rents. Also, the low supply level, as represented by improved net absorption levels since 2020 and record-low construction starts, doesn’t indicate increased competition:
JLL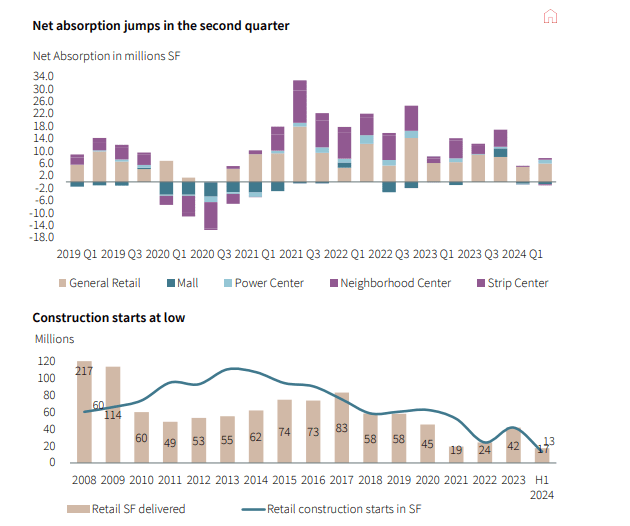
Performance
Recent operational results reflect the presence of such attractive market conditions as well as Tanger’s ability to take advantage of them. In 2023, blended leasing spreads of 13.3%, consisting of 37.5% spreads for new tenants and 11.2% for renewals, reflect a 320 bps YoY increase. Additionally, base rent increased by 3.25% and occupancy increased by 30 bps to 97.3%. With 6.2% YoY growth in same-center NOI and core FFO reaching $1.96 per share, reflecting a YoY 7.1% increase, the impact on the bottom line was significant.
In the last quarter, the company reported that the average leasing spread based on the TTM leasing activity was 15%, indicating accelerated internal growth. Occupancy was lower in the second quarter at 97.1% when compared to the year-end 2023 but by only 20 bps. Regardless, same-center NOI increased by 8% and FFO per share increased by 12.77% to $0.53 per share, also reflecting accelerated growth.
During the last earnings call, management guided higher and now expects same-center NOI to grow by 3.25% to 4.75% in 2024. Core FFO per share is now expected to increase by about 5% to 8% based on a new range of $2.05 to $2.12.
Leverage & Liquidity
As of the second quarter of 2024, Tanger’s $1.4 billion of debt financed 63.66% of its total assets. While that may be above-average leverage among retail REITs, 95.8% of that debt was unsecured and 94% was fixed-rate. Moreover, the REIT enjoys very strong liquidity as its debt/adjusted EBITDAre ratio is at 4.57x and interest coverage is 5.09x (average interest rate of 4.10%). Also, there are no maturities in 2025 and the rest are manageable given the high level of available liquidity.
Investor Presentation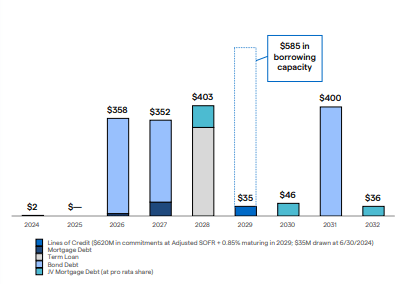
Dividend & Valuation
SKT currently pays a quarterly dividend of $0.28 per share, resulting in a forward yield of 3.57%. While I think that this yield is very low in the current environment, there is a lot to like about SKT. First, the payout ratio is also very low at 54.63%; this leaves plenty of room for dividend growth, which is reasonable to expect given the rapid growth of this REIT’s core FFO. Of course, expectations of increased FFO per share answer the “can it” question. The “will it” can be answered by the average 4.35% dividend growth rate in the last 3 years; even though Tanger cut the dividend in 2020 like many other retail REITs, it’s on its way to bringing it back to its pre-pandemic level.
Seeking Alpha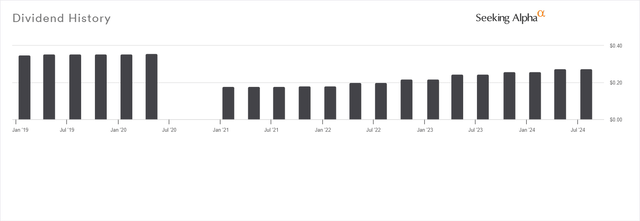
Moreover, its FFO yield of 6.55% represents good value here. On a peer-relative basis, it seems to be fairly valued as its FFO multiple is 14.77x while the average of its peers is 14.84x. However, I think its multiple should be judged in the context that its positive outlook provides. While many retail REITs should enjoy high growth given the current market dynamics, we’ve already seen that Tanger’s relatively short-term leases and efficient management give it an advantage for better growth prospects.
Its implied cap rate is currently 6.36%, which is lower than the rate of 6.9% which is forecast to be the average for retail asset transactions in 2024. Using the latter, NAV comes at $27.70 per share, so the current price represents a 12.87% premium to NAV. While I generally like buying REITs at prices below their NAVs, I believe that this one deserves to be trading at least 20% above its NAV for the efficient management of the assets to take maximum advantage of the currently favorable supply/demand condition; without it, it wouldn’t be worth very much anyway.
Risks
While I believe that the company will continue to provide value to shareholders without major issues, this nuanced approach to valuation poses the risk of a lack of margin of safety. I believe there is a margin of safety here given the solvency profile and growth opportunities, but it is not as tangible as a discount to NAV often reflects. Make sure you understand that as you consider the merits of this REIT.
Additionally, REITs are sensitive to interest rate changes, and many have experienced price declines in the last couple of years. However, it appears that SKT is more resistant, as it has increased by 81% since the Fed started raising the policy interest rate in 2022. Regardless, some of those gains could be the result of expectations of lower interest rates in the short term, so increased volatility is likely if the Fed delays the cuts.
TrendSpider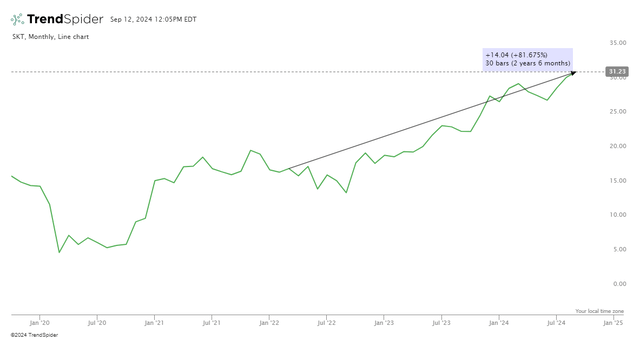
Verdict
Despite the risks, I think that SKT is a good pick due to the high dividend growth prospect, efficient management, and attractive valuation. So, I am rating it a buy.
What do you think? Do you own this stock, or do you favor some other REIT? I’d love to know! Also, please leave a comment if you found this post useful; it means a lot.
Credit: Source link