
hapabapa
Introduction & Investment Thesis
ServiceNow (NYSE:NOW) provides an end-to-end workflow automation platform for enterprises. The stock has performed more or less at par with the S&P 500 and Nasdaq 100 YTD. The company reported its Q4 FY23 earnings in January, where it beat on both revenue and earnings expectations, growing 26% YoY and 33.8% YoY, respectively. It is expected to report its Q1 FY24 earnings on April 24, where it expects to grow its Subscription revenue by 23.5-24% to $2.5B while improving its non-GAAP operating margin by 300 basis points YoY to 29%.
ServiceNow has a history of delivering operational excellence and robust product innovation, and I will be watching to see how it drives its momentum with new logo acquisition while growing spend on the platform among its existing customer cohorts at the same time, as it remains laser focused on building new features to integrate GenAI on its platform and across workflows with its latest Washington DC platform release to drive higher productivity, cost savings, and improved experiences for their customers.
However, I believe that the management’s forward guidance is fully priced into the stock at the moment, thus leaving little to no upside from its current levels. Therefore, I will rate it as a “hold” at the moment, as it heads into its earnings.
A preview of ServiceNow’s Q4 Earnings Report
ServiceNow reported its Q4 FY23 earnings report in January, where it outperformed on both the revenue and earnings estimates for the quarter. For the full year FY23, the company generated $8.9B in revenue, growing 23.5% YoY. Out of the $8.9B in revenue, Subscription Revenue contributed 97% to Total Revenue, growing 25.5% YoY. At the end of FY23, ServiceNow had 1897 customers with $1M+ in Annual Contract Value (ACV) growing 15% YoY, while the average ACV of the $1M+ customer cohort grew 10% YoY to $4.5M. To me, this indicates deepening adoption and spend on the platform per customer, as ServiceNow continues to successfully drive its product strategy to benefit from the growing spend in AI while gaining operating leverage at the same time.
Q4 FY23 Earnings Slides: Growing number of $1M+ ACV Customers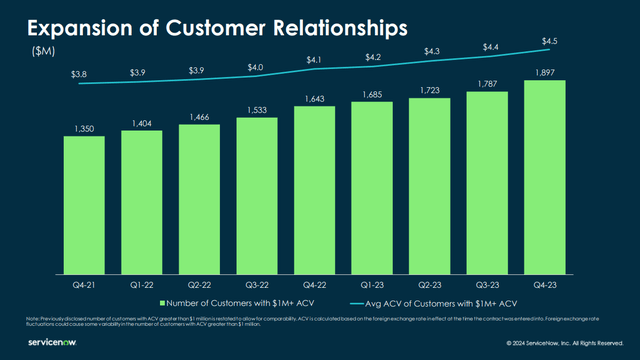
In terms of customer acquisition, the company saw tremendous traction, closing 168 deals across its product lines with over $1M in Net New ACV, up 33% YoY, and 10 new customers, including a $10M deal with a large global financial services firm, their largest customer logo in history.
Moving on to product innovation, I will first provide a quick overview of their solution suite. ServiceNow’s cloud-based workflow applications are built on the Now Platform, and the applications are organized into four areas that include 1) Technology, 2) Customer, 3) Industry and 4) Employee, so that organizations can unify workflows across siloed functions and systems to improve productivity, streamline operational processes, and improve the overall experience.
10k: ServiceNow’s Now Platform 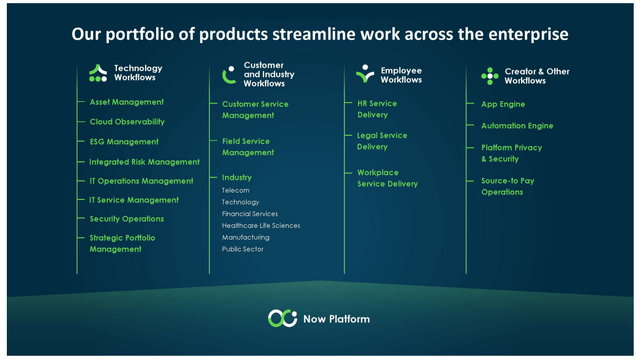
During the earnings call, Bill McDermott, CEO of ServiceNow, mentioned that 11 product lines have $250M in ACV, with IT Service Management (ITSM), IT Operations Management (ITOM) product lines within the Technology Workflow with doubt-digit deals of over $1M in ACV in Q4. Meanwhile, customer, employee, and creative workflow portfolios also had double-digit deals over $1M in ACV in Q4.
Q4 FY23 Earnings Slides: ACV across ServiceNow’s workflows on the platform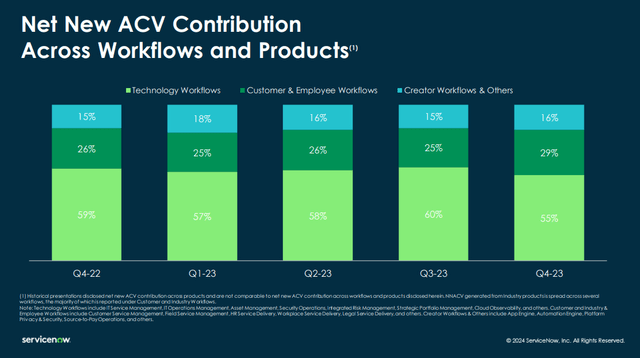
The company delivered its Vancouver release on September 20, where it integrated GenAI capabilities into its platform and across workflows in order to enable the IT department to streamline incident identification while offering businesses a holistic view into their risk parameters to improve agility. At the same time, it also released capabilities in order to automate manual processes so that employees can focus on ROI-rich activities and drive more informed career conversations between their managers to improve overall productivity and experience within an organization. During the earnings call, the CEO mentioned that they were seeing “exciting traction and customer adoption” as the company positioned itself to successfully commercialize its innovative solution suite in order to benefit from the secular trend in AI, where spending is expected to reach $3T by 2027, as per Gartner.
In order to spearhead growth, the company is also expanding its partner program with the announcement of its five-year strategic alliance with Visa (NYSE:V), where the two companies will work together to launch ServiceNow Disputes Management, a GenAI-powered solution that will offer dispute resolution for customers worldwide, as it expects to surpass $10B in revenue by the next fiscal year.
Shifting gears to profitability, ServiceNow generated close to $2.5B in non-GAAP operating income in FY23, up 33.8% YoY at a margin of 28%, up from 26% in FY22. The improvement in margin was driven by streamlining operating expenses, where Sales and Marketing spend relative to Revenue was 37%, compared to 39% in FY22 on a GAAP basis, while the growing number of customers with a spend of $1M in ACV and a renewal rate of 99% helped the company improve its overall operating leverage.
Q4 FY23 Earnings Slides: ServiceNow’s operating margins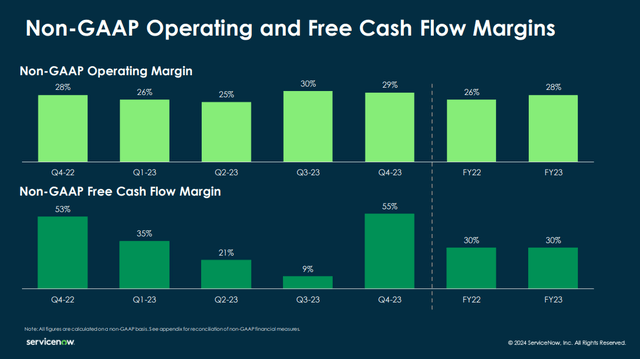
Key Updates since the last earnings call
During the last three months since the earnings call, ServiceNow has been very busy with plenty of initiatives on both the product innovation and acquisition fronts. I will highlight some of the main ones below.
-
ServiceNow and NVIDIA (NASDAQ:NVDA) introduced telecommunications-specific GenAI solutions with its Now Assist for Telecommunications Service Management that will leverage Nvidia AI to boost customer care agent productivity, improve speed to resolution, and elevate the overall customer experience. I believe the joint partnership puts ServiceNow at the forefront of the global telecommunications industry as they turn to AI to drive cost savings and unlock new business opportunities.
-
This ties in well with ServiceNow’s acquisition of Atrinet’s NetACE technology to drive end-to-end network lifecycle management for telecommunications companies on a single platform, given the strength of Atrinet’s NetACE network discovery and activation capabilities, thus accelerating ServiceNow’s roadmap to expand into telcos.
-
Finally, ServiceNow announced its first platform release with the launch of Washington, D.C., which includes features to enhance its Now Assist GenAI experiences, with the introduction of Now Assist for ITOM AIOps and Now Assist in Virtual Agent enhancements that will enable organizations to accelerate value from their AI spend. While Now Assist for ITOM AI Ops is designed to speed up issue resolution for IT operators, Now Assist in Virtual Agent is building capabilities with Virtual Agent Designer and Dynamic Translation features to improve self-service experiences by creating AI-powered conversations with real-time localization.
3 things to look for in ServiceNow’s Q1 earnings call
-
Revenue guidance: ServiceNow has guided its Subscription Revenue to grow 23.5%-24% YoY to $2B in Q1 FY24, while for the full year FY24, it is expected to grow 22% to approximately $10.56B. While it has a solid history of consistently meeting and exceeding its quarterly revenue projections, I believe that we need to pay closer attention to its forward guidance as to whether it will hold or raise its FY24 projection, given the momentum in its new logo acquisition and spend on its platform.
-
Current Remaining Performance Obligation (cRPO): The company has already set expectations that it will see a slowdown in cRPO in Q1 at 20%, compared to 24% in Q4 FY23. I believe any decline in this figure would indicate weakening in customer renewal rate and spend on platform, which will weigh down on investor expectations.
-
Net new ACV: So far, ServiceNow has been on a tear with closing deals at a record pace with $1M in ACV, and should we see the momentum continue, the company may raise its projections for Q2, as well as for the full year FY24. One of the big drivers behind the success so far can be attributed to the robust production innovation geared towards integrating GenAI on the platform across its workflows, which is driving new logo acquisition. However, I believe that with macroeconomic uncertainties still persisting, we should be watching out for any commentary on the macroeconomic front, which can lead to a shift in sentiment.
-
Number of customers with $1M+ in ACV: I believe we need to see steady growth in this figure, with the average spend of $4.5M in ACV trending higher, in order to establish that customers are continuing to deepen adoption of the Now Platform across their workflows as they unlock productivity gains and improve cost savings. Should the growth in this number stall, we will see a hit to RPO eventually, while investor optimism will fade with disappearing momentum and margin.
2. Profitability guidance: For Q1 FY24, ServiceNow has guided a 29% margin from non-GAAP operating income. Assuming that revenue growth trends in line with Subscription growth at 24%, we should expect to see ServiceNow deliver a non-GAAP operating income of $620M, a growth of 42% YoY. This would also mean an improvement of 400 basis points in non-GAAP operating margin YoY. For the full year FY24, the company expects to maintain its non-GAAP operating margin at 29%.
3. AI: The CEO has been bullish on how ServiceNow can continue to commercialize its solutions as AI spend grows to $3T by 2027. It has already demonstrated robust product innovation through the accelerated launch of the Washington, D.C., platform release, and it is expected to follow it up with the Xanadu platform release by Q4 FY24. I expect the management to provide color into its product releases and how that is driving ACV across its workflows in the earnings call.
Is NOW stock a buy?
Taking ServiceNow’s FY24 projections for revenue and earnings into consideration, while expecting revenue growth to remain in the low twenties to high teens region over the next 2 years, as the company continues to drive robust innovation to capture market share while deepening adoption of its platform, I believe that ServiceNow should produce approximately $15.7B in revenue in FY26. At the same time, I believe that as ACV per customer continues to grow, ServiceNow will streamline its operating expenses, which will drive further margin improvement to at least 30% by FY26, which would translate to a non-GAAP operating income of $4.7B, equivalent to a present value of $3.9B, when discounted at 10%.
Taking the S&P 500 as a proxy, where its companies grow their earnings on average by 8% over a 10-year period with a price-to-earnings ratio of 15–18, I believe that ServiceNow should trade at a forward multiple of 2.25x of the S&P 500, or a PE ratio of 38, given its rate of earnings growth. This would translate to a price target of $719, which leaves no upside from its current levels, indicating that the stock has fully priced in the management’s forward guidance. Therefore, unless the company reports a substantial beat and raises FY24 guidance, I don’t expect the stock to have substantial upside from its current levels.
Author’s Valuation Model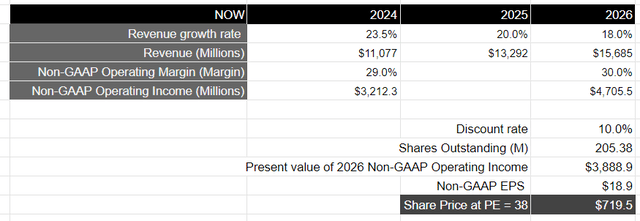
Conclusion
ServiceNow has a history of operational excellence and robust innovation. While the company had a terrific FY23, as it saw a record number of new deals with $1M in ACV and continued adoption of its platform while driving success through its product launches and partnerships, I believe that it is imperative that it continues its momentum in FY24 in order to keep investor optimism anchored. As per my analysis, I believe that the stock is fully priced in management’s forward guidance, and unless we see a substantial beat and raise, I maintain that the stock has little upside at its current levels, making it a “hold”.
Credit: Source link