Davel5957/E+ via Getty Images
Introduction
RLJ Lodging Trust (NYSE:RLJ) has substantially underperformed the Vanguard Real Estate Index Fund ETF Shares (VNQ) so far in 2024, delivering an almost 19% loss against the ~10% total return for the benchmark ETF:
RLJ vs VNQ in 2024 (Seeking Alpha)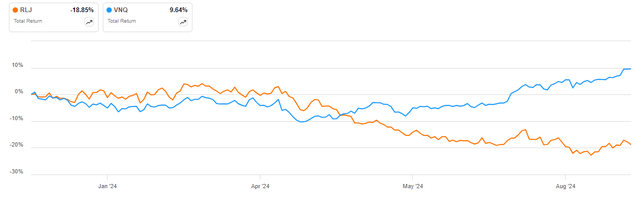
I also covered the shares back in March 2024 arguing they were undervalued in light of the company’s robust operating performance and the levered capital structure which will benefit from Fed rate cuts. After examining the company’s Q2 2024 results I still think the REIT is undervalued both from an adjusted FFO multiple and market-implied cap rate perspective and I expect the company to show stronger FFO in 2025, driven on the one hand by normalizing cost inflation, and on the other hand by Fed rate cuts which will reduce interest expenses.
Company Overview
You can access all company results here. RLJ Lodging operates 96 premium-branded urban-centric hotels, with the company’s largest exposure to Los Angeles/ Anaheim (8% of hotel EBITDA), followed by Washington, DC at 7%:
Portfolio overview (RLJ Lodging Q2 2024 Supplemental)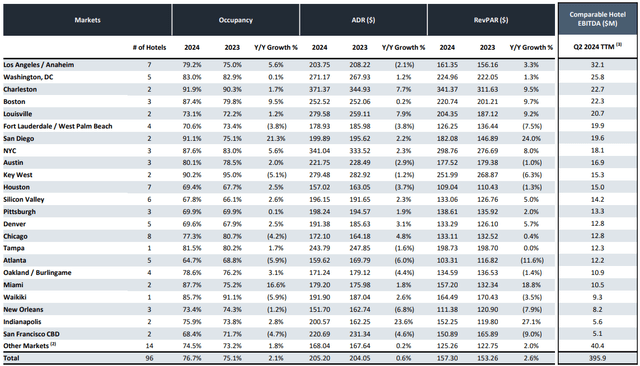
Operational Overview
In Q2 2024 the company reported revenue per available room, or RevPAR, growth of 2.6% Y/Y, driven primarily by a higher occupancy (+2.1% Y/Y) while the average daily rate, or ADR, only increased 0.6% Y/Y:
Key operatic metrics (RLJ Lodging Q2 2024 Q2 Results Press Release)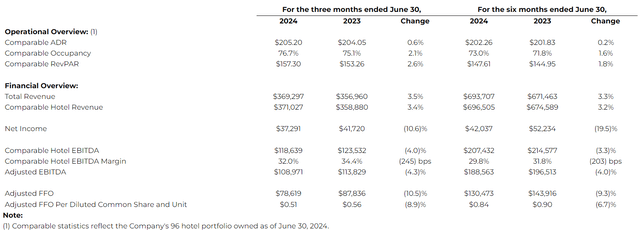
Relative to the first quarter of 2024, from the snippet above we observe that RevPAR growth accelerated, driven by both stronger occupancy and higher ADRs.
Adjusted FFO however was 8.9% lower Y/Y in Q2 2024, at $0.51/share, impacted by both higher operating expenses and elevated interest costs.
Reduced 2024 Outlook
Given the weaker-than-forecast RevPAR growth so far in 2024, the REIT cut its outlook across the board, and now expects RevPAR to increase by between 1% to 2.5% in 2024, respectively adjusted FFO should land at about $1.45-$1.58/share:
Reduced 2024 Outlook (RLJ Lodging Q2 2024 Q2 Results Press Release)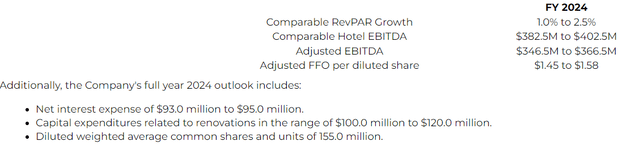
Taking the midpoint of adjusted FFO of about $1.52/share, we observe the cash flow multiple relative to the current share price, which stands at just 6.1x, a very attractive amount.
Capital Structure
The REIT ended Q2 2024 with a net debt of $1.85 billion and the company has $0.33 billion in preferred stock outstanding RLJ Lodging Trust CUM CONV PFD A (RLJ.PR.A). The market capitalization stands at $1.46 billion, indicating a combined enterprise value of $3.64 billion. As such, net debt accounts for 51% of enterprise value, opportunistically positioning the company should we observe a sector-wide compression in real estate cap rates, which I expect over the next few years.
29% of the debt is floating rate, indicating substantial immediate benefits from Fed rate cuts for adjusted FFO. On a run-rate basis, I estimate a 2% cut to the Fed funds rate (as futures markets currently price in by July 2025) will result in a $0.05/share boost to adjusted FFO, or about 3.3%.
The average debt maturity is 3.1 years, with an average interest rate of 4.75%.
Market-implied cap rate
The company should produce $236 million in adjusted FFO in 2024. Furthermore, the REIT will pay approximately $94 million in interest expenses and $25 million in preferred dividends. As a result, cumulative cashflows to enterprise value stand at $355 million, or a market-implied cap rate of 9.75% which is quite attractive as it already incorporates management overhead of about $60 million.
Adding back general and administrative expenses results in a market-implied cap rate of 11.4%, which is also very attractive, although it does point to the need for the company to optimize its overhead, or alternatively expand its portfolio.
The company’s capital expenditure budget for 2024 is $110 million, indicating a 3% impact on the market-implied cap rate from capex which is quite high. At the same time, consistently high capex will surely result in robust ADR growth down the line.
Valuation and prospects
As shown above, RLJ Lodging remains cheap both on an adjusted FFO (6.1x) and a market-implied cap rate (9.75%) basis. I expect operating expenses growth to moderate alongside inflation in the next couple of years, which coupled with significant capex will likely boost RevPAR and in turn adjusted FFO.
The company also boosted its quarterly dividend by 50% to $0.15/share, maintaining good coverage and at the same time reinvesting excess cash flows into capital expenditures.
Risks
The main risk I see for RLJ Lodging is a potential recession, the likelihood of which has arguably increased given the weakening of the US labor market over the past year. This will negatively affect hotel demand and likely result in depressed occupancy and ADR growth.
I would also highlight that RevPAR growth is driven primarily by occupancy gains, which cannot continue indefinitely. A more sustainable driver of RevPAR growth is increases in the ADR, which have been running below inflation, indicating a weak competitive position.
Last, but not least, considering that net debt accounts for 51% of enterprise value, a slower than currently anticipated pace of Fed rate cuts will negatively affect the REIT.
Conclusion
RLJ Lodging reported mixed Q2 2024 results, with robust RevPAR growth offset by elevated operating expenses, ultimately resulting in lower FFO. The company also cut its full-year outlook, indicating no immediate turnaround in operational performance.
Even so, the REIT remains attractively valued both in terms of adjusted FFO multiple and market-implied cap rate. The capital structure is also well-positioned to benefit from real estate cap rate compression and the 29% in floating rate debt will provide a boost to cash flows as soon as the Fed starts cutting interest rates.
All in all, I think RLJ Lodging is still worth a buy rating, notwithstanding risks related to a potential recession.
Thank you for reading.
Credit: Source link