
filo
Rithm Capital Corporation (NYSE:RITM) continued to earn its $0.25 per share per quarter dividend easily with distributable earnings in the second quarter.
Rithm Capital also grew its book value and disclosed solid financial results, driven by gains in the Mortgage Servicing Rights portfolio. I anticipate Rithm Capital to do more acquisitions moving forward, particularly in the asset management business, in order to diversify its mortgage-heavy investment portfolio and create new income streams.
From a dividend safety angle, Rithm Capital offers up one of the most secure 9% yields that are available in the market, in my view.
My Rating History
A low dividend pay-out ratio and a higher-for-longer rate environment led me to evaluate Rithm Capital as a Strong Buy in May. Rithm Capital is a well-diversified and expanding its business in the asset management business which could help the trust achieve lower earnings volatility moving forward.
With the dividend also being quite well-covered with distributable earnings, I think RITM remains a buy for passive income investors.
Portfolio Review
Rithm Capital is a mortgage-focused investment company, but it has started to change and broaden its investment scope.
Last year, Rithm Capital acquired Sculptor Capital in 2023, an asset management business with $32 billion in assets, in order to diversify its portfolio and income streams.
The core investment for Rithm Capital is still Mortgage Servicing Rights which are unique mortgage assets in the industry. They offer investors upside in a rising-rate environment because they become more valuable as the life of the fee stream gets extended. As such, they are pro-cyclical investments and have been key to Rithm Capital’s mortgage-based investment strategy in recent years.
Mortgage Servicing Rights remained the largest pillar in Rithm Capital’s investment portfolio and accounted for $9.7 billion of investment assets, reflecting 11% QoQ growth. Other investments in the mortgage trust’s portfolio included Consumer Loans, Single Family Rentals, Residential Mortgage Loans and other mortgage investments.
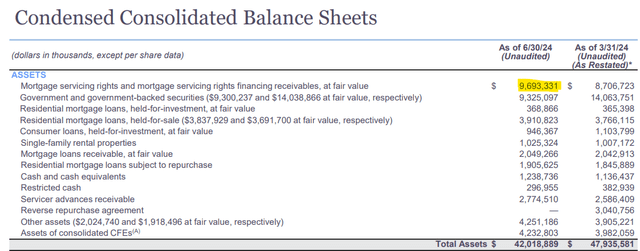
Condensed Consolidated Balance Sheets (Rithm Capital Corporation)
Mortgage Servicing Rights are paying servicing fees for Rithm Capital and in the second quarter, the mortgage trust’s MSRs produced $431.1 million in servicing revenues, which was the second-highest sales stream. Only interest income, which captures earnings from the trust’s residential mortgage and consumer loan portfolio, had higher revenues of $478.7 million.
The breakdown for the second quarter also showed that the asset management is starting to produce some respectable results: The new asset management service line produced $109.4 million in revenues in 2Q24, up 44% YoY.
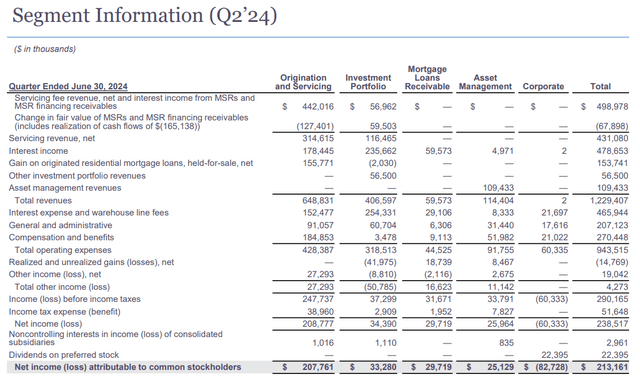
Segment Information (Rithm Capital Corporation)
In June, Rithm Capital became the external manager of Great Ajax, an investment company that is transforming into an opportunistic commercial real estate REIT.
I anticipate Rithm Capital to do more acquisitions in the asset management industry and expand the scope of its investments. Moving forward, Rithm Capital is poised to become a diversified asset management company with distinct service lines in credit, real estate and asset management. The increasing diversification of the investment portfolio should lead to an even higher quality and more diversified income stream for shareholders.
Dividend Coverage
Rithm Capital is a well-managed mortgage real estate investment trust, though the company is becoming more of an all-round investment manager that has moved beyond its core mortgage investments.
In the second quarter, Rithm Capital earned $0.47 per share in distributable earnings which equates to a dividend pay-out ratio of only 53%. In the last twelve months the mortgage real estate investment trust paid out even less than that, only 49% of its cumulative distributable earnings which translates into a very high margin of safety.
Annaly Capital Management, Inc. (NLY) paid out 98% of its distributable earnings. Though Annaly Capital Management has bit of a different focus in the mortgage industry (the mortgage trust primarily invests in mortgage-backed securities) than Rithm Capital, it does have some exposure to Mortgage Servicing Rights as well.
From a margin of safety angle, Rithm Capital is one of the best deals that passive income investors can get in the REIT industry, in my view.
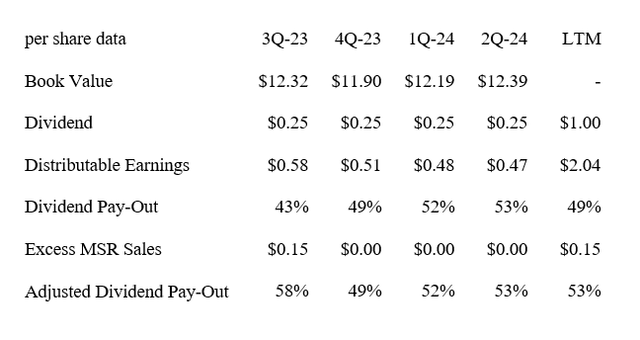
Dividend (Author Created Table Using Trust Information)
Discount To Book Value
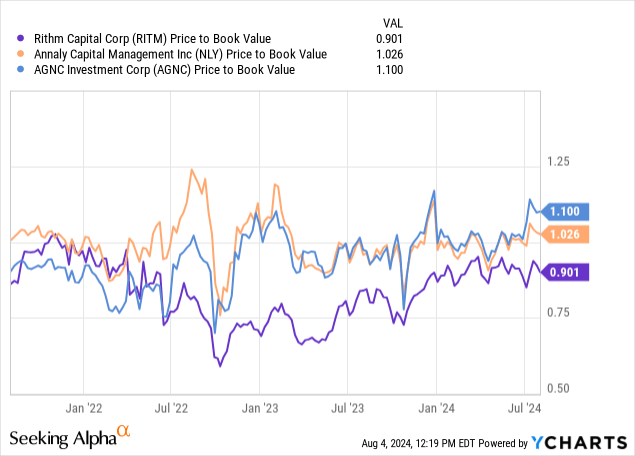
Rithm Capital’s book value grew 1.6% in the last quarter and the mortgage real estate trust had a book value of $12.39 as of June 30, 2024. Strong Mortgage Servicing Rights results added to the QoQ gain in book value. With a stock price of $11.35, the stock of Rithm Capital sells for an 10% discount to book value.
Agency MBS-focused mortgage trusts like Annaly Capital Management and AGNC Investment Corp. (AGNC) are selling for 3% and 10% premiums to their book values, respectively.
Taking into account that Rithm Capital is offering investments into multiple different and uncorrelated mortgage investments, I think that Rithm Capital at the very least could rerate to book value which implies an intrinsic value of $12.39 per share.
Why The Investment Thesis Might Not Play Out
Rithm Capital is overweight Mortgage Servicing Rights which are becoming less appealing investments in a low-rate environment. MSR values tend to increase during periods of rising rates and fall during periods of falling rates which makes them directional rate investments.
With the central bank closing in on its first rate cut (anticipated for September 2024), I think that MSRs are becoming less compelling investment choices for passive income investors.
I anticipate Rithm Capital to strategically reduce its MSR investments in the next couple of quarters, however, in order to remove a source of potential valuation risk from its balance sheet.
Since Rithm Capital is also becoming more diversified through its investment in Sculptor Capital, I think that the long-term asset mix will shift away from Mortgage Servicing Rights.
My Conclusion
Rithm Capital grew its book value in the second quarter, the Mortgage Servicing Rights Portfolio for now is performing well and the mortgage real estate investment trust once again covered its dividend with distributable earnings in the second quarter.
It should be noted that Rithm Capital continued to achieve a substantial amount of excess dividend coverage in 2Q24 with the trust paying out only 53% of its distributable earnings.
The value proposition remains compelling, in my view, because Rithm Capital is selling at a discount to book value and the 10% book value discount on top of a significant dividend margin of safety makes the trust’s stock a buy for passive income investors.
Credit: Source link