

























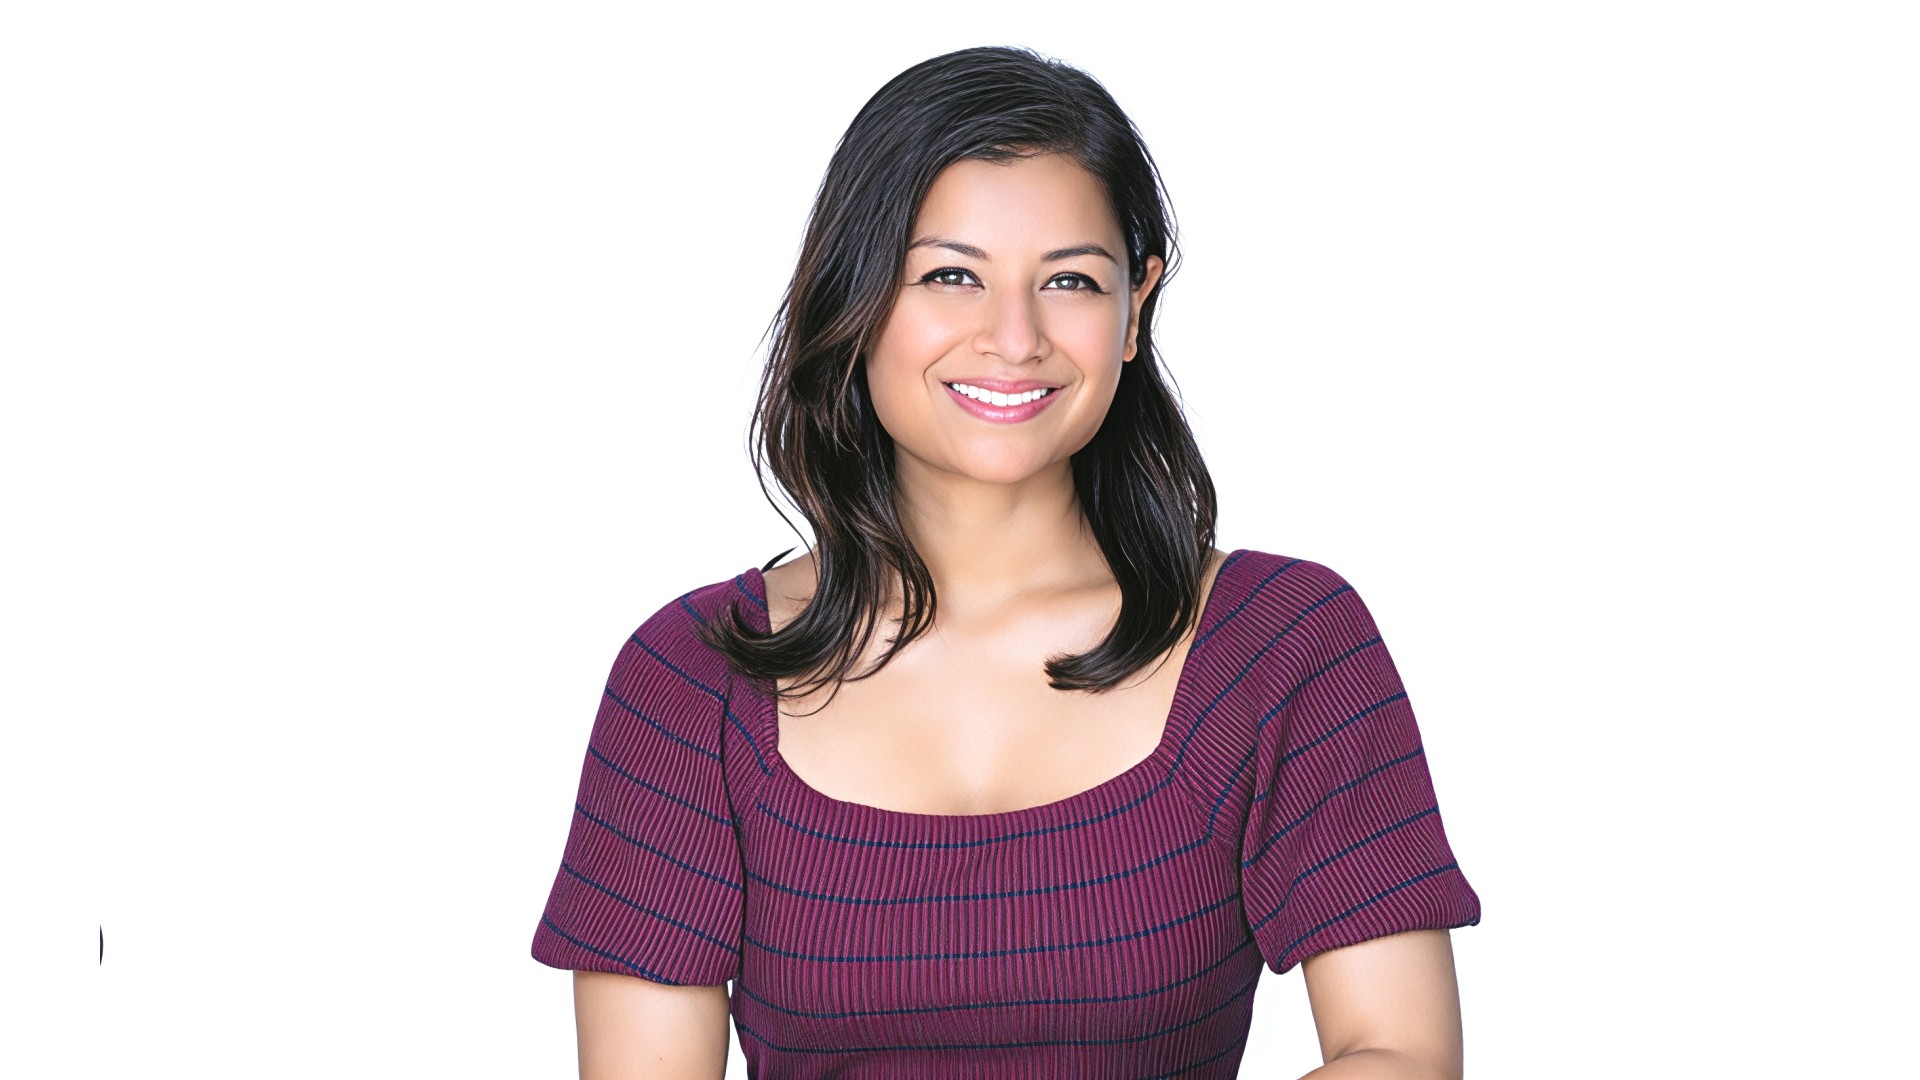
Priya Saiprasad, General Partner at Touring Capital, is a venture capitalist and technology investor with extensive experience across enterprise software, artificial intelligence, and growth-stage investing. She co-founded Touring Capital after a career spanning venture capital, M&A, and enterprise technology, including serving as a Partner at SoftBank Vision Fund, where she led investments in companies such as Pixis, Vendr, Observe.AI, CommerceIQ, Sendoso, and Skedulo. Previously, she focused on AI and analytics investments at Mayfield Fund and was a founding member of M12, Microsoft’s venture fund, where her investments included Go1, WorkBoard, PandaDoc, Element AI, and Bonsai. Earlier in her career, she worked on M&A and corporate development at Square. Saiprasad currently holds several board positions and was named to Forbes’ 30 Under 30 list for Venture Capital in 2018.
Touring Capital is a San Francisco-based venture capital firm focused on backing the next generation of AI-powered software companies. The firm invests primarily in early-stage and early-growth businesses approaching product-market fit, with an emphasis on companies using AI to transform enterprise workflows and create measurable customer value. Touring was founded by investors with experience across M12, Qualcomm Ventures, and SoftBank Vision Fund, and in 2025 closed an oversubscribed $330 million inaugural fund to expand its investments in AI-driven software companies globally. Its investment approach emphasizes durable data advantages, product flywheels, domain expertise, and clear paths to commercial scale rather than AI adoption for its own sake.
You co-founded Touring Capital after a career that included helping build M12, investing at Mayfield, and serving as a Partner at SoftBank Vision Fund. What convinced you it was the right moment to launch Touring Capital, and what did you want to do differently as an investor in the emerging AI era?
Across M12, Mayfield and SoftBank, I had the opportunity to see company building from several vantage points: early-stage investing, growth investing, and the technology platforms that shape how startups scale. AI brought those experiences together with the potential to change how work gets done across nearly every industry.
When software can perform work, it changes the product, the addressable market, the pricing model and the economics of the company delivering it. We wanted to build Touring around that opportunity from the outset.
Our focus is on companies approaching or demonstrating early product-market fit, when technical promise starts translating into customer adoption. That is a particularly consequential stage in AI: founders are deciding which workflows to own, how much autonomy customers will accept, and how to turn early demand into repeatable growth.
We also wanted to bring a company-building perspective informed by our experience across venture, M&A and large technology platforms. Our ambition is to help founders build businesses whose competitive advantages deepen as the technology advances. That requires conviction about the opportunity and a willingness to continually reexamine the assumptions underneath it.
You’ve argued that some of the biggest AI opportunities are shifting away from simply building larger foundation models and toward companies applying AI to specific industries. What has changed technologically or economically to make the application layer so compelling now?
The models have become dramatically more capable and accessible, which changes where entrepreneurs can create value. You no longer need to build the underlying intelligence from scratch to build something powerful.
That shifts the question from, “Who has the best model?” to, “Who can apply that intelligence to solve a problem in a way that fundamentally changes the economics or the workflow?”
The most compelling companies aren’t simply putting an LLM in front of an existing software product. They’re using AI to rethink how work gets done. In some cases, that means automating large portions of a workflow. In others, it means allowing a much smaller team to produce significantly more output.
That’s where I think a lot of the next wave of value creation will happen: companies that can take increasingly capable intelligence and turn it into a product customers trust to do meaningful work.
When you look across sectors today, which industries do you believe are reaching a genuine AI inflection point, where AI could fundamentally restructure workflows rather than simply make existing software more efficient?
I’m particularly interested in industries with a combination of significant knowledge work, complex existing workflows and historically lower levels of software penetration.
Financial services, healthcare, legal, industrials and automotive are good examples. These industries often have enormous amounts of valuable information and highly specialized workflows, but much of the work is still fragmented, manual or dependent on experienced people moving information between systems.
The opportunity isn’t simply to make those workers 10% more productive. The more interesting companies are redesigning the workflow around what AI can now do.
You can see that in companies like Numa, which is using AI agents to automate customer interactions and dealership operations, and Daloopa, which applies AI to the highly time-sensitive data and research workflows used by financial institutions. The common thread is a deep understanding of the underlying work. AI is powerful, but it doesn’t eliminate the need to understand the industry you’re building for.
Touring Capital emphasizes data moats, product flywheels, and domain-specific expertise when evaluating AI companies. What does a truly defensible vertical AI business look like, and how do you distinguish one from a company whose main advantage is simply wrapping a third-party large language model?
A truly defensible AI business gets stronger as it operates.
The underlying model may improve over time, and a company may switch models entirely, but the value of the business shouldn’t disappear because the model underneath changes. What matters is what the company owns around that model: the customer relationship, the workflow, the proprietary data, the integrations and the trust to take on increasingly important work.
One of the things we pay close attention to is whether the product becomes more deeply embedded over time. Are customers trusting it with more work? Are usage and outcomes compounding? Is the company learning from its deployments in ways that improve the product?
Those dynamics create a much stronger business than simply having a good interface on top of a third-party model. Features can converge very quickly in AI. Sustained usage and deeper workflow adoption are much harder to replicate.
As foundation models become more capable and increasingly commoditized, does that strengthen vertical AI companies by giving them cheaper intelligence to build on, or does it create a risk that the model providers themselves absorb more of the application layer?
Both dynamics can occur simultaneously. Better models expand what application companies can deliver, while also allowing model providers to move further into products and workflows.
The question to diligence is how a company’s position changes as the underlying intelligence improves. We ask two questions together: what becomes possible for this business with the next generation of models, and what part of its current value proposition might become a standard model capability? That helps distinguish companies benefiting from progress from companies whose differentiation depends on a temporary limitation.
Vertical businesses can build durable positions through specialized workflows, customer access, integrations, evaluation systems and the operational responsibility they assume. Those advantages require continuous investment; domain expertise by itself is not permanent protection.
The companies I find most compelling have a clear path to taking on more valuable work as models improve. Their customers get better results, their delivery economics strengthen, and their accumulated knowledge becomes more useful. That is the relationship with model progress we want to underwrite.
Traditional software-as-a-service companies have historically been evaluated using metrics such as annual recurring revenue, gross margins, retention, and seat expansion. How is AI changing the metrics you rely on, particularly as inference costs, usage-based pricing, and outcome-based business models become more important?
ARR, retention and gross margins still matter. The problem is that, on their own, they no longer tell us enough.
An AI company can grow to tens of millions in ARR incredibly quickly while underlying usage inside its customer base is already declining. The customer may still be under contract, but by the time renewal comes around, the product has effectively been replaced. That’s what we describe as latent churn.
So we’re increasingly looking beneath the pricing model and asking what work is actually being done. Are the number of workflows and outcomes increasing over time? Is the customer trusting the product to do more work? Is usage continuing after the initial excitement of deployment?
We’re also looking much more closely at the economics behind the growth. AI companies can replace human headcount with automation, but compute becomes a real part of the workforce and cost structure. That’s why we look at concepts like workflow intensity, efficiency multipliers, revenue per adjusted employee and cost leverage.
The bigger question is whether growth is becoming more durable and efficient over time. Spectacular growth and durable growth are not necessarily the same thing.
Many AI agents are being designed not just to assist employees but to complete entire workflows autonomously. How does that change the market opportunity for enterprise software, and could AI companies ultimately capture a portion of the labor budgets that historically sat outside software spending?
I think this is one of the most important shifts in enterprise software.
Historically, software was largely sold as a tool that helped an employee do their job. The employee remained responsible for producing the work, and the software budget was separate from the labor budget.
AI changes that equation because software can increasingly perform portions of the job itself.
That expands the market opportunity significantly. You’re no longer just selling a productivity tool out of an IT or software budget. If a product can reliably take ownership of meaningful work and produce a measurable outcome, it can potentially capture value from labor budgets as well.
The important distinction is between an AI assistant and an AI system that customers trust to actually execute. The latter has the potential to become far more valuable, but it also has to demonstrate real reliability, accountability and economics. Customers ultimately won’t care how sophisticated the AI is if the product can’t consistently deliver the outcome it promised.
You currently sit on the boards of companies including Numa and Daloopa, which apply technology to very different verticals such as automotive operations and financial data. What have these companies taught you about what it takes to successfully introduce AI into industries with deeply established workflows and domain expertise?
The biggest lesson is that AI doesn’t eliminate the importance of domain expertise. In many ways, it makes it more important.
To successfully introduce AI into an established industry, you need to understand the workflow deeply enough to know where automation actually creates value and where human judgment still matters. You also need to understand how customers will adopt the product, how it fits into their existing systems and AI adoption cycle, and what it takes to earn their trust.
Numa and Daloopa operate in very different markets, but both are deeply connected to the specific work their customers need to accomplish. The most successful vertical AI companies don’t start with, “Where can we put AI?” They start with a meaningful problem or workflow and then redesign it around what AI can now do.
That’s also why I think domain expertise can become a significant advantage over time. The deeper you understand the work, the more effectively you can build a product customers are willing to rely on.
Touring’s recent investments span both domain-specific applications and enabling AI infrastructure. How do you think about the balance between investing in the application layer versus the infrastructure required to power it, and where do you believe the greater opportunity for venture-scale returns exists today?
We don’t view the opportunity as exclusively existing in one layer of the stack. We’re focused on where important bottlenecks are emerging and where a company can build a meaningful position as AI adoption scales.
On the application side, we’re excited by companies that can translate AI into measurable economic value by owning important workflows and delivering real outcomes. On the infrastructure side, we’re interested in the companies solving the constraints that determine whether AI can actually be deployed efficiently at scale.
Our investments in companies like Infinity and Parasail reflect that. One is addressing the software challenge of making different AI chips ready to run modern models, while the other is helping developers deploy and scale AI workloads without having to manage the underlying infrastructure themselves.
The better opportunity isn’t necessarily determined by whether a company sits in applications or infrastructure. The key question is whether the company is solving an important and durable problem with the potential to become increasingly valuable as the AI market evolves.
With enormous amounts of capital now concentrated around a relatively small number of frontier AI companies, where do you believe investors are still underestimating the opportunity, and which AI-native categories or business models are receiving far less attention than they deserve?
One area I find particularly interesting is the middle of the market.
Right now, venture has become increasingly barbelled. There is enormous appetite for promising companies at the earliest stages, particularly those with exceptional teams and compelling technology. There is also substantial capital available for the very largest, most proven companies.
But the middle, particularly the traditional Series B and C stages, has become much more difficult.
AI has compressed expectations. Companies can now go from zero to meaningful revenue faster than we’ve ever seen, which has raised the bar dramatically once a business starts generating revenue. Growth that would have been considered extraordinary a few years ago may no longer stand out in today’s market.
That creates both risk and opportunity.
Some companies are being pushed to optimize for whatever the fundraising market wants at a particular moment: 5x growth, 10x growth, a certain revenue milestone, regardless of whether that trajectory creates a durable business. The market can change dramatically in six to nine months, so founders have to be careful not to build exclusively for the expectations of the next financing round.
For investors, I think there is real opportunity in identifying companies that have strong underlying fundamentals but don’t fit neatly into the extremes of today’s market. The challenge is being disciplined enough to distinguish durable growth from a company simply being pulled forward by the current AI financing cycle.
Thank you for the great interview, readers who wish to learn more about this VC firm should visit Touring Capital.
Credit: Source link