
Brandon Woyshnis
According to my projections, declining interest rates and strengthening consumer demand have the potential to create a favorable environment for outperformance in the automotive sector in 2024. In that context, I am particularly optimistic about Porsche (OTCPK:DRPRY), due to the company’s strategic focus on value over volume, as well as pragmatic approach to the EV transition. To render the argument even more attractive, I point out that Porsche is currently cheap, with shares trading at an EV/EBIT of around 10x. Based on a residual earnings valuation model, I argue Porsche stock should be worth about $13.4/ share. “Buy”.
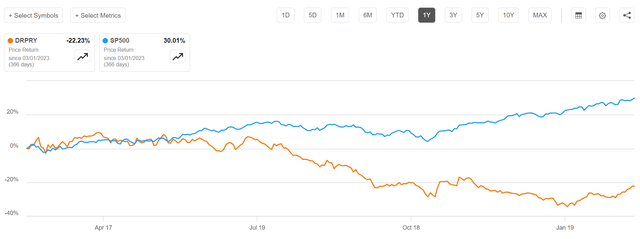
For context, Porsche stock has underperformed the broad equities market in 2023 and early 2024. For the trailing twelve months, Porsche shares are down about 22%, compared to a gain of approximately 30% for the S&P 500 (SP500).
Seeking Alpha
Resilient Performance In 2023, Despite Macro Pressure
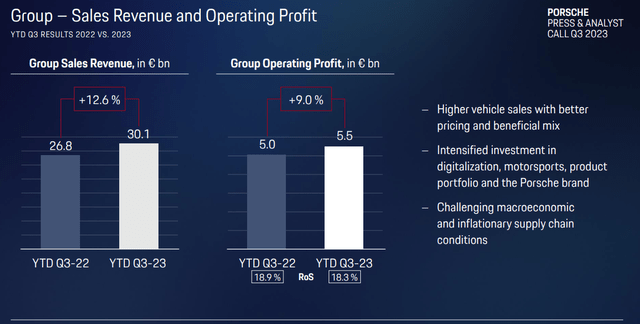
Despite a lagging share price, Porsche delivered a solid 2023, broadly topping (soft) expectations through Q3. For the trailing nine months leading up to the December quarter, Porsche generated EUR 30.1 billion in sales, up 12.6% YoY. Group operating profit increased to EUR 5.5 billion, representing an increase of 9% YoY compared to the same period in 2022. Investors should consider that Porsche’s strong performance was supported by pricing rather than volume. In fact, Porsche’s average selling price per car increased to EUR 118,000 as of Q3, up from EUR 110,000 in the previous quarter.
Porsche Investor Presentation Q3 2023
Together with Q3 results, Porsche confirmed its full-year financial targets, forecasting a revenue midpoint of €41 billion and an EBIT margin between 17% and 19%. Looking ahead, Porsche is set to release its FY23 results on March 12; but I argue the results are unlikely to reveal any new information or move sentiment. In fact, I point out that unit sales, which dropped 12% YoY, were already disclosed on January 12. This drop is primarily attributable to a strong 2022 benchmark, as well as a difficult market situation in China. Personally, I predict a 9-10% YoY decrease in Q4 revenues and an operating margin of 17-18%, leading to an operating profit of approximately €1.7 billion (annualized about €7 billion of profit, compared to a market cap of about €40 billion).
Macro Shifts Favorably
I am optimistic about the automotive sector heading into 2024. My optimism is based on the broader macroeconomic context, as I see falling interest rates as a significant tailwind for capital goods consumption. It’s important to note that a substantial portion of automobile purchases are financed through credit. Consequently, a decrease in credit costs is likely to boost consumer confidence and stimulate demand for vehicles. The argument is especially valid for high-priced brands such as Porsche. As a second driver of the automotive industry’s commercial momentum in 2024, I argue that the decline in energy prices and overall inflation is expected to enhance OEM’s operating leverage on higher revenues.
Turning to Porsche’s commercial strategy, I appreciate the company’s commitment to prioritizing value over volume and its focus on maintaining a premium position in the automotive sector. In my opinion, this premium-oriented approach will insulate the German automaker from potential price competition posed by emerging electric vehicle startups, especially those originating from China. In fact, Porsche’s marketing strategies emphasize exclusivity and luxury, appealing to a demographic that values these traits over cost-saving considerations. Moreover, Porsche’s clientele is considered highly loyal to the brand, rendering Porsche customers less susceptible to the market fluctuations that might sway a more price-sensitive customer base.
I also like that Porsche management is sensibly and successfully expanding its EV portfolio, with battery electric vehicles (BEVs) making up 13.4% of sales as of Q3 2023. For 2024, Porsche’s upcoming vehicle pipeline includes an all-electric Macan. The new Macan features a lithium-ion battery with a 100 kWh gross capacity, allowing for fast charging up to 270 kW.
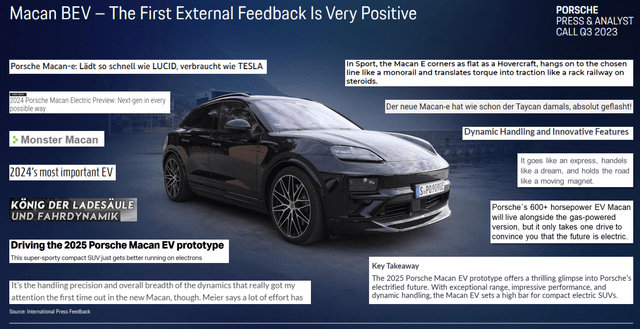
Porsche Investor Presentation Q3 2023
Valuation: Set Target Price At $13.4/Share
To value a relatively mature business like Porsche, I am a great promoter of using a residual earnings model, which anchors on the idea that a valuation should equal a business’ discounted future earnings after capital charge. As per the CFA Institute:
Conceptually, residual income is net income less a charge (deduction) for common shareholders’ opportunity cost in generating net income. It is the residual or remaining income after considering the costs of all of a company’s capital.
With regard to my Porsche stock valuation model, I make the following assumptions:
- To forecast EPS through 2027, I anchor on the consensus analyst forecast as collected by Refinitiv.
- To estimate the capital charge, I anchor on Porsche’s cost of equity at 8.5%.
- For the terminal growth rate after 2025, I apply 2.25%, which is about in line with estimated nominal global GDP growth.
Given these assumptions, I calculate a base-case target price for Porsche stock of about $13.4/share.
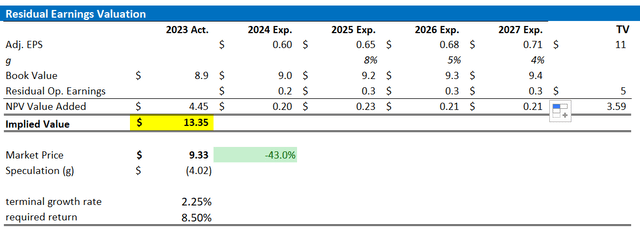
Refinitiv; Company Financials; Author’s Calculations
As I argued that my estimates for growth and equity charges may be conservative, I acknowledge that investors may hold varying assumptions regarding these rates. Therefore, I’ve included a sensitivity table to test different scenarios and assumptions. See below.
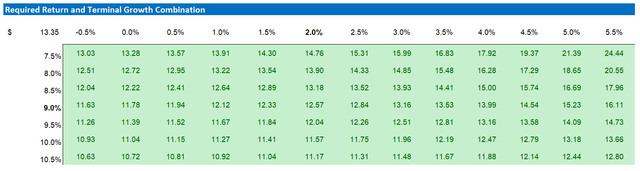
Refinitiv; Company Financials; Author’s Calculations
A Note On Risks
Investing in Porsche stock is not without risk. Specifically, I point out the possibility of a challenging economic climate, with “higher for longer interest rates” potentially impacting the sales volume of Porsche vehicles in 2024. Additionally, geopolitical tensions, such as those arising from the Ukraine conflict, along with Porsche’s significant market presence in China, present potential uncertainties for the business. Lastly, as the automotive industry is cyclical by nature, Porsche’s stock value may be subject to fluctuations in investor sentiment.
Investor Takeaway
I predict a positive outlook for the automotive sector in 2024, driven by declining interest rates and rising consumer demand. In that context, I view Porsch as a particularly attractive investment opportunity, due to the company’s strong brand equity, focus on premium pricing over volume, as well as sensible electrification transition strategy. In my opinion, the stock can be considered undervalued, with a target price set at $13.4/ share based on a residual earnings valuation model.
Editor’s Note: This article discusses one or more securities that do not trade on a major U.S. exchange. Please be aware of the risks associated with these stocks.
Credit: Source link