David McNew
Above: Will Shari open the legacy gates to PARA at the present deal bids?
There are three sides to every story: my side, your side and the truth, And no one is lying…
– Robert Evans movie mogul (1930-2019)
The above mote of wisdom emanated from one of the most successful survivors of the entertainment business, whose hits include Rosemary’s Baby and The Godfather. His tenure at Paramount (NASDAQ:PARA) is thought to be among the company’s golden ages. The problem of trying to arrive at a smart decision about the stock in the sector is that everyone is either right or wrong at the same time. One must conclude what we all believe is some logical base for our liking or passing on the PARA stock at its current price range coming out of a better Q4’23.
google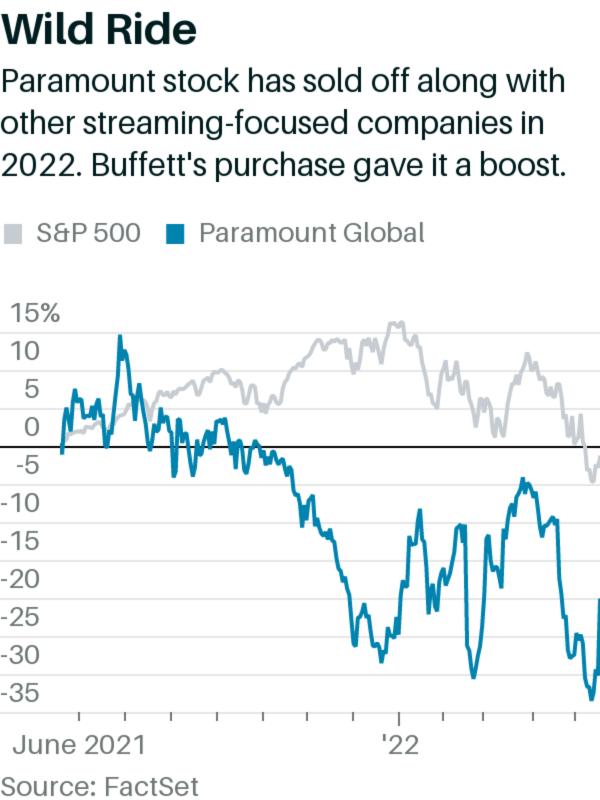
Above: The presence of Warren clearly buoyed some bullish hopes since 2021 but that is no longer a support position. Yet 2-23 looking better could be giving Shari pause not to jump on anything now on the table.
Stipulation: One of our key sources of informed outlooks on the overall Paramount situation is a former c-suite executive in the sector, now retired. He follows PARA among other stocks in the sector not only because of his career experience but also because he recently sold his position. He said:
I got tired of sensing a deal was imminent as a catalyst… I believe Shari was being not skipping toward a hard commitment to selling to Skydance and may be motivated now to find another potential acquirer at a better price.
To get an industry view of the PARA situation, I assembled a zoom panel of former colleagues and clients I had come to know over decades. They all have served as either advisors or c-suite executives in studios, TV networks or as lead bankers on deals. They agreed to participate but not have their opinions attributed. We have complied with those requests.
Last week we talked about the prospects for a PARA deal going forward. One of our responders has followed the progress or lack of same for the Skydance bid. He told me his opinion has changed since the release of Q4’23 results…
google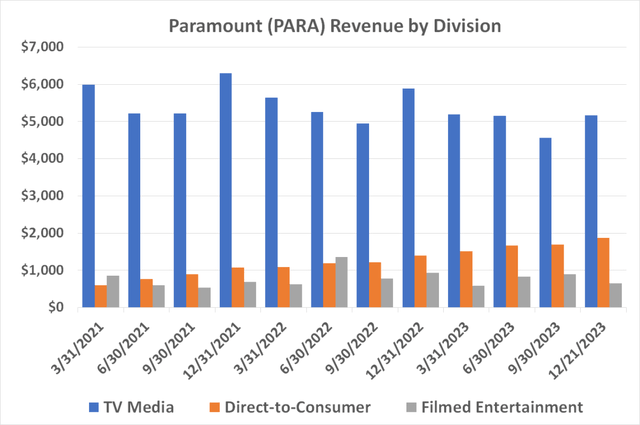
I’m not suggesting they are any closer or farther away from a deal or a termination of talks. Friends around the industry think Shari could be slow walking the Skydance deal as she contemplates possibly stronger results trending ahead. That would make sense given what we now see as positive shoots in the Q4’23 results.
He also agreed that Shari was highly motivated to sell:
But she’s not going to give away the store. I had been involved with Sumner on deals over the years. His approach was always to extract maximum value out of deals. She’s his student.
What’s changed, if anything?
PARA just sold their 13% stake in India Viacom to Reliance for $517m. It’s too early to signal whether that move is part of a larger agenda that comes from the special advisor group Shari has assembled to weigh in on options going forward.
Analysts have been split on whether prospects for PARA have improved enough to call a buy or whether massive headwinds in linear and DTC segments plus a large debt overhang doom the stock to go nowhere. And by extension, kill deal prospects.
para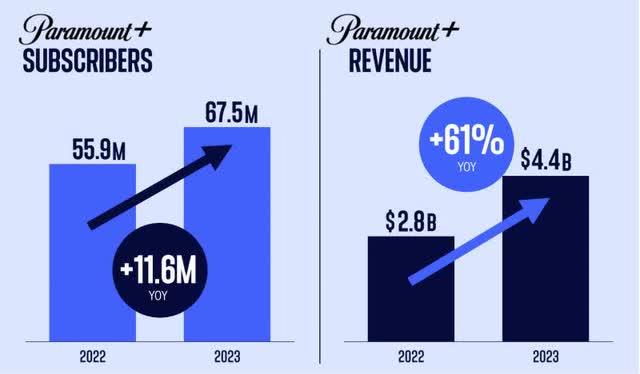
Above: Is this enough to ignite a change in deal expectations?
FY 2023 results brought in revenue of $29.65b, or $200m short of consensus expectations. More telling for bull scenario buyers was the turnaround in earnings. PARA showed $0.04 for 2023 vs. 2022 loss ($1.01). A few ticks yes, but a positive nonetheless. There were gains in DTC subscriptions, continued declines in linear/cable ads and total revenue. The record Super Bowl viewership supports some thinking that linear still has a chance to shine when and if its programming costs match ad revenue possibilities.
Bear outlooks remain as well sprung from continuing disbelief that PARA and its sector peers have reached anywhere near what appears to be a viable new business model for streaming.
Sitting in Mr. Market’s skeptic’s chair is the fact that Warren has recently sold off a third of his PARA position. Many believe he was averaged in the mid $20s so he clearly felt convinced enough to swallow the loss. But realists know that Warren’s not so secret of success above all qualities of his investing style is patience. So when he apparently runs out of patience, one must assume that his analysis up down and sideways came up SELL. And if so, the market, despite the several upside indicators of the recent PARA move, small as it is, portends good things ahead, a case that Warren didn’t buy.
The stock has been in full force decline since last April when it traded ~$22 to where it sits at writing at $11.59.
The book value at the end of 2023 was $34.51 a share, nearly three times as high as it is currently trading.
The Allen deal proposed to PARA averages out to ~$25 a share for the total voting and non-voting shares, or $30b. Based on year-end results, we asked our colleagues whether that would trigger a rise in the Allen bid, or whether Skydance as well would have to shift its strategy to buy only NAI?
Our panel’s top 5 consensus appraisals of the state of play
If Warren sold, given his average entry point as they believe, it was motivated by a final negative call on prospects ahead. All agree the Q4’23 results do detect somewhat better times ahead, including a profitable 2024. But all likewise think that neither PARA nor its peers are out of the fiscal woods as long as the dreadful debt overhang looms. All agreed that linear will see a nice uptick this year due to the presidential election-but that it likewise will be short-lived and the vertical’s problems will persist.
All believe that Skydance, to the best of their knowledge of key people in the situation, has not as yet actually reached out for finance to do the PARA deal. One person thinks it is because they sense the talks will take a lot longer now than anticipated as the “first fairly possible crocus has popped off the FY results”. An entertainment attorney, who back in the day, had been part of legal teams for both Sumner and Shari, agreed with the slow walk take at the moment:
From day one, not matter how motivated Shari has been to sell, she clearly has a number in mind that my guess tells me is way off what she wants. The recent positive results will feed into what happens over the next months.
We believe another deep dive into the massive data what ifs of the media/entertainment sector is no longer the issue here for PARA. What our discussions with our industry friends believe is now the only focus is this: The prospect that Shari now has more of a rationale to stiffen her price demands is a fact. While nobody ever can predict outcomes in such situations, the consensus of our group is that the deal maker price will be above that which currently is on the table from both Skydance and Allen.
From our perceptive, we believe so much of the what if analysis is whether to sell now or take a shot at $11 on the theory – and that’s what it is that Shari will hold fast for a better price now than what is on the table.
The upcoming Disney proxy vote will give us a bit of a window as to how shareholders of the leadership stock in the sector feel. And, by extension, whether investors in the space have bought into the very similar recovery plans among all peers. If you read earnings releases across the sector, what you see is a virtual carbon copy of what the streamers RXs are. Lower costs in production, move to ad supported, fingers crossed on linear continued aggressive repayment of debt. And the durable mantra, “We’ll make content consumers will love.”
If the Q4’23 and FY23 results of PARA portend the same shifts in a recovery strategy as DIS and all major peers, then we believe Shari might well be expecting raised bids. We shall see.
DIS CEO Iger has said he expects streaming to turn profitable by the end of this year. Investors have traded the stock to $112 from where it was dead pooled for a long duration ~$82.
WBD was $12.26 last December and now sits at $8.52, indicating the more positive tone on DIS isn’t shared by the market. Yet all peers in the sector face the same set of challenges this year. But only PARA continues to present the single most cogent case for a sale either of some verticals or the entire company.
Our group still believes the endgame of PARA needs to be either a significant sale of assets to reduce debt or the entire company. The newest question we believe is this: If indeed our guess is right that Shari is slow, is she looking to draw a bigger, deeper pocketed acquirer to step into the fray?
So while it all remains a dice roll as to whether we are just passing through some kind of quiet contemplation mindset of the principals, or whether in fact PARA awaits the entry of another bidder-holding seems a strategy for the moment.
google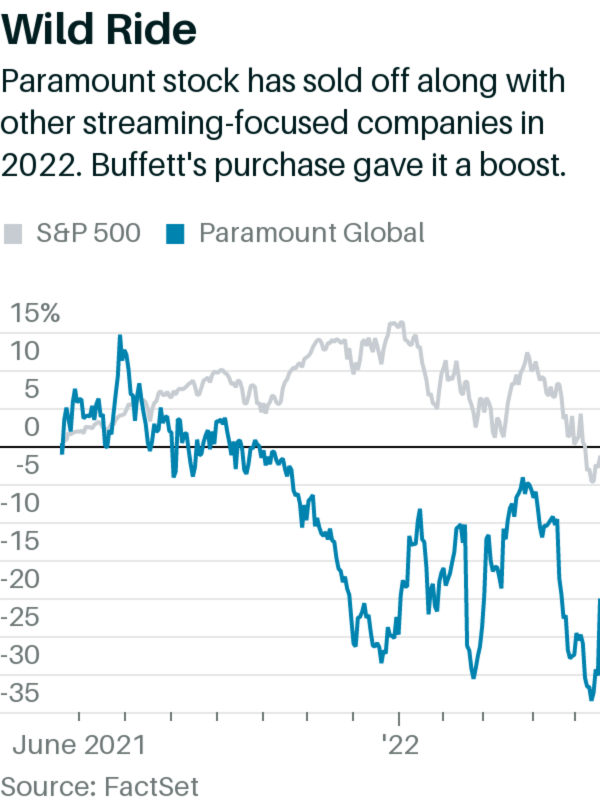
We don’t rule out the old durable endgame of take the money and run here, but we do believe, as does our panel, that perhaps Shari and her advisor committee are pumping the brakes in a slowdown. That could add to the case for HOLD.
Credit: Source link