
PM Images/DigitalVision via Getty Images
Summary
PagerDuty (NYSE:PD) offers a real-time incident management platform that allow to automate and accelerate threat detection and response. We think that the company’s durable growth and margin can afford a much higher valuation multiple versus what it currently trades at.
Business
PagerDuty provides digital operations management solutions and differentiates itself in the real time operations where the time to response needs to be much lower than in traditional workflow driven set-ups.
The company’s key offering, the PagerDuty Operations cloud is a SAAS offering that consists of the following four solutions to predict, mitigate, and respond to incidents in real-time:
- PagerDuty Incident Management: This platform enables real time response to incidents with an overlay of intelligence gathered from previous incidents. Automation of responses leads to reduced resolution time, with a real-time view of the service health helping to pre-empt potential incidents.
- AIOps: This offering is the application of machine learning to data emanating across different platforms, enabling users to triage billions of data points to enhance triage and addressal of incidents.
- Process Automation: This is a platform for orchestrating workflows that spans the entire organization, helping speed up incident resolution.
- Customer Service Operations: Solution that helps scale customer impacting issues.
Key competitors include Atlassian, Splunk, Red Hat, Everbridge and ServiceNow.
Investment thesis
Demand appears to be durably growing
We note that the company has steadily reduced the spending on sales and marketing and expects it to reduce it a bit more.
PagerDuty Q4 2024 Earnings Presentation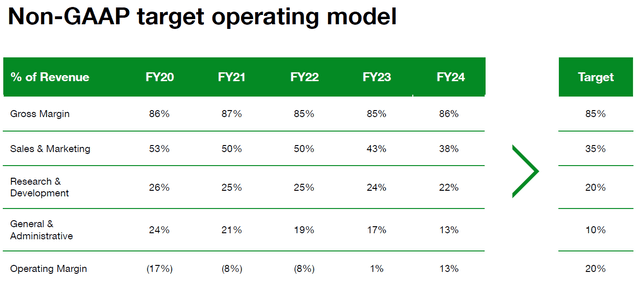
PagerDuty Q4 2024 Earnings Presentation
So, one of the shifts we saw in the macro was this move away from bottoms-up buying through the developer community to a top-down, more centralized, procurement-led purchasing process. And we had to enable the salesforce to manage that effectively.
…But what we’ve seen stabilized towards the back half of the year is more confidence around the budget envelope that our enterprise customers have to work within, and more of a willingness to engage with us in multi-year, multiproduct deals.
Source: PagerDuty Q4 2024 Earnings Call Transcript on Seeking Alpha
While the company’s product offering was always well regarded, in the post COVID environment a lot of the technology buying decisions (especially for highly technical products) were relegated to the actual consumers of the technology. While it was the fancy thing to do when money was cheap, as business sense began to prevail the decision making started getting consolidated. The top-down approach has turned out to be less expensive and the company is generating more bang for the same buck.
In addition to the tailwind from the change in buying dynamics, PagerDuty’s demand also seems to be a lot more intrinsic.
It was definitely driven by an improvement in cross-selling and upselling. So, I think we mentioned earlier that now 62% of our ARR comes from customers with two or more products. That’s a 4 percentage point improvement over the previous quarter. And I see that as early momentum.
when we look at the net new ARR within quarter, we’re seeing a much larger contribution coming from products outside of Incident Management to the extent that now we’re seeing this dynamic as customers adopt the operations cloud where the Incident Management portion is smaller than the portion that’s coming from the AIOps, Process Automation or CSR space
Source: PagerDuty Q4 2024 Earnings Call Transcript on Seeking Alpha
As customers look to reduce costs by consolidating point solutions into a single platform, PagerDuty is increasingly benefitting from its market leading position.
PagerDuty Q4 2024 Earnings Presentation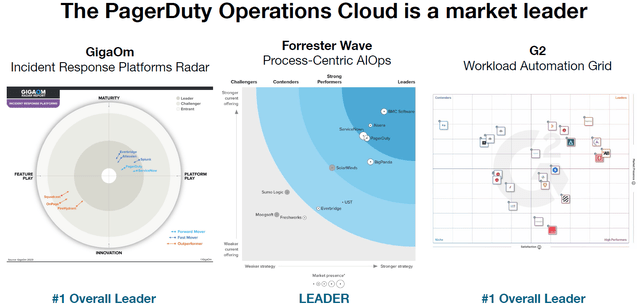
The growing demand is also evident in the growing pipeline, which is further substantiated by the growth in billings, revenue, and deferred revenue.
we have pipeline that goes out much further than we had historically. Instead of just the next quarter, we’re looking two, three, four quarters out now.
Source: PagerDuty Q4 2024 Earnings Call Transcript on Seeking Alpha
10K – 2024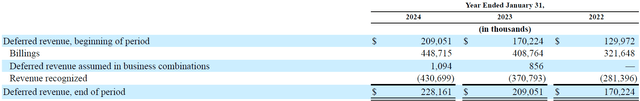
We think PagerDuty’s strategy of selling to existing customers, inevitably means referrals and reduced sales cost (additional revenue from the same client should be minimal sales cost and with a warm connect through referrals, sales cost should also be much lower than what it is for cold outreach). Furthermore, as PagerDuty’s core client ecosystem grows, the ability to cross-sell increases. Also, cold leads that convert to clients also get an ecosystem to hang their hat on.
Differentiated position in real time operations management
Many of PagerDuty’s competitors provide workflow (or ticketing) systems that require a string of approvals etc on a longer timeline to resolve lower criticality problems. Versus these, PagerDuty’s offerings cater to incidents that have a much shorter timeframe of response (and are much higher value in nature). The rise of large language models (or LLMs) and other artificial intelligence driven solutions has given rise to the need for automated workflows – speed of incident management must keep up with the speed of the environment in which such incidents are occurring.
The other thing that has helped the company are belt tightening initiatives.
And at the same time, the market has become much more open to automation than maybe they were a year ago when they were thinking about protecting jobs. Like, most of the leaders we talk to are looking for ways to take people out of these processes and really try and improve the level of automation.
Source: PagerDuty Q4 2024 Earnings Call Transcript on Seeking Alpha
And the key trend here is that technology is now seen as a value driver and not just a cost reduction mechanism. This is possibly the reason by PagerDuty has been able to sell its solutions to be integrated in the broader workflow automation, which then helps customers to accelerate action.
The stability in gross margins despite growth in client volumes is indicative of sustained demand for the product differentiation that PagerDuty’s products provide to customers.
Financials
Seeking Alpha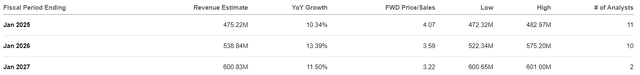
Consensus estimates 10%+ revenue growth for the company for the next three years. PagerDuty’s guidance for F2025 per the company’s Q4 2024 earnings report was:
- Revenue: $470-$478 million (9-11% y/y growth)
- Non-GAAP gross margin: 84%-86%
- Operating margin: 13%-14%
Considering the company’s SAAS revenues, 10%+ growth and 80%+ gross margins we think PagerDuty’s valuation should be closer to those of SAAS peers. Per the BVP cloud index, the revenue multiple should be closer to 6x versus the current forward multiple of 4.5x, which implies an upside of 33%.
Risks to our thesis
- Competition: Incident management is a relatively known category and should some of the more established players catch up in the real-time space, PagerDuty may face margin pressure which may impact multiples.
- M&A: Splunk (a similar company), was acquired by Cisco at a P/S of 6.9x. PagerDuty’s size and financial profile can potentially be accretive to a larger security firm. Valuation in this case could be significantly higher than what we estimate.
Conclusion
PagerDuty offers a differentiated proposition in the incident management space by way of its real-time use cases. Growth in edge use cases given rise to newer incident vectors, which previously were not thought of and hence the need to have an immediate response system is much needed. We find the management to be solid and with a growing pipeline, the additional visibility of the company’s high growth margins warrants ownership of the stock.
Credit: Source link