
courtneyk/E+ via Getty Images
Investment summary
My recommendation for Nutanix, Inc. (NASDAQ:NTNX) is a buy rating. Despite the strong 3Q24 results, share prices traded down for reasons that I believe are non-structural. The underlying demand momentum remains strong and can be seen through multiple data points. The large deal won in the quarter was strong evidence that NTNX offers a strong solution, which gives me confidence that it can continue to win deals.
Business Overview
NTNX provides hyperconverged infrastructure solutions to organizations to address the need for storing, moving, and using data across multiple cloud platforms and end-points through its enterprise cloud platform. Segment-wise, NTNX reports product revenue that is ~49% of total revenue and support & other services that are ~51% of total revenue. Subscription is ~93% of total revenue. Geography-wise, ~56% of total revenue comes from the US and the remainder from overseas. NTNX competitive moat is its leading position as the best hyperconverged infrastructure provider in the industry. Its underlying software architecture enables it to disrupt legacy storage solution providers as businesses shift towards a hybrid multicloud architecture to run apps and data.
3Q24 results update
Released on 29th May 2024, NTNX reported 3Q24 revenue of $524.6 million, representing ~17% y/y change. Driving that growth was annual contract value [ACV] billings growth of 20% to $288.9 million. The main cause of the strong growth in both metrics was a large, eight-figure deal with a North American-based Fortune 50 financial services company. Adj gross margins expanded y/y by 250bps to 86.5%, which led to adj EBIT margins sustaining at the mid-teens level (14% in 3Q24). In terms of guidance, management narrowed FY24 revenue guidance to a range of $2.13 billion to $2.14 billion ($2.13 billion implies ~14% growth) vs. the prior guide for $2.12 billion to $2.15 billion, essentially keeping the midpoint unchanged. ACV billing guidance was raised by ~2%, implying ~18% y/y growth at mid-point.
I was puzzled to see NTNX share price tank after this very solid set of 3Q24 results. Looking at the headlines, it seems that the market was disappointed with management FY24 guidance, as it implies a massive deceleration in y/y growth for 4Q24. Whatever the case, this was positive for me because valuation has come down a lot. In my view, NTNX reported a very solid 3Q24 quarter, and there are several data points that suggest very strong demand momentum and future growth potential.
Very strong billings performance
First and foremost, the strength was evident in the 20% y/y ACV billings growth, which landed 700 bps points above management guidance, driven by better than expected renewal performance. I don’t think this massive outperformance is a one-off blip, as the dollar value of the pipeline of opportunities worth more than $1 million in ACV was up 50% y/y for the last three quarters, and the same set of opportunities was up 30% in 3Q24. Clearly, the demand momentum remains strong, especially if one considers that we are in a fairly uncertain macroeconomic environment.
The problem with this magnitude of large ACV deals flowing into NTNX’s P&L is that it drives greater variability in the new and expansion business, and this looks bad on the surface because it makes it seem like NTNX is reporting poor ACV and annual recurring revenue [ARR] performance (due to the timing of closing the deals and the way these deals are structured). Hence, I urge investors to take a step back and view NTNX’s performance over the long term. In my opinion, this situation of variability will get better over time as NTNX expands its pool of large customers, which will give it a larger pool of renewals each year, and this should offset to some extent the variability in the performance of the new and expansion business.
The key highlight for the quarter was really the 8-figure ACV deal with a North American Fortune 50 financial services company. This is a good example of how such new and large ACV deals can impact ACV and ARR performance. It takes a long time (about 2 years for this customer) to close the deal, and naturally a lot of resources are allocated to complete it, which means there are going to be periods with lower ACV/ARR performance. More importantly, it shows that NTNX solutions are showing a good value proposition to organizations, and they have the capacity to convert these large potential deals in the pipeline into actual revenue. Another example cited during the call that suggests NTNX momentum in winning share is the renewal and expansion with a North American-based Fortune 500 consumer packaged goods company (previous split between NTNX and a competitor, but NTNX is now the sole provider).
Partnership with Dell has huge benefits
The next positive highlight is the new relationship with Dell. At the .Next conference, NTNX revealed their plans to release their AHV hypervisor with support for 3-tier architectures that use Dell PowerFlex storage. Arriving in 2025, this product will be the first to allow AHV to be utilized without undergoing a transition to a hyperconverged architecture. This is massive because it removes the need for organizations to upgrade hardware (cost savings), essentially reducing the adoption friction and making it easier for NTNX to convince prospects.
Valuation
Redfox Capital Ideas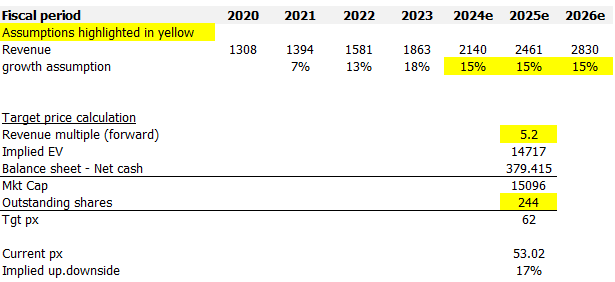
I model NTNX using a forward revenue approach, and using my assumptions, I believe NTNX is worth $62. I expect NTNX to easily grow by 15% for the next few years, using the high end of FY24 revenue guidance as a baseline. I note to readers that my growth assumptions are rather conservative, considering that the industry is expected to grow at a 23% CAGR from 2024 to 2032. The reason for this conservatism is not because I think NTNX will lose share in the near term, but because the macroeconomy remains uncertain (some organizations may continue to delay migrations).
The growth in revenue base should benefit NTNX’s bottom line directly, which can be seen from the strong pro forma EBIT margin expansion since FY22 (from -11.1% in 1Q22 to 14% in 3Q24). I expect this to continue moving as there is still plenty of room to expand, given that pro forma gross margin is trending at high-80s percentage.
The good thing is that even with a conservative growth assumption, the upside is attractive given that valuation has come down a lot. For background information, since the start of the year, NTNX share price has rallied very strongly, driving valuation up to ~7.4x forward revenue (which is near 75% premium vs. the average of other infrastructure software peers like Oracle, Dell, Hewlett Packard Enterprise, Cisco, Lenovo, etc.).
NTNX currently trades at 5.2x forward revenue, and I would argue that NTNX deserves to trade higher than 5.2x given the better relative growth rate against some of the peers. For instance, NTNX is growing in the mid-teens but trades at 5.2x, while Oracle is growing at 10% and trading at 7x. That said, I assumed 5.2x in my model, as I did not want to be too aggressive in assuming an upward rerating.
Bloomberg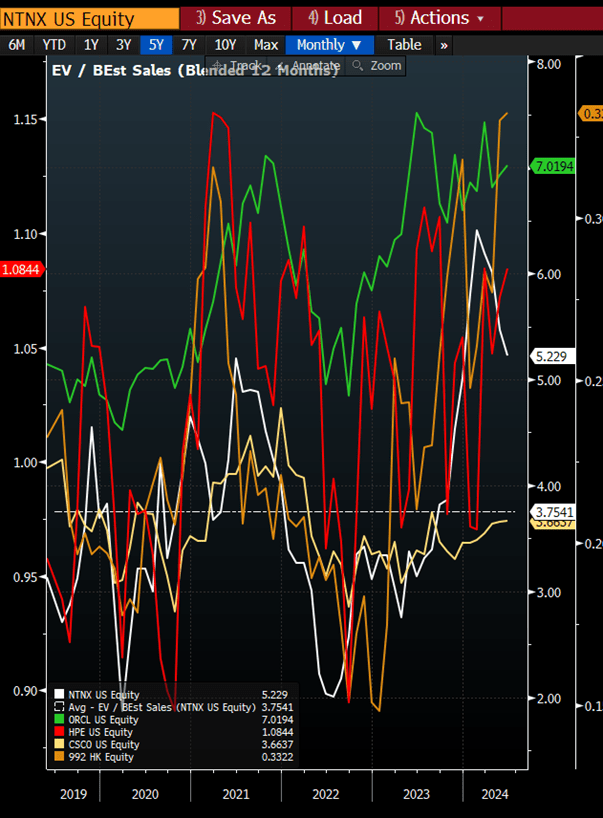
Risk
Moving to NTNX requires a server purchase, which increases the initial investment required to move. The risk is that this continues to be a big friction when NTNX is trying to convert a prospect, thereby limiting the growth potential. The new Dell partnership offers an alternative for organizations. However, for NTNX to really show its value proposition, it is still best for customers to convert to hyperconverged infrastructure. Without this move, the quality of solutions offered by NTNX may not be the best, and this could impact NTNX’s ability to retain customers.
Conclusion
My view for NTNX is a buy rating due to strong demand momentum and future growth potential. Several data points support this, including a large eight-figure deal with a North American Fortune 50 financial services company and a 50% year-over-year increase in the dollar value of the pipeline of opportunities. The new relationship with Dell is another positive factor. While the upfront server purchase cost can be a hurdle, I believe organizations will continue to migrate to hyperconverged infrastructure as the long-term value proposition remains attractive.
Credit: Source link