Luis Alvarez/DigitalVision via Getty Images
I am updating my previous analysis on NovoCure Limited (NASDAQ:NVCR) in light of Q1 2024 earnings which were released pre-market on Thursday, May 2nd.
I previously rated NovoCure a buy for the following reasons:
- Core business was very healthy with growing revenue and a 75% gross margin.
- NovoCure was pursuing growth on multiple fronts including brain, thoracic, and abdominal cancer as well as regional growth in Asia.
- DCF analysis on the core business excluding R&D and growth initiatives in SG&A suggested nearly 100% upside.
Since my previous analysis, the stock has returned more than 19% while the S&P 500 has yielded more than 12%.
NVCR Price Trend (Seeking Alpha)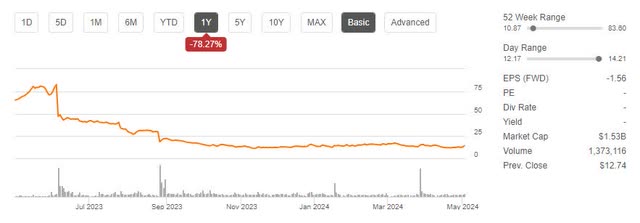
Q1 earnings exceeded my expectations with NovoCure growing revenue and reducing costs much faster than expected. Tailwinds for the business are getting stronger as new market data suggests faster growth for specialty oncology treatments. And the core business is getting stronger as growth accelerates. NovoCure is significantly undervalued on the core business alone, with new treatments representing additional upside beyond that. With this in mind, I maintain my buy rating at a price target of $22.10, noting additional upside potential as new therapies receive approval.
Q1 Earnings Recap
NovoCure reported EPS of -$0.36 beating consensus by $0.06 and revenue of $138.5 million beating consensus by $7.06 million.
NVCR Earnings Summary (Seeking Alpha)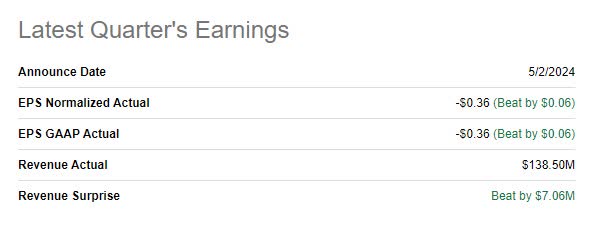
While NovoCure doesn’t provide guidance, this quarterly performance was ahead of my expectations driven by much stronger revenue growth (13% versus my expectation of 4%) and SG&A cost improvements partially offset by a slight decline in gross margin. Note that in the earnings call management attributed R&D decreases more to timing of clinical tests but the G&A reductions are expected to continue.
Q1 2024 Financials (NVCR Investor Relations)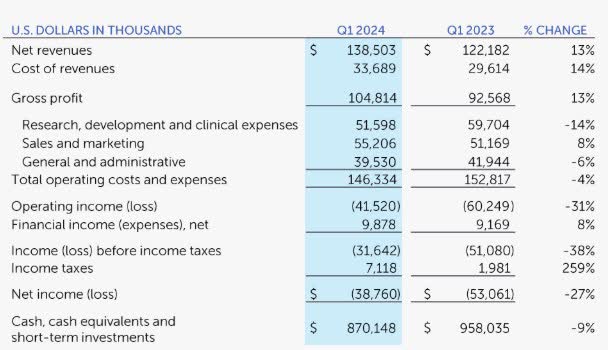
From an R&D standpoint, new treatments for Brain Metastasis met its primary endpoint and treatments for Glioblastoma, lung cancer, and pancreatic cancer are progressing through phase 3 trials.
Metis Phase 3 Results (NVCR Investor Relations)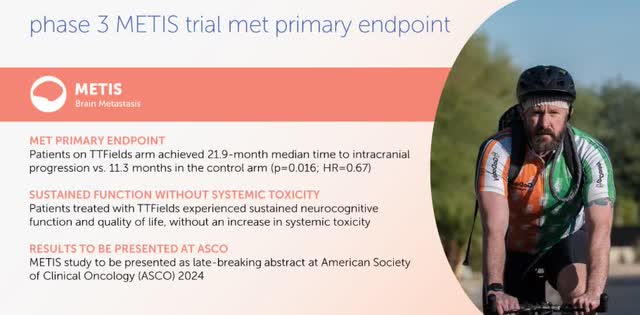
Market Tailwinds Getting Stronger
Growth expectations for specialty treatments, especially around oncology, are growing. The market is now expected to grow at a CAGR of more than 36% through 2033, with oncology representing 42% of the market at present.
Specialty Medical CAGR (Market.US)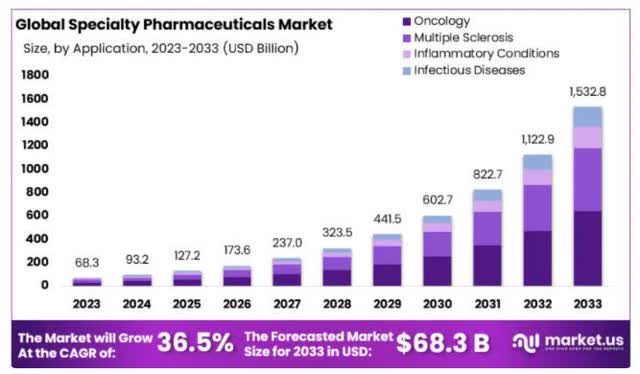
With a current growth rate in the low double digits, this gives NovoCure plenty of room to run, both geographically and in product line, even if it doesn’t keep up with the overall market.
Core Business Continues To Succeed
NovoCure’s core business is growing at an accelerated pace with revenue growing 13% and active patients growing 11%.
Q1 Key Stats (NVCR Investor Relations)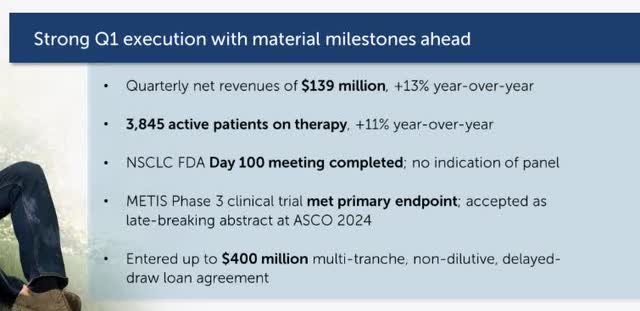
NovoCure continues to pursue growth geographically, and the strategy is playing out well. The majority of growth came from international markets outside their core operation which is a great base as new treatments come online.
Revenue By Region (NovoCure Investor Relations)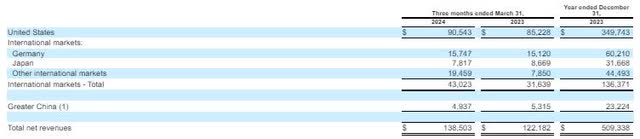
Several new treatments also have the potential to come online late in 2024 and throughout 2025.
Clinical Trial Pipeline (NVCR Investor Relations)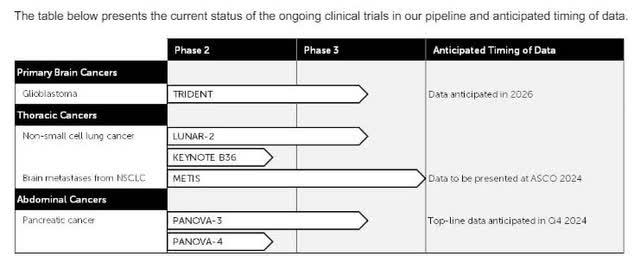
Valuation
I updated my ongoing DCF analysis looking at the value of the core business, excluding unapproved treatments and the R&D pipeline. I made the following key assumptions:
- 10% near-term revenue growth rate based on current trends.
- Current gross margin maintained.
- 75% of R&D costs excluded.
- 75% of new G&A to support expansion and new treatments excluded.
- 10% discount rate as capital needs would be reduced and company would be cash flow positive reducing risk.
- 3% long-run growth rate is a conservative assumption since I am assuming no new treatments.
This DCF analysis yields a price target of $22.10, 46% upside from today’s pricing.
NVCR DCF (Data: SA; Analysis: Mike Dion)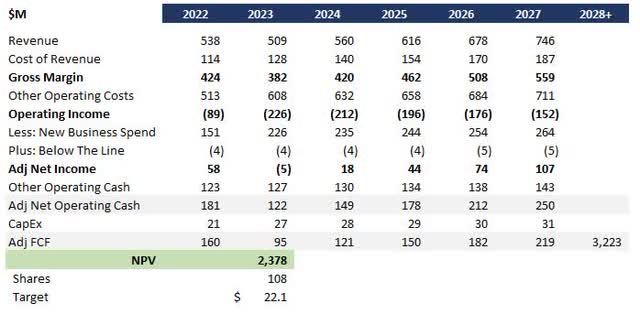
Wall Street analysts land in a similar range with a price target of $25.57, a 71% upside from today’s pricing.
Wall Street Rating (Seeking Alpha)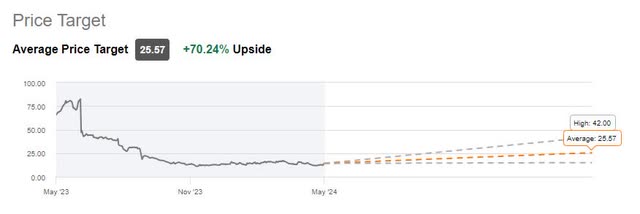
The quant rating continues to suggest a hold. However, this is driven by momentum in the share price which fell sharply early in 2023. The remaining metrics are favorable, including valuation metrics.
NVCR Quant Rating (Seeking Alpha)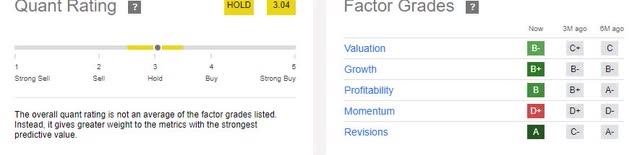
Downside Risk
Downside risks for new treatment approval are largely mitigated as I am suggesting the core business can sustain a higher price target. With that in mind, downside risks are tied to the core business. The primary risk is execution and cash flow risk as my scenario would require the business to ramp down R&D sufficiently with enough cash runway to rebuild the balance sheet.
The secondary risk would be an existing trial losing its approval, reducing future revenue potential.
Verdict
NovoCure’s existing core business is strong enough and on a sufficient growth trajectory to provide upside even if no new treatments are approved. In addition, there is upside potential from both new treatments as well as market forecasts suggesting more rapid growth in the oncology segment. With a DCF analysis on the core business excluding new treatments suggesting a price target of $22.10 and risks largely mitigated by multiple growth avenues, I maintain my buy rating on NovoCure.
This article represents my personal opinion and does not constitute financial, legal, or tax advice. Please consult a licensed advisor prior to making investment decisions.
Credit: Source link