
Kevin Hagen
News Corporation (NASDAQ:NWS) (NASDAQ:NWSA) has made notable strides in the media sector, marked by its diverse portfolio that effectively merges traditional media channels with modern digital advertising platforms. The company’s commitment to product innovation and its operations across various geographies significantly enhance its global presence. I believe integrating REA Group’s financial services with digital property search and adding Subscription Video Services via the Foxtel Group is a testament to NWSA’s progressive approach. However, a closer examination of NWSA’s financials indicates certain shifts in its revenue sources and operational strategies. Based on these observations and my valuation model, I infer that the company’s stock might be somewhat overpriced. Consequently, I lean towards a mildly bearish rating, largely due to its valuation compared to its financial metrics.
Business Overview
NWSA’s diversified portfolio underscores its robust approach toward navigating the media landscape. The blend of traditional media outlets with digital advertising realms, notably real estate, exemplifies a strategic pivot towards more digitally inclined revenue streams. The emphasis on product innovation to foster user engagement is a prudent endeavor to retain relevance in a competitive market. In my view, the geographically diverse operations enhance its global outreach yet might pose operational complexities.
The separation from Twenty-First Century Fox Inc. in 2013 was a strategic recalibration, focusing on core competencies. The Wall Street Journal, Dow Jones, and HarperCollins Publishers are key brands. Revenue streams include subscriptions, advertising, real estate listings, and licensing fees. Based in New York, it operates mainly in the U.S., Australia, and the U.K. with a structured fiscal year.
Company’s website.
In my view, the fusion of REA Group’s financial services with digital property search, alongside Move’s Realtor.com, exhibits a visionary approach to encompass a broader consumer base. The inclusion of Subscription Video Services through the Foxtel Group reflects an astute recognition of the growing on-demand entertainment market. As a stalwart in delivering quality news and business information, Dow Jones signifies a grounding element amidst other ventures. Blending traditional media with digital advancements is instrumental in adapting to shifting consumer preferences.
The Dow Jones segment within News Corp adeptly navigates the transitional digital tide, leveraging established brands like WSJ, Barron’s, and MarketWatch to offer a multifaceted financial discourse. The notable 68% mobile engagement on WSJ platforms embodies a pivotal consumer shift towards mobile-centricity. This diversified consumer interaction, from print to digital to live events, underpins a sturdy engagement blueprint and unfolds varied revenue streams like advertising and subscriptions. This positions Dow Jones as a formidable player in the digital realm.
Company’s website in Japan.
The utility of Dow Jones Risk & Compliance, especially in a labyrinthine regulatory environment, can’t be overstated; it serves as a beacon for navigating through compliance requisites. OPIS is another cog in the wheel, providing invaluable data in the energy sector, a volatile and crucial domain in the global economy. The widespread adoption of Factiva, exemplified by its 1.0 million activated users and the daily torrent of news from Dow Jones Newswires, is emblematic of the unquenchable thirst for real-time, global business insights among professionals. In my view, the competitive arena where Dow Jones operates is a crucible, with formidable adversaries like Reuters and S&P Global. Yet, the diverse portfolio of Dow Jones, tailored to meet contemporary demands, holds its ground firmly. This robustness, I believe, is a testament to its adaptive strategies and an unwavering commitment to quality and relevance in information dissemination.
Operating Performance and Segment Analysis
It’s worth noting that digital engagement in Australia, with news.com.au – Australia’s leading news site drawing a monthly unique audience of around 12.9 million. Contrastingly, the U.K. showcases a strong print readership, with The Sun and The Times accounting for a substantial portion of national newspaper sales. Regulatory landscapes, particularly data privacy laws and media regulations, present operational challenges and frameworks. In my opinion, this mix of digital transformation, regulatory adeptness, and geographic diversification delineates a robust business model capable of navigating varying market dynamics across different regions.
Interestingly, the nuanced transitions in NWSA’s financials shed light on operational dynamics. The modest increase in circulation and subscription revenue by $70 million (2022 to 2023) against a $79 million dip in advertising revenue may hint at a shift in revenue streams. The upswing in operating expenses by $84 million and a stark net income fall by $414 million accentuate operational bottlenecks. The contraction in total assets by $187 million and the slide in net cash from operating activities by $360 million underlines a tighter liquidity scenario. I believe these figures evoke a need for a strategic review to bolster operational efficiency and financial robustness.
NWSA’s latest 10-K.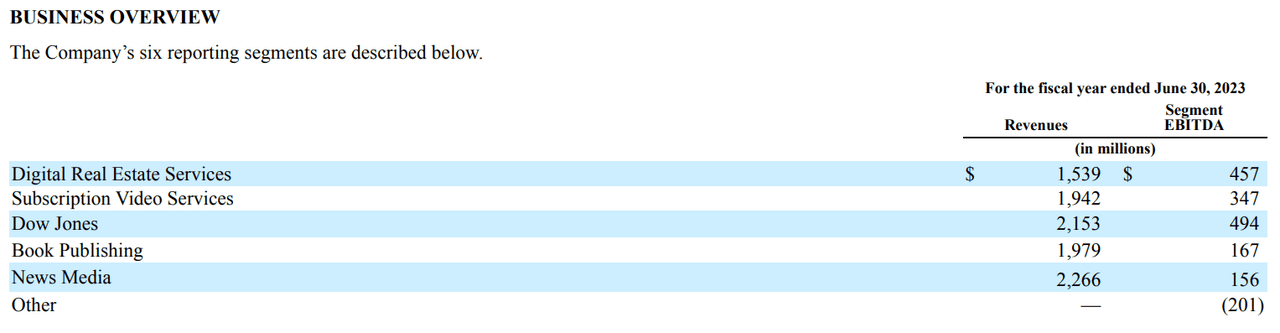
Noteworthy is the significant contribution from Subscription Video Services, Dow Jones, and Book Publishing, generating $477 million, $529 million, and $515 million, respectively. The Dow Jones segment, responsible for $426 million in circulation and subscription revenue, appears to be a pivotal revenue stream alongside Book Publishing, which solely holds the Consumer revenue of $495 million. Diversification is evident with distinct revenue streams across segments, potentially insulating against sector-specific downturns. The figures suggest a robust revenue generation framework. The decline in real estate revenue from $988 million to $896 million over the nine months ended March 31, 2022, to 2023 might indicate market saturation or competitive pressures.
Revenue Pattern and Valuation Analysis
In 2023, NWSA’s revenues experienced a 5% decline compared to the previous year, with significant reductions in areas like advertising, consumer, and real estate. In my view, the absence of the 53rd week in 2023, which affected revenues by approximately $110 million, played a pivotal role in this downturn. The Book Publishing segment faced challenges, primarily from diminished print and digital sales in the U.S. market. Most of this decline should be transitory due to a mix of factors: waning consumer demand, adjustments in Amazon’s inventory, and the impact of foreign currency fluctuations.
Nevertheless, The Dow Jones segment experienced a revenue boost, primarily attributed to the acquisitions of OPIS and CMA. Interestingly, even with stable operating expenses year-over-year, savings in areas like Book Publishing and News Media offset the increased expenses in the Dow Jones segment. In my opinion, this showcases the company’s resilience to financial challenges. I believe the 7% reduction in SG&A expenses in 2023 further emphasizes the company’s proficiency in cost management. This is particularly evident in the Digital Real Estate Services and News Media segments, suggesting a focused and effective operational strategy.
Therefore, if we take a step back, NWSA’s overall financial profile appears relatively stable as a whole, with little to modest growth. The valuation model I’ve employed assumes that the company’s revenues will recover the lost revenue in 2023. Following this recovery, I project a gradual decline in revenue until it aligns with a terminal growth rate of 1.7%. This rate is consistent with the company’s CAGR of 1.7% observed since 2014. Using this historical CAGR as a benchmark is prudent because it provides a realistic and time-tested growth expectation for the company. Subsequently, I’ve incorporated the model’s historical averages for EBIT, D&A, and CAPEX margins. The resulting FCFs were then discounted using the implied CAPM discount rate of 11.2%.
NWSA’s latest 10-K.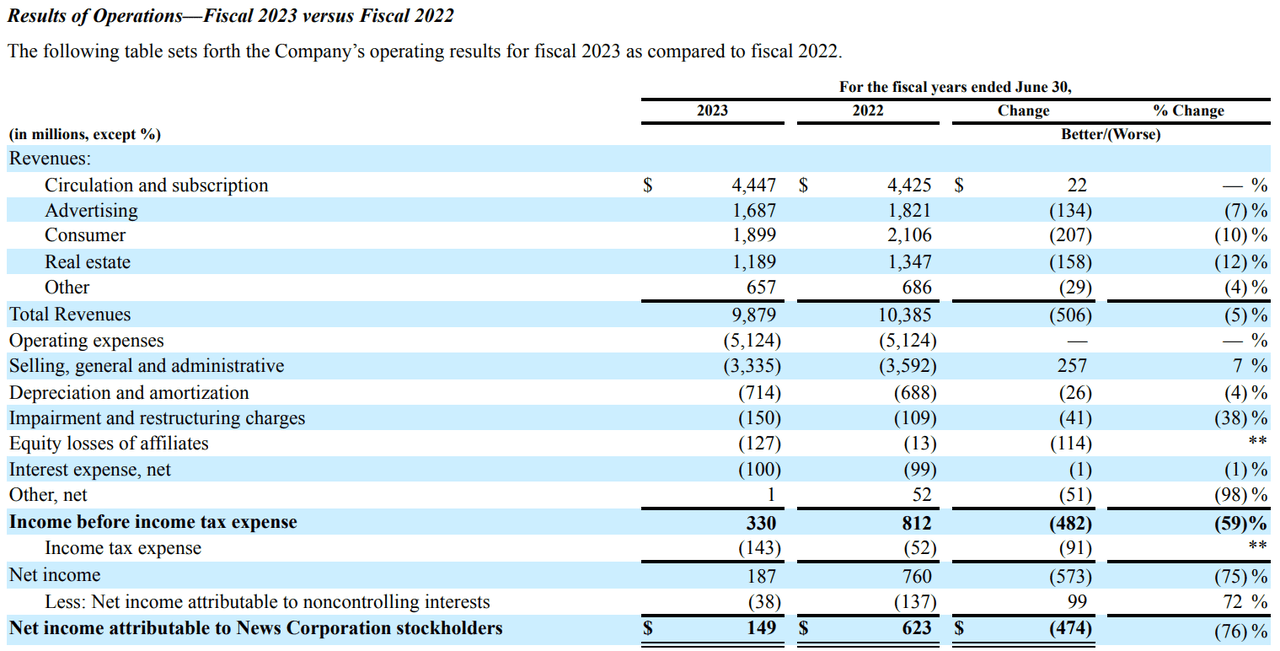
I believe this is a sound approach, as the CAPM discount rate considers the company’s risk relative to the market. Additionally, I’ve applied a perpetuity growth rate of 1.7%, mirroring the long-term growth rate CAGR. Finally, I adjusted for the company’s debt and cash positions following the FCFF DCF methodology. I think this comprehensive approach ensures a balanced and well-informed company valuation.
Author’s elaboration.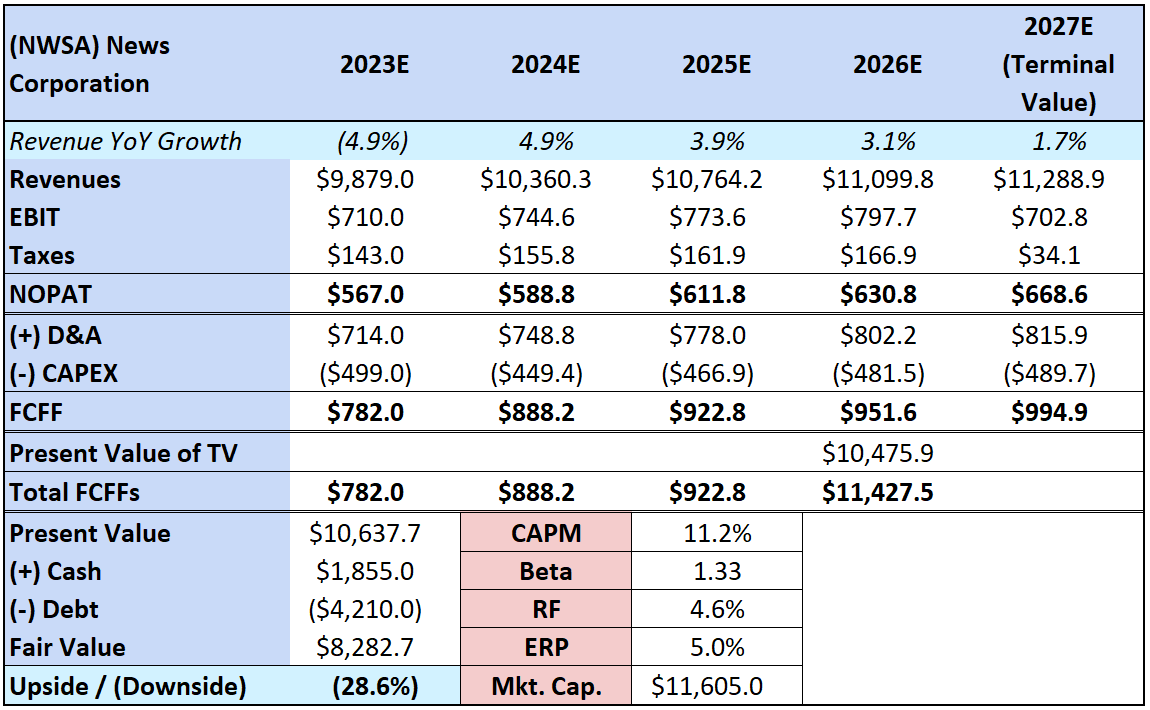
As you can see, my valuation model implies that the company is slightly overvalued, suggesting a 28.6% potential downside from current levels. This, coupled with the company’s relatively sluggish topline growth and secular tailwinds in print media, led me to assign a bearish rating on the stock. However, it’s worth noting that my stance is mostly due to the company’s relatively expensive valuation compared to its fundamentals. Otherwise, I’d give it a neutral rating.
Conclusion
News Corporation demonstrates commendable adaptability in the media sector, evident through its diversified portfolio that seamlessly integrates traditional media with contemporary digital platforms. In my view, the company’s commitment to product innovation and its emphasis on global expansion indicate a forward-looking strategy. I believe that the decision to merge REA Group’s capabilities with digital property searches and the inclusion of Subscription Video Services through the Foxtel Group underscores NWSA’s progressive approach. However, my valuation model suggests it’s overvalued by 28.6%. This leads me to think that the stock has a slightly bearish potential, especially when its current market valuation is juxtaposed with its core financial metrics.
Credit: Source link