
Thicha studio/iStock via Getty Images
Dear readers,
NewLake Capital Partners (OTCQX:NLCP) is a high-yield cannabis REIT with operations in limited-license states in the U.S. The REIT is relatively small with a market cap of $340 Million, trades over-the-counter (OTC), and holds 14 cultivation facilities and 17 dispensaries leased to a total of 13 tenants.
NLCP IR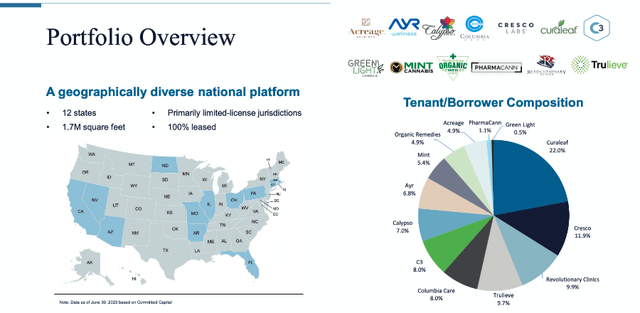
I’ve covered the stock multiple times, most recently here, with my last BUY rating at $13.20 per share. My thesis was based on three things: (1) a high double-digit (12%) dividend yield, (2) significant potential upside of 30%+ driven by declining yields and several positive legislative catalysts, and (3) a limited downside thanks to a low valuation below the replacement costs of properties. Since my last call, the stock has outperformed with an RoR of 23% compared to an RoR of the S&P 500 (SPX) of 13%.
My last article was published in mid-November, post Q3 2023 earnings. At that point in time, NewLake was coming out of several consecutive quarters of tenant delinquencies. Since then, the company has reported their Q4 2023 results. And I’m delighted to say that after many quarters of struggles, things appear to have stabilized. Moreover, many of the bullish catalysts discussed last time are still very much ahead of us, making the stock attractive.
Recent Results
NewLake’s performance has gradually improved over the course of 2023, ending with a very good fourth quarter revenue of $13 Million, up 6.4% YoY. The growth was driven by rent escalators and acquisitions and notably came with 100% rent collections in the quarter.
Notably, the $13 Million in revenue included about $1.3 Million of non-recurring revenue related from NLCP’s tenant Revolutionary Clinics, which consisted of a $315 ths. security deposit, $480 ths. in delinquent rents from prior periods and $522 ths. in non-cash revenue from the valuation of warrants received with the forbearance agreement (discussed in my last article).
AFFO for the quarter reached $0.51 per share, up 1 cent YoY.
NLCP IR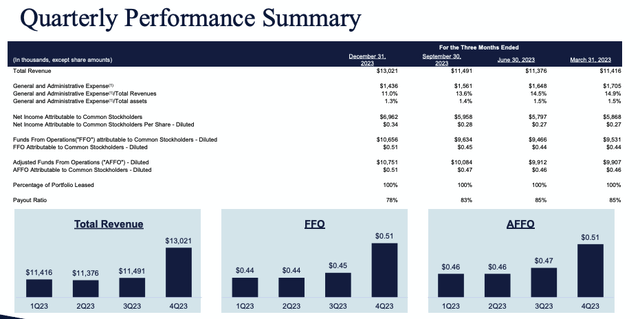
As of today, NewLake has virtually no debt as they only have $1 Million outstanding on their revolving line of credit ($90 Million limit) and hold a large $25 Million cash position.
Catalysts that could move the price higher
The cannabis industry is still in its early stages, which means that it could grow substantially going forward. In fact, it is estimated that sales will grow by a CAGR of 10.5% over the next 5 years.
On a consumer level, this growth will be driven by increasing acceptance of cannabis, which is evident from the fact that cannabis sales have accelerated in recent quarters, while beer sales have declined.
NLCP IR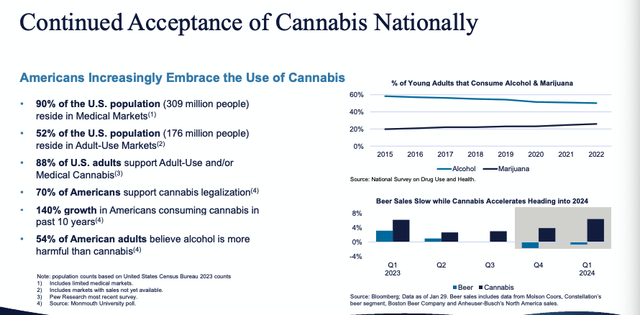
Moreover, on a legislative level, more and more states are taking steps towards making cannabis legal every year. Recently, Ohio approved recreational cannabis in November and an adult-use program is expected to start later this year. And, on a similar note, just two weeks ago, Virginia approved legislation to implement an adult-use program.
NLCP IR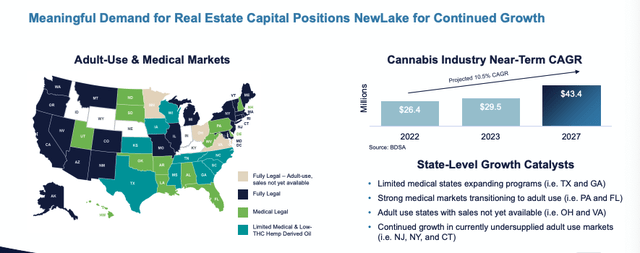
And it’s not just states that are becoming increasingly cannabis friendly. The Federal government has made an effort to reschedule cannabis to a Schedule 3 substance. The final step in the process is a DEA approval. Unfortunately, it seems that the DEA is pushing back and disputing some of the findings reported by the U.S. Health and Human Services. But since President Biden and his administration are very much pushing for this to happen, I remain confident that the proposal will eventually be cleared by the DEA.
This would be a big deal because it would eliminate Section 280E taxation, which weighs heavily on cannabis operators. The elimination of the tax would significantly improve the credit profile of cannabis operators (NewLake’s tenants) and improve their cash flows. NewLake’s management estimates that operators would save about 20% of annual gross profits or an aggregate of $400 Million annually, which would be positive for NewLake as their landlord.
I expect that the final approval will serve as a major bullish catalyst.
NewLake IR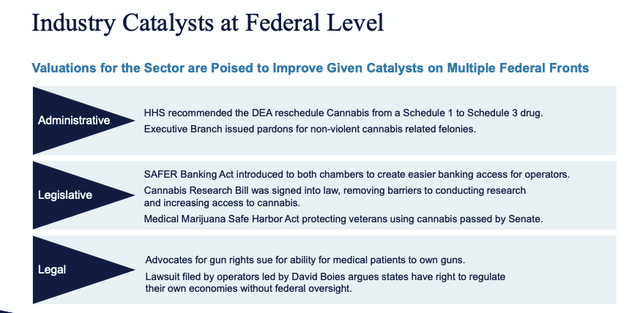
Is NewLake still a BUY?
NewLake’s operations have no doubt stabilized, especially with regard to their delinquent tenants. As a result, the board has declared an increased dividend for Q1 2024 of $0.41 per share, up 2.5% compared to last quarter. The forward dividend yield now stands just above 10% with a comfortable payout ratio of 78%, below the bottom end of management’s target of 80-90%. Moreover, they have continued with an aggressive share buyback program, buying back $12 Million worth of their stock at a very accretive level of $13 per share (vs a price today of $16.30).
Today, NewLake is clearly not as attractive as it was several months ago, but I believe that there’s still upside to be had from today’s level of 8.8x FFO, especially as the REIT is cheap relative to its biggest competitor – Innovative Industrial Properties (IIPR).
NLCP IR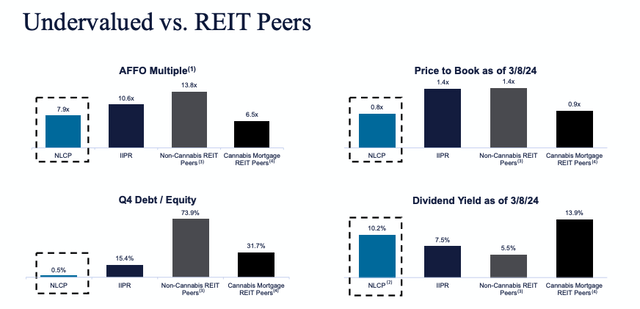
The stock trades at an implied cap rate of 11.7%. Such a high cap rate translates into a massive 7.5% spread to 10-year treasuries. While NLCP is somewhat unproven and small, given the fact the company has no debt and its tenants have very decent coverage of 3.7x for cultivation facilities and 10.3x for dispensaries, I can easily see re-rating down to a spread of 4-5%, especially if cannabis gets rescheduled to a Schedule 3 substance. Such re-rating would result in stock price upside of 30-40%, which is what I continue to see as possible.
NLCP IR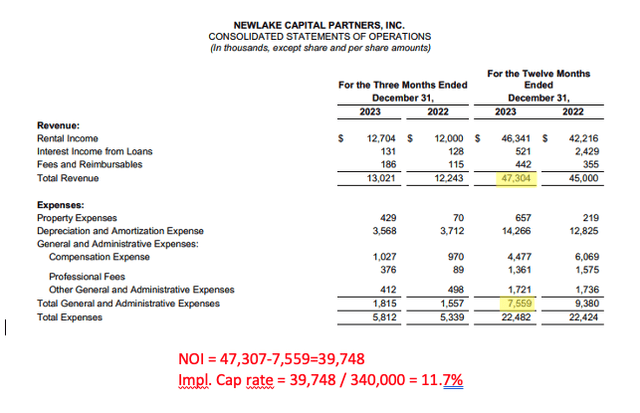
I see few things that could result in material downside, apart from a further rise in interest rates and yields which would pressure valuations and apart from a (hard to imagine) sharp drop in demand for cannabis which would hurt operators. As a result, I’m confident that NewLake deserves a BUY rating here at $16.30 per share with a price target of $22 per share.
Editor’s Note: This article discusses one or more securities that do not trade on a major U.S. exchange. Please be aware of the risks associated with these stocks.
Credit: Source link