
WANAN YOSSINGKUM/iStock via Getty Images
By Catherine Stienstra, Head of Municipal Bond Investments; Paul F. Fox, CFA, Senior Portfolio Manager
Waiting for rates to fall could mean missing out on compelling total return opportunities.
With the Federal Reserve appearing to be done with its tightening cycle, and with rates stabilizing at still attractively high levels, municipal bonds are positioned to deliver compelling returns.
We saw an early example of what that could look like in the last two months of 2023 when interest rates dropped in anticipation of an end to the Fed’s hiking cycle, and bonds rallied. Will this momentum continue?
While some valuation metrics within the muni space (e.g., the ratio of municipal to U.S. Treasury yields) may not appear attractive relative to history, we believe this is due to technical factors – specifically high investor demand.
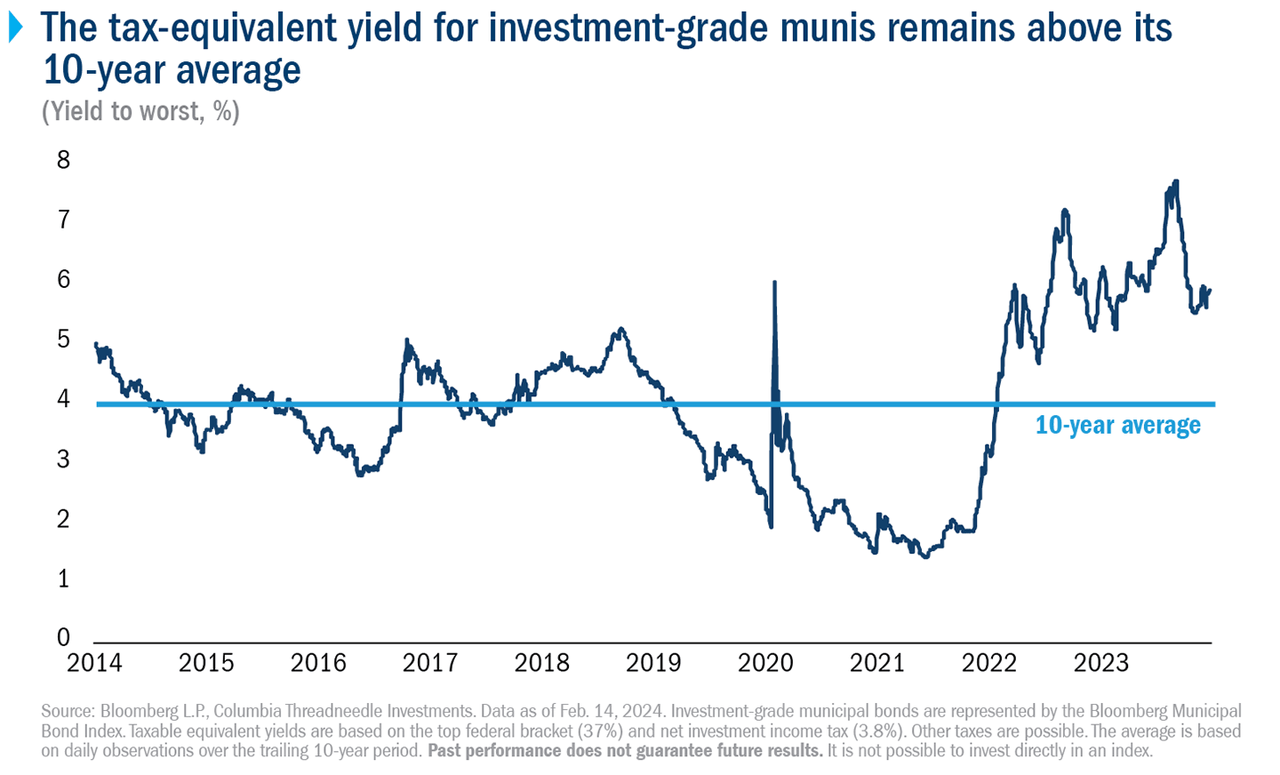
On a tax-equivalent basis, we think the current environment represents an opportunity to lock in historically attractive yield levels before the Fed starts to cut rates.
For investors comfortable with going out on the risk and duration spectrum, intermediate bonds can offer attractive value while maintaining a cushion for potential interest rate volatility.
Going a little further out, longer duration bonds have greater total return potential, given the additional income.
A resilient economy is supportive of revenue sectors
The stronger-than-expected economy, buoyed by the resilient U.S. consumer, is supportive specifically of sectors that initially struggled post-COVID, such as airports, tolls, hospitals and continuing care retirement centers (CCRCs), but that are now showing signs of improvement:
-
Airports. Even though the post-pandemic surge in passenger growth rates has somewhat moderated, record-setting airport volumes echo the strength of U.S. consumer balance sheets and the U.S. economy as a whole.
-
Tolls. Traditional toll roads have rebounded to pre-COVID levels, exhibiting strength and stability with healthy balance sheets that we expect will be maintained throughout the economic cycle.
-
Hospitals. The outlook for the sector has been upgraded to stable after almost four negative years, reflecting a return to profitable operations, albeit at much lower levels relative to pre-COVID.
-
CCRCs. Demand for CCRCs has been fairly robust, especially for independent living. The metrics for the sector including total units occupied and occupancy rates have already surpassed, or are expected to surpass, pre-pandemic levels. Our positive outlook is driven by aging demographics and baby boomers’ interest in lifestyle-oriented senior living.
We believe that in these sectors, intermediate and longer maturity municipal bonds offer an attractive level of income relative to associated risks.
Market conditions are also supportive of high-yield munis – inventory is limited, the probability of a recession is fading, and the rate environment has stabilized.
The bottom line
We are constructive about the municipal bond market this year. A stable rate environment, strong investor demand and a resilient economy set the stage for green shoots continuing to grow.
Disclosures
There are risks associated with fixed-income investments, including credit risk, interest rate risk, and prepayment and extension risk. In general, bond prices rise when interest rates fall and vice versa. This effect is usually more pronounced for longer term securities. Income from tax-exempt municipal bonds or municipal bond funds may be subject to state and local taxes, and a portion of income may be subject to the federal and/or state alternative minimum tax for certain investors. Federal and state income tax rules will apply to any capital gains.
Additional Disclosure
Use of products, materials and services available through Columbia Threadneedle Investments may be subject to approval by your home office.
© 2016-2024 Columbia Management Investment Advisers, LLC. All rights reserved.
Investors should consider the investment objectives, risks, charges, and expenses of Columbia Seligman Premium Technology Growth Fund carefully before investing. To obtain the Fund’s most recent periodic reports and other regulatory filings, contact your financial advisor or download reports here. These reports and other filings can also be found on the Securities and Exchange Commission’s EDGAR Database. You should read these reports and other filings carefully before investing.
With respect to mutual funds, ETFs and Tri-Continental Corporation, investors should consider the investment objectives, risks, charges and expenses of a fund carefully before investing. To learn more about this and other important information about each fund, download a free prospectus. The prospectus should be read carefully before investing.
The views expressed are as of the date given, may change as market or other conditions change and may differ from views expressed by other Columbia Management Investment Advisers, LLC (CMIA) associates or affiliates. Actual investments or investment decisions made by CMIA and its affiliates, whether for its own account or on behalf of clients, may not necessarily reflect the views expressed. This information is not intended to provide investment advice and does not take into consideration individual investor circumstances. Investment decisions should always be made based on an investor’s specific financial needs, objectives, goals, time horizon and risk tolerance. Asset classes described may not be appropriate for all investors. Past performance does not guarantee future results, and no forecast should be considered a guarantee either. Since economic and market conditions change frequently, there can be no assurance that the trends described here will continue or that any forecasts are accurate.
Columbia Funds and Columbia Acorn Funds are distributed by Columbia Management Investment Distributors, Inc., member FINRA. Columbia Funds are managed by Columbia Management Investment Advisers, LLC and Columbia Acorn Funds are managed by Columbia Wanger Asset Management, LLC, a subsidiary of Columbia Management Investment Advisers, LLC. ETFs are distributed by ALPS Distributors, Inc., member FINRA, an unaffiliated entity.
Columbia Threadneedle Investments (Columbia Threadneedle) is the global brand name of the Columbia and Threadneedle group of companies.

Original Post
Editor’s Note: The summary bullets for this article were chosen by Seeking Alpha editors.
Credit: Source link