
porcorex/iStock via Getty Images
The following segment was excerpted from this fund letter.
Monday.com (NASDAQ:MNDY) is a unique business.
They are a leader in the collaborative work management software industry, an industry dedicated to helping knowledge workers organize, manage and collaborate around work.
Smartsheet (SMAR), another Optimist top 10 holding, is also a leader in this market. On the surface Smartsheet and Monday might sound like Coke and Pepsi, which would drive one to ask, “why do you own both?”, but the more one learns about both companies, you come to realize their distinct differences.
Smartsheet is predominately focused on expanding their relationships with existing enterprise customers in project management, whereas Monday views themselves as an app building platform where project management was the first of many applications. Smartsheet typically wins on being able to handle enterprise complexity, whereas Monday wins on ease of use.
In the last few years Monday has broadened their product offering launching Sales CRM, Monday Dev, managing software development workflows, and then late last year they announced a planned entrance into the service management market.
Because the markets both companies are competing in are large, underpenetrated, or in some cases distinctly different, we believe both companies long term growth and success are not mutually exclusive.
The Monday.com founders are exceptional.
Left: Founder and Co-CEO Roy Mann, Right: Founder and Co-CEO Eran Zinman (Source: Calcalistech.com/ctech/articles/0,7340,L-3909641,00.html)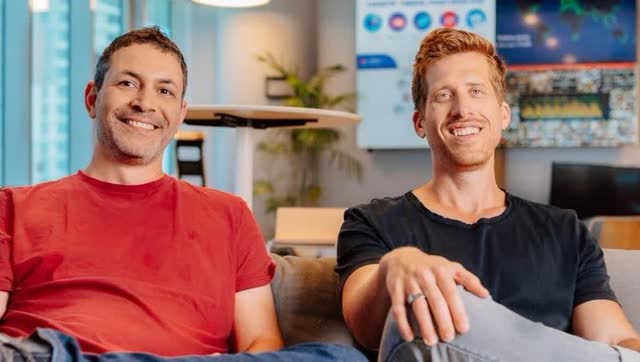
From the initial product launch in 2014 to today, co-founders and co-CEO’s, Roy Mann and Eran Zinman, have done an exceptional job efficiently allocating capital to maximize shareholder value.
Before going public they raised $234 million of which ~$120 million was invested in the business. In 2023 Monday generated ~$165 million in free cash flow excluding interest income.
The above results are an exceptional return on invested capital and has driven Roy and Eran’s combined equity (~15% of the company) to be worth ~$1.9 billion.
The growth runway is large.
Though the founders have already built an incredible business, we believe we are still in the early innings of the Monday.com growth story.
Currently there are over 1 billion knowledge workers globally of which less than 50 million use a collaborative work management solution like Monday.com.
Spreadsheets, word documents, and email remain the tools the vast majority use to manage work. This presents an enormous growth opportunity for the collaborative work management software category.
On top of the enormous collaborative work management opportunity, Monday also addresses the CRM space with their sales and soon to launch service product which together add 10’s of billions of addressable opportunity.
The unit economics are attractive.
Monday breaks even on their customer acquisition spend (sales and marketing expense) in under 2 years and, more importantly, the cohort of customers they acquire, in aggregate, spend more money with Monday every year thereafter.
For example, if Monday spends $10 in sales and marketing to acquire customers, in year 1 they’ll make ~$5 of incremental contribution profit, in year 2 they’ll make $6, year 3 they’ll make $7, and continue to grow thereafter.
Below is a cohort graph demonstrating how Monday’s annual recurring revenue from customers acquired in each period continue to grow over time.
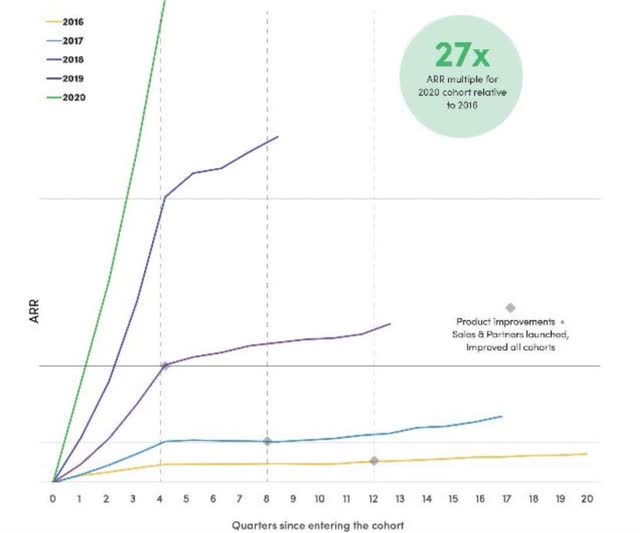
Monday’s attractive unit economics are further demonstrated by their nearly 30% free cash flow margins while sustaining 30%+ revenue growth.
Source: Monday.com Q1 2024 Investor Presentation Source: Monday.com Q1 2024 Investor Presentation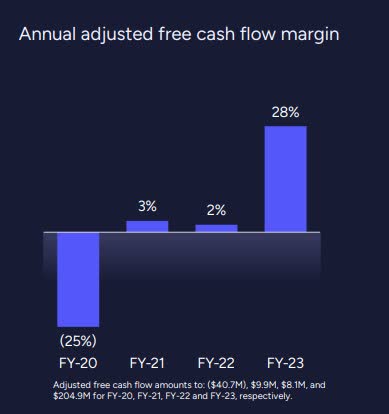
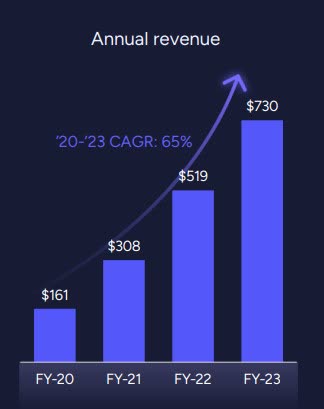
As the company matures and revenue growth slows to sub 20%, free cash flow margins should march past 40%, making Monday one of the highest margin, publicly listed software companies in the world. We believe Monday is significantly undervalued.
Based on our estimates, Monday.com is trading at ~23x 2025 free cash flow, which in our view, is a highly attractive valuation for a business growing revenue 30%+ while continuing to have material future margin expansion potential.
Our 5-year price target is $1,180, (a 5-year internal rate of return of ~40%) driven by revenue and free cash flow per share growth of 35%/37% and a target multiple of 40x EV/FCF.
Overall, Monday.com’s exceptional management, strong growth runway, robust unit economics, and attractive valuation make us optimistic about our investment in the company.
|
Footnotes *Rates of return are for Class E lead series net of all fees and expenses for Optimist Fund to illustrate the historical performance of our investment strategy. **The Benchmark has a 50% weighting in the MSCI World Growth Index and a 50% weighting in the Russell Midcap Growth Index. The Benchmark is provided for information only and comparisons to benchmarks and indexes have limitations. Investing in global equities is the primary strategy for Optimist Fund but Optimist Fund does not invest in all or necessarily any of the securities that compose the Benchmark or the market indexes. Reference to the Benchmark and the market indexes does not imply that Optimist Fund will achieve similar returns. ***Fund start date was March 1, 2022. This report is neither an offer to sell nor a solicitation of an offer to buy any securities in any fund managed by us. Any offering is made only pursuant to the relevant offering memorandum together with the relevant subscription agreement, both of which should be read in their entirety. No offer to sell securities will be made prior to receipt of these documents by the offeree, and no offer to purchase securities will be accepted prior to completion of all appropriate documentation. The discussions in this report are not intended to be investment advice to any specific investor. Some of the discussions are based on the best information available to us, publicly or otherwise, but due consideration should be given to the fact that much of it is forward-looking or anticipatory in nature, which is inherently uncertain. Past performance of a fund is no guarantee as to its performance in the future. This report is not an advertisement, and it is not intended for public use or distribution. |
Editor’s Note: The summary bullets for this article were chosen by Seeking Alpha editors.
Credit: Source link