SweetBunFactory
MKS Instruments (NASDAQ:MKSI) put the final touches on FY2023 with the release of the Q4 report on February 7. The year 2023 was a rather tumultuous one for MKSI with a number of setbacks. Among other things, MKSI suffered a GAAP loss of as much as $1.8B or $27.54 a share in FY2023, a reflection of the kind of challenges facing MKSI. However, things are looking up for MKSI and the stock continues to rally. Why will be covered next?
MKSI soars higher after new lows
A previous article from last November rated MKSI a hold even though the stock was in the middle of a rally after noting that while MKSI had made progress in dealing with some of the recent headwinds, there were other headwinds still out there. The industry is still dealing with the effects of a downturn, which has zapped the demand MKSI requires for a number of reasons, including to generate enough income with which MKSI can pay off the rather hefty debt load it took on as the market turned with the acquisition of Atotech.
Source: Thinkorswim app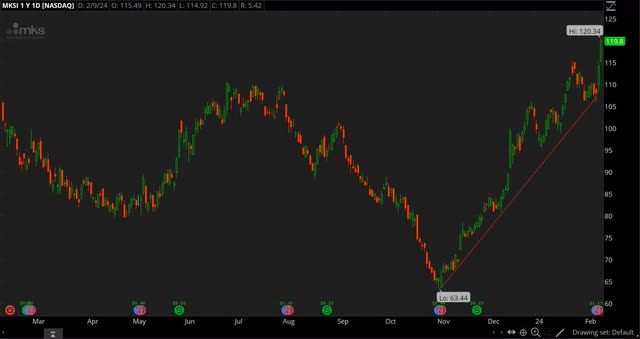
The chart above shows how the stock has rallied for the last three to four months after hitting a multi-year bottom at $63.44 on November 1, which can be considered the culmination of the gradual decline that started in April 2021 when the stock hit an all-time high of $199.44. The stock made it all the way to $115.29 by January 24 before pulling back.
This was likely no coincidence. It’s worth mentioning that the 38.2% Fibonacci retracement of the downtrend, starting with the April 2021 high of $199.44 to the November 2023 low of $63.44, is $115.39, which is ten cents above the January 2024 high of $115.29. In other words, resistance was able to hold the stock at bay, at least temporarily.
However, the pause did not last long. The stock took another stab in February following the Q4 report on the 7th, and this time the stock was able to succeed where it failed the month before. The rally has resumed and if we assume the 38.2% Fibonacci level is in the rearview mirror, then the stock could go higher until the next possible resistance level. This could potentially be the 50% Fibonacci retracement level, which would take the stock all the way to $131.44 or so. The stock closed at $120.34 on February 9.
Why the stock approved of the Q4 report from MKSI
The stock gained a quick 10.9% in the two trading days following the Q4 report. The consensus called for MKSI to report non-GAAP EPS of $0.84 on revenue of $845M, but MKSI reported non-GAAP EPS of $1.17, or $0.33 more than expected, on revenue of $893M. In terms of GAAP, MKSI reported a GAAP loss of $68M, or $1.02 a share.
The difference between GAAP and non-GAAP is mostly due to $70M of amortization of intangible assets and $75M of goodwill and intangible asset impairment, which are included in the former, but not in the latter. Adjusted EBITDA was $218M, which excludes, among other things, $83M of interest expense on debt. The table below shows the numbers for Q4 FY2023.
|
(Unit $1M, except margins, shares and EPS) |
|||||
|
(GAAP) |
Q4 FY2023 |
Q3 FY2023 |
Q4 FY2022 |
QoQ |
YoY |
|
Revenue |
893 |
932 |
1,085 |
(4.19%) |
(17.70%) |
|
Gross margin |
46.0% |
45.7% |
44.7% |
30bps |
130bps |
|
Operating margin |
2.7% |
12.6% |
15.0% |
(990bps) |
(1230bps) |
|
Income (loss) from operations |
24 |
118 |
163 |
(79.66%) |
(85.28%) |
|
Net income (loss) |
(68) |
39 |
54 |
– |
– |
|
EPS |
(1.02) |
0.58 |
0.81 |
– |
– |
|
Weighted-average shares outstanding |
66.9M |
67.1M |
66.7M |
(0.30%) |
0.30% |
|
(Non-GAAP) |
|||||
|
Revenue |
893 |
932 |
1,085 |
(4.19%) |
(17.70%) |
|
Gross margin |
46.0% |
47.1% |
45.9% |
(110bps) |
10bps |
|
Operating margin |
20.3% |
21.8% |
23.6% |
(150bps) |
(330bps) |
|
Income from operations |
182 |
203 |
257 |
(10.35%) |
(29.18%) |
|
Net income |
78 |
98 |
133 |
(20.41%) |
(41.35%) |
|
EPS |
1.17 |
1.46 |
2.00 |
(19.86%) |
(41.50%) |
|
Adjusted EBITDA |
218 |
241 |
297 |
(9.54%) |
(26.60%) |
|
Weighted-average shares outstanding |
67.1M |
67.1M |
66.7M |
– |
0.60% |
Source: MKSI Form 8-K
The table below shows the numbers for all of FY2023. FY2023 revenue increased by 2.1% YoY with a full year of contributions from Atotech. MKSI earned $4.43 a share in terms of non-GAAP and in terms of GAAP, MKSI lost $27.54 a share in FY2023. Most of this loss can be attributed to the GAAP loss of $1,769M or $26.47 in Q2 FY2023, which was due to goodwill and intangible asset impairments totaling $1,827M due to industry conditions. Adjusted EBITDA was $863M, but this excludes interest expense of $339M in FY2023, up from $173M in FY2022. MKSI finished FY2023 with gross debt of $5B on the balance sheet, partially offset by cash and cash equivalents of $875M.
|
(Unit $1M, except margins, shares and EPS) |
|||
|
(GAAP) |
FY2023 |
FY2022 |
YoY |
|
Revenue |
3,622 |
3,547 |
2.11% |
|
Gross margin |
45.3% |
43.6% |
170bps |
|
Operating margin |
(42.9%) |
17.4% |
– |
|
Income from operations |
(1,554) |
617 |
– |
|
Net income |
(1,841) |
333 |
– |
|
EPS |
(27.54) |
5.56 |
– |
|
Weighted-average shares outstanding |
66.8M |
59.9 |
11.52% |
|
(Non-GAAP) |
|||
|
Revenue |
3,622 |
3,547 |
2.11% |
|
Gross margin |
45.7% |
45.1% |
60bps |
|
Operating margin |
19.5% |
24.5% |
(500bps) |
|
Income from operations |
707 |
870 |
(18.74%) |
|
Net income |
297 |
597 |
(50.25%) |
|
EPS |
4.43 |
9.97 |
(55.57%) |
|
Adjusted EBITDA |
863 |
980 |
(11.94%) |
|
Weighted-average shares outstanding |
67.0M |
59.9M |
11.85% |
However, it’s worth mentioning that guidance was below estimates, in contrast to the Q4 numbers which were better than expected. The quarterly numbers have gradually deteriorated and this is expected to continue in the short term. Guidance calls for Q1 FY2024 revenue of $840M, plus or minus $40M, an increase of 5.8% YoY at the midpoint. The forecast sees non-GAAP EPS of $0.72, plus or minus $0.25, an increase of 50.0% YoY at the midpoint. Keep in mind that Q1 FY2023 was negatively affected by the ransomware event, so MKSI is benefiting from favorable comps. The YoY gains should be seen in that light.
|
Q1 FY2024 (guidance) |
Q1 FY2023 |
YoY |
|
|
Revenue |
$800-880M |
$794M |
0.76-10.83% |
|
Adjusted EBITDA |
$160-204M |
$142M |
12.68-43.66% |
|
Non-GAAP EPS |
$0.47-0.97 |
$0.48 |
(2.08%)-102.08% |
Management added some color to the worse-than-expected guidance. MKSI is still dealing with weak demand. From the Q4 earnings call:
As we look to the first quarter of 2024, we expect revenue in our semiconductor market to be down sequentially from our better-than-expected fourth quarter, as overall demand remains muted. While customer inventory levels of some of our product categories have eased, we expect continued drawdown in categories tied to memory spending.”
Source: MKSI earnings call
Furthermore, the outlook is leaning towards a flattish FY2024, with the second half somewhat better than the first half.
As you know, we only guide one quarter out. Visibility is limited as usual. But we certainly read the same things you do, and we’re certainly in constant contact with our customers. And I think our view is consistent with the industry, meaning the first half is kind of consistent with current levels, kind of with our guidance. And then certainly, the industry feels that the second half can be a little better.”
Using these guidelines from MKSI, FY2024 is estimated to be similar to FY2023, with revenue of $3.6B and non-GAAP EPS of $4.43. This would give MKSI a forward non-GAAP P/E ratio of 27x with the stock at $120.34, well above the average for the last five years at 17x and also above most in the sector.
Keep in mind, MKSI’s current long-term financial model calls for revenue of over $5.6B, non-GAAP gross margin of greater than 47% and non-GAAP EPS of more than $13 by FY2027. Assuming MKSI hits these targets and applies a multiple of 17x, then this suggests a stock price of around $221. This is roughly 10% above the all-time high of $199.33 set in April 2021.
Investor takeaways
There are not many companies out there that suffered as many setbacks as MKSI did in the past year. The year got off to a bad start with the ransomware event in early 2023. MKSI was also among those companies to be directly affected by the outbreak of violence in the Middle East in October, and Israel in particular, due to having some production facilities located there. MKSI suffered additional headwinds with the industry downturn proving to be more severe than anticipated, particularly as it related to the NAND memory market.
Demand took a major hit in 2023, which led to impairment charges of close to $1.8B at one point, a major reason why MKSI recorded a GAAP loss of $1.8B or $27.54 a share in FY2023. FY2023 non-GAAP EPS fell by 56% YoY to $4.43 despite a 2% increase in revenue to $3.6B, and that’s with a whole year of contributions from the acquisition of Atotech in the preceding year.
Some of the issues MKSI dealt with in 2023 have faded away, like the ransomware event, but other headwinds like the market slump remain. Q1 guidance was worse than expected with demand remaining sluggish and the FY2024 outlook sees a flat year ahead. There is a chance the second half might see a stronger recovery, which may lead to a better FY2025.
The lack of growth comes at a time when MKSI carries around $5B of debt on the books due to the Atotech acquisition. MKSI paid $339M on interest alone in FY2023. MKSI could really use a pickup in growth because interest payments will keep a lid on earnings for years to come unless MKSI gets around to bringing down debt to more reasonable levels.
The stock actually sold off at first after the Q4 report, but the stock rallied afterward. MKSI appears to have benefited from the stock market rally in recent months that has taken the indices to record territory. As they say, a rising tide lifts all boats. Some are also assuming MKSI lowballed guidance to clear the way for a big beat, just as what happened for the Q4 results.
In doing so, the stock appears to have broken through resistance that had kept the stock at bay as recently as January. Also going higher were forward multiples, especially with earnings expected to stay flat. The stock has now gone higher at a steep angle for the last 3-4 months since hitting a multi-year low in early November. As a result, the stock is now in overbought territory, with an RSI value of over 70.
It is tempting to be long MKSI, especially with how the stock has soared higher in the last several months to almost double in value, but I am going with neutral on MKSI. MKSI looks to be in a good position when the current slump in demand goes away, especially with the addition of Atotech, but it is too early to say the downturn is no more. MKSI’s own outlook sees a flattish year ahead.
The stock might be ahead of itself with the recent rally. Momentum followers might have no problem going with MKSI with the way the stock has performed recently, but others may be more wary of getting in on the stock under current circumstances. An argument can be made that the recent doubling in the stock price is not wholly justified, given that MKSI is not that much better off than it was before the rally. MKSI seems to have benefited from favorable stock market conditions.
Bottom line, there are two ways to look at MKSI. The stock has definitely done very well in recent months, which argues in favor of sticking with long positions. Others may be more wary of placing bets on a stock that has come such a long way in a short amount of time, and the risk that comes along with it. If the stock keeps going up like it has, great, but keep in mind that nothing goes up forever.
Credit: Source link