
• bitcoinBitcoin(BTC)$80,287.00-0.95%
  • ethereumEthereum(ETH)$2,576.14-1.85%
  • tetherTether(USDT)$1.000.00%
  • binancecoinBNB(BNB)$747.73-1.68%
  • rippleXRP(XRP)$1.38-2.13%
  • usd-coinUSDC(USDC)$1.000.00%
  • solanaSolana(SOL)$108.44-2.83%
  • tronTRON(TRX)$0.3415651.16%
  • zcashZcash(ZEC)$1,445.13-7.41%
  • Figure HelocFigure Heloc(FIGR_HELOC)$1.02-1.31%
  • HyperliquidHyperliquid(HYPE)$90.97-2.13%
  • dogecoinDogecoin(DOGE)$0.084860-1.98%
  • moneroMonero(XMR)$525.50-8.14%
  • whitebitWhiteBIT Coin(WBT)$81.70-1.74%
  • USDSUSDS(USDS)$1.000.00%
  • RainRain(RAIN)$0.013391-3.70%
  • chainlinkChainlink(LINK)$11.97-2.61%
  • cardanoCardano(ADA)$0.219129-0.93%
  • leo-tokenLEO Token(LEO)$8.900.16%
  • stellarStellar(XLM)$0.189740-0.97%
  • uniswapUniswap(UNI)$8.70-5.19%
  • bitcoin-cashBitcoin Cash(BCH)$245.860.20%
  • Ethena USDeEthena USDe(USDE)$1.000.00%
  • daiDai(DAI)$1.000.01%
  • nearNEAR Protocol(NEAR)$3.46-5.75%
  • litecoinLitecoin(LTC)$56.730.06%
  • USD1USD1(USD1)$1.00-0.01%
  • avalanche-2Avalanche(AVAX)$9.5912.17%
  • CantonCanton(CC)$0.103824-5.29%
  • the-open-networkGram (prev. Toncoin)(GRAM)$1.382.40%
  • hedera-hashgraphHedera(HBAR)$0.0814724.08%
  • MemeCoreMemeCore(M)$1.5116.48%
  • suiSui(SUI)$0.820.89%
  • Global DollarGlobal Dollar(USDG)$1.000.00%
  • shiba-inuShiba Inu(SHIB)$0.000005-0.22%
  • crypto-com-chainCronos(CRO)$0.058276-1.42%
  • BittensorBittensor(TAO)$251.66-0.26%
  • paypal-usdPayPal USD(PYUSD)$1.00-0.01%
  • tether-goldTether Gold(XAUT)$4,369.77-0.03%
  • Circle USYCCircle USYC(USYC)$1.140.00%
  • okbOKB(OKB)$115.27-0.95%
  • Ripple USDRipple USD(RLUSD)$1.000.00%
  • BlackRock USD Institutional Digital Liquidity FundBlackRock USD Institutional Digital Liquidity Fund(BUIDL)$1.000.00%
  • Ondo US Dollar YieldOndo US Dollar Yield(USDY)$1.15-0.60%
  • aaveAave(AAVE)$136.64-4.05%
  • AsterAster(ASTER)$0.73-2.51%
  • OndoOndo(ONDO)$0.4074583.37%
  • EthenaEthena(ENA)$0.1951778.99%
  • mantleMantle(MNT)$0.59-1.90%
  • pax-goldPAX Gold(PAXG)$4,360.66-0.05%
TradePoint.io
  • Main
  • AI & Technology
  • Stock Charts
  • Market & News
  • Business
  • Finance Tips
  • Trade Tube
  • Blog
  • Shop
No Result
View All Result
TradePoint.io
No Result
View All Result

Miller-Howard Q4 2025 Quarterly Report

February 3, 2026
in Market & News
Reading Time: 29 mins read
A A
Miller-Howard Q4 2025 Quarterly Report
ShareShareShareShareShare

BlackJack3D/iStock via Getty Images

Is There Growth in Your Value?

Let’s start with the part everyone already knows…

OVER THE LAST 10 YEARS, EQUITY MARKETS have witnessed unprecedented outperformance from the companies with the largest market capitalizations. As the biggest companies grew, equity markets reached record levels of concentration with the weight of the top 10 holdings in the S&P 500 Index more than doubling to 41% (from ~19%), and surpassing the Tech Bubble high of ~26% in 1999. The “Magnificent Seven” (Mag 7)* have been the poster children for this dynamic. The Mag 7 accounted for an astounding 38% of the total return of the entire S&P 500 over the last 10 years and 44% over the last five years. Over 10 years, the Mag 7 went from just 11% to 34% of the S&P 500 Index.

What may be more surprising to investors is that style-based allocation alone does not eliminate this market concentration risk nor manage exposure to a narrow set of economic drivers. At the same time, index construction is creating fewer opportunities to diversify portfolios, further complicating matters for investors.

Imagine trimming exposure to Mag 7 holdings (or growth-style in general) and reallocating that capital into a value or income product—only to find some of that money going back into the very names you just trimmed. This dynamic is becoming increasingly common.

Record Market Concentration: Top 10 as a Percent of the S&P 500 Index
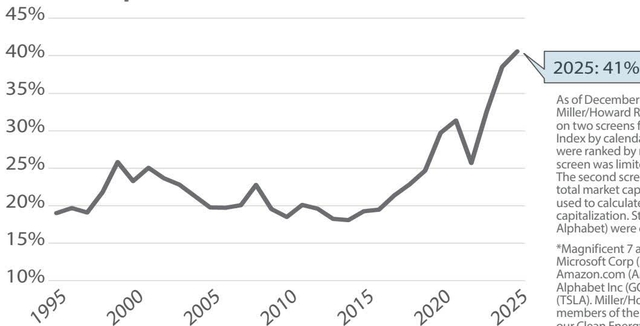
Line chart showing the percentage of the S&P 500 Index held by the top 10 companies from 1995 to 2025. The chart shows a steady increase over time, with a significant jump in the last few years, reaching 41% in 2025.

As of December 31, 2025. Sources: Bloomberg; Miller/Howard Research & Analysis. Based on two screens for members of the S&P 500 Index by calendar year end date. Members were ranked by market capitalization. The first screen was limited to the top 10 by market cap. The second screen was all other members. The total market cap of each selection period was used to calculate top 10 total percent market capitalization. Stocks with multiple classes (e.g., Alphabet (GOOGL)) were combined.

*Magnificent 7 are NVIDIA Corp (NVDA), Microsoft Corp (MSFT), Apple Inc (AAPL), Amazon.com (AMZN), Meta Platforms (META), Alphabet Inc (GOOGL/GOOG), and Tesla Inc (TSLA). Miller/Howard does not hold six of the members of the Magnificent 7; TSLA is held in our Clean Energy portfolio. TSLA entered the S&P 500 Index as part of the Index’s quarterly rebalance in December 2020.

Are Indices Changing?

FTSE Russell periodically reconstitutes its indices. For the Russell 1000 Growth and Value indices, this includes reevaluating the companies in their indices to determine where they lie along the investment style spectrum. Russell uses three metrics (one value-, and two growth-oriented) to calculate a composite value score for each company that reflects how strongly the position displays value and growth characteristics. The constituents are ranked and an algorithm is applied to determine style index membership weights. Since a continuous style-scoring system is used (versus a binary system), holdings can be divided and allocated across both indices. In fact, over 250 holdings were held in both the Growth and Value indices earlier this year.

The 2025 reconstitution (on June 30) marked a key moment as three mega-cap stocks shifted from pure growth to part growth and part value due to lower growth scores and higher value scores: Alphabet (GOOGL/GOOG) shifted to 65% growth/35% value, Amazon (AMZN) shifted to 73% growth/27% value, and Meta Platforms (META) shifted to 82% growth/18% value.

This is not without precedent. In 2022, Google and Meta were categorized as partially value and were added to the value index at weights of ~1.65% and ~0.9%, respectively. However, during the 2025 reconstitution, Google, Amazon, and Meta all became top 10 positions in the Russell 1000 Value due to their outsized market capitalizations, despite only a portion of their total weight being allocated to value . The three positions represented a combined ~5.5% of the Value index. Perhaps even more counter-intuitively, Google, Amazon, and Meta were top 10 holdings in both the Russell 1000 Growth and Russell 1000 Value indices at the reconstitution.

Large Shift in the Top 10 Members of the Russell 1000 Value Index

Ticker Company Name Fwd. P/E 6/30/25 Weight 6/30/24 Weight 6/30/25 Change in Weight Rank 6/30/24 Rank 6/30/25 Change in Rank
BRK.B Berkshire Hathaway (BRK.B) 24x 3.2% 3.2% 0bps 1 1 Same
JPM JPMorgan Chase (JPM) 16x 2.5% 2.9% +40bps 2 2 Same
GOOGL/GOOG Alphabet (Class A)/Alphabet (Class C) 19x * 2.4% (GOOGL 1.3% + GOOG 1.1%) +240bps * 3 New
AMZN Amazon 35x * 2.1% +210bps * 4 New
XOM Exxon Mobil (XOM) 16x 2.2% 1.7% -50bps 3 5 -2
WMT Walmart (WMT) 36x 1.3% 1.4% +10bps 7 6 +1
PG Procter & Gamble (PG) 23x 1.3% 1.3% 0bps 6 7 -1
JNJ Johnson & Johnson (JNJ) 14x 1.5% 1.3% -20bps 5 8 -3
BAC Bank of America (BAC) 13x 1.2% 1.1% -10bps 8 9 -1
META Meta Platforms 28x * 1.0% +100bps * 10 New

As of June 30, 2025. Sources: LSEG; Bloomberg; Miller/Howard Research & Analysis. GOOGL/GOOG share classes are combined. * Google, Amazon, and Meta were not members of the Russell 1000 Value Index as of June 30, 2024. BAC, JNJ, JPM, and XOM were held in Miller/Howard portfolios as of December 31, 2025.

The Russell indices aren’t the only ones encountering these dynamics. S&P style indices are similar in many respects as they don’t force constituents to be 100% growth or value and allow weights to be split based on three growth factors and three value factors. The S&P 500 Index is divided roughly equally into growth and value indices with overlapping positions. S&P reconstitutes its style indices annually in December. At the end of 2024, the S&P 500 Value Index added some of the Mag 7 members with Apple (AAPL), Microsoft (MSFT), and Amazon making up the top three positions and comprising a stratospheric ~18% of the S&P 500 Value Index.

So, what’s the problem?

It’s a fair question. After all, index reconstitution is a mechanical process that is consistent and repeatable—core tenets of the passive process. It also seems fair to conclude that some companies don’t fit neatly into a style category.

If anything, the recent reconstitutions illuminate the fact that investing in passive indices requires an active decision. These indices, while not actively managing their holdings in a traditional sense, are making investment allocations based on their own key metrics. These criteria differ among providers based on what “value” or “growth” mean to the index provider. At the end of the day, we simply disagree with the output of this passive process.

Historically, investors have generally agreed that, stylistically, value is predicated on identifying securities that are undervalued relative to their fundamentals and thus offer a margin of safety, while growth is predicated on identifying securities with above-average growth expectations and emphasizes upside potential. As a result, value stocks have typically exhibited higher dividend yields, lower valuation multiples, and lower growth rates than growth stocks.

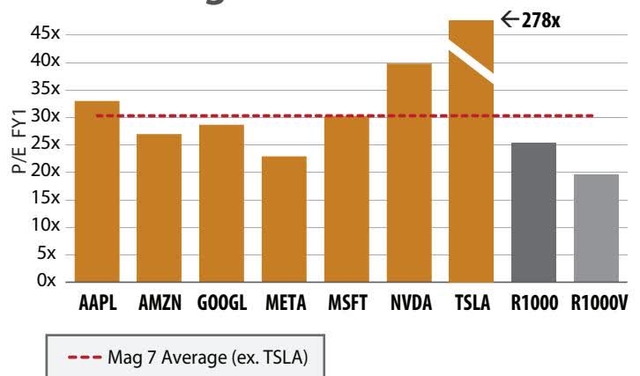
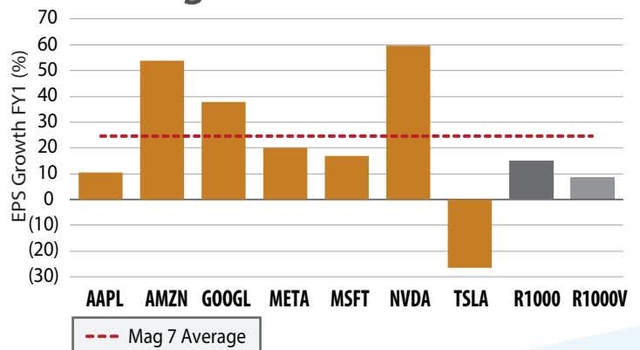
While some of the Mag 7 may have, directionally, become more value-oriented based on year-to-year changes in key metrics, we think it requires some mental gymnastics to classify the Mag 7 as being true value names. At year end, on average, Mag 7 constituents had a lower dividend yield, higher price-to-forward-earnings (P/FE) ratio, and higher growth expectations than value names and the broad market in general. The dividend yield of Mag 7 constituents was ~100 basis points lower than the Russell 1000 and ~175 basis points lower than the Russell 1000 Value. The forward P/E of Mag 7 constituents [even excluding Tesla (TSLA) which was an outlier] was four turns higher than the Russell 1000 and nearly 10 turns higher than the Russell 1000 Value. Finally, the forward earnings-per-share (EPS) growth of the Mag 7 was nearly 10 percentage points higher than the Russell 1000 and nearly 16 percentage points higher than the Russell 1000 Value.

Mag 7 Stocks Still Look Growthy

Lower Dividend Yield
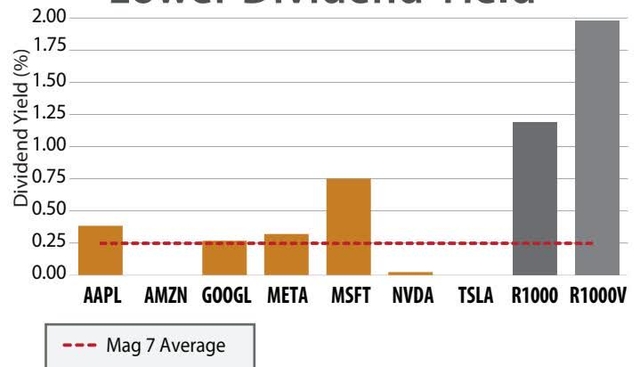
Bar chart showing Dividend Yield (%) for Mag 7 stocks and indices. The y-axis ranges from 0.00 to 2.00. The x-axis lists AAPL, AMZN, GOOGL, META, MSFT, NVDA, TSLA, R1000, and R1000V. A dashed red line indicates the Mag 7 Average at approximately 0.25%.

Higher Valuations

Bar chart showing P/E FY1 for Mag 7 stocks and indices. The y-axis ranges from 0x to 45x. The x-axis lists AAPL, AMZN, GOOGL, META, MSFT, NVDA, TSLA, R1000, and R1000V. A dashed red line indicates the Mag 7 Average (ex. TSLA) at approximately 28x. TSLA is marked with a diagonal line and labeled < 278x.

Higher EPS Growth

Bar chart showing EPS Growth FY1 (%) for Mag 7 stocks and indices. The y-axis ranges from (30) to 70. The x-axis lists AAPL, AMZN, GOOGL, META, MSFT, NVDA, TSLA, R1000, and R1000V. A dashed red line indicates the Mag 7 Average at approximately 22%.

As of December 31, 2025. Sources: Bloomberg; Miller/Howard Research & Analysis. Magnificent 7 are NVIDIA Corp (NVDA), Microsoft Corp (MSFT), Apple Inc (AAPL), Amazon.com (AMZN), Meta Platforms (META), Alphabet Inc (GOOGL/GOOG), and Tesla Inc (TSLA). Miller/Howard does not hold six of the members of the Magnificent 7; TSLA is held in our Clean Energy portfolio. R1000 = Russell 1000 Index. R1000V = Russell 1000 Value Index. FY1 is the expected fiscal year earnings for a company.

Why Should Active Investors Care?

It would be logical for a reader to be thinking, “But I’m an active investor, so this seems like a non-event.” The unfortunate reality is that index construction impacts active management decisions.

Active managers are under constant pressure to beat index performance (and/or provide superior risk-adjusted returns, income streams, etc.). For this reason, portfolio managers are, at the very least, aware of material changes to indices. But this awareness can also influence investment decisions. The inclusion of highflyers like the Mag 7 in value benchmarks clearly adds pressure to maintain performance. At the same time, value index inclusion provides cover to add names that may not have ordinarily been consistent with an investment approach. In aggregate, these dynamics affect portfolio composition and risk.

Looking Under the Hood

Are active managers providing style diversification? We evaluated the holdings of the 25 largest (by AUM) actively-managed large-cap value separately managed accounts as categorized by Morningstar. The exercise suggests that actively-managed value portfolios have materially increased investment in the Mag 7 over the last six months.

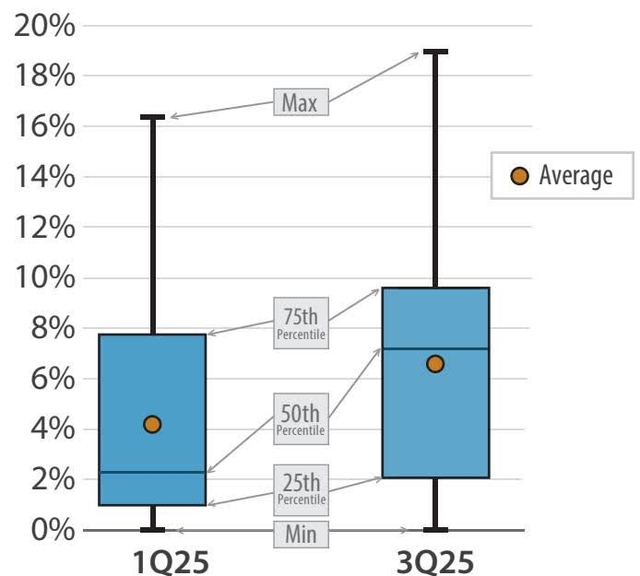
On March 31, 2025, (the quarter-end prior to the Russell reconstitution), 16% of portfolios held zero Mag 7 constituents and 72% held two or fewer. Six months later, by September 30 (one quarter post-Russell reconstitution), only 8% of portfolios held zero Mag 7 constituents and only 52% held two or fewer. In other words, nearly half of the value managers held three or more Mag 7 names . The number of portfolios holding five or more Mag 7 positions also rose to 12% (from 4%). The median portfolio allocation of US Large Cap Value SMAs to the Mag 7 increased from 2.3% to an astonishing 7.2%.

Value Managers Increased Exposure to the Mag 7

More Mag 7 Holdings
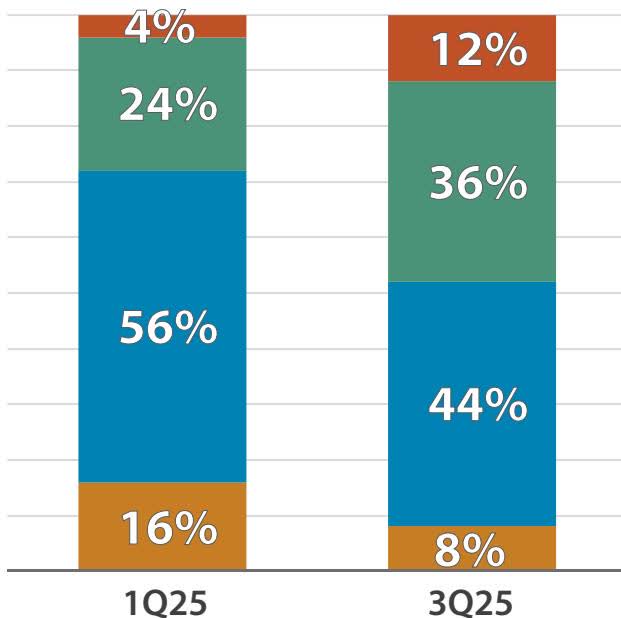
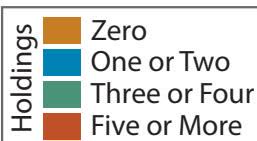
Stacked bar chart showing the distribution of Mag 7 holdings in US Large Cap Value SMAs for 1Q25 and 3Q25. The categories are: Zero (orange), One or Two (blue), Three or Four (green), and Five or More (red).

legend

More Mag 7 Weight

Box plot showing the distribution of Mag 7 weight in US Large Cap Value SMAs for 1Q25 and 3Q25. The y-axis represents weight percentage from 0% to 20%. The plot shows the minimum, 25th percentile, 50th percentile, 75th percentile, and maximum for each quarter, along with the average (orange dot).

As of September 30, 2025. Sources: Morningstar Direct; Miller/Howard Research & Analysis. Based on the Morningstar US Large Cap Value SMA universe, sorted by AUM as of 3Q25 to identify the largest 25 products; those same managers are compared as of 1Q25. The floating bars represent the 25th, 50th, and 75th percentiles. The whiskers represent the maximum and minimum. The orange dot is the average of the managers.

Magnificent 7 are NVIDIA Corp (NVDA), Microsoft Corp (MSFT), Apple Inc (AAPL), Amazon.com (AMZN), Meta Platforms (META), Alphabet Inc (GOOGL/GOOG), and Tesla Inc (TSLA). Miller/Howard does not hold six of the members of the Magnificent 7; TSLA is held in our Clean Energy portfolio.

It was our initial assumption that value managers would have been more likely to add Mag 7 constituents than their income-focused peers. A cursory evaluation shows the facts proved otherwise. Within our analysis, over 25% of the products evaluated had “dividend” or “income” in the product name. These products had an above-average number and above-average weight in the Mag 7.

Our goal is not to disparage competing approaches. Yes, some value managers may have purchased these securities at levels that were consistent with their investment mandate. However, we have concerns that these names compromise style integrity. Ultimately, the high Mag 7 weight within value portfolios creates the illusion of diversification while heightening exposure to market concentration risks. We see this as a unique opportunity for investors to revisit overall portfolio diversification and to ensure each product is meeting its stated philosophy, investment universe, and portfolio objective.

Diversification with High Current Income & Growth of Income

Miller/Howard’s dividend focus is embedded in our corporate DNA and has remained unchanged for over three decades. Our disciplined approach maintains a close adherence to our investible universes across our portfolios, and we do not own the Magnificent 7 in our income-oriented portfolios. We believe this makes for differentiated portfolios that are consistent to their objective for high current income and growth of income compared to many other products in the market. While the investment landscape and products may continue to shift, we strive to continue to provide a truly diversifying income solution for investors.

NOTE: Magnificent 7 are NVIDIA Corp (NVDA), Microsoft Corp (MSFT), Apple Inc (AAPL), Amazon.com (AMZN), Meta Platforms (META), Alphabet Inc (GOOGL/GOOG), and Tesla Inc (TSLA). Miller/Howard does not hold the members of the Magnificent 7 in our income-oriented portfolios; TSLA is held in our Clean Energy portfolio, which does not have an income mandate.


Even putting concentration risk and potential style drift aside, we think the investment case is concerning. It is admittedly easier to invest in what is working. The problem is that it works until it doesn’t. As we identified in our blog Dividends: Valuations and Mathematics, published earlier this year, history suggests that 10-year returnsskew negative when investments are made at elevated P/E multiples.

Assessing the Nuclear Landscape

AFTER A RAPID EXPANSION OF US NUCLEAR power capacity in the 1970s and 1980s, the industry has seen limited new development over the last 30 years. Since 1990, the US nuclear industry has supplied ~20% of total US electricity. This could be changing as the US finds itself on the cusp of a nuclear renaissance. The combination of rising electricity demand, policy support, desire for clean energy solutions, and emerging nuclear technologies is creating the foundation for a long-term expansion of nuclear capacity. While the sector has been gathering momentum, regulatory, economic, and execution risks leave many key questions unresolved.

Rising Electricity Demand

US electricity demand—which has been flat for 20 years due in large part to efficiency gains—is expected to return to growth, driven by data centers, reshoring of manufacturing, and electrification trends. The EIA expects US electricity generation to grow by 1.7% in 2026. Electricity system planning reports suggest growth is expected to continue, and even accelerate, over the next 15 years. North American Electric Reliability Corp’s (NERC) Long-Term Reliability Assessment, published in December 2024, noted, “Electricity peak demand and energy growth forecasts over the 10-year assessment period continue to climb; demand growth is now higher than at any point in the past two decades.” NERC expects peak demand to rise by 15% to 20% over the 10-year period. National Renewable Energy Laboratory’s (NREL) mid-case scenario report suggests generation will need to increase by ~25% over the next 10 years.

As demand marches higher, traditional dispatchable energy is simultaneously facing headwinds to growth. For most of the last two decades, coal-fired power generation has declined as plants have been retired. This trend seems likely to continue. Through 2030, the EIA has identified over 25 GW of coal-fired plant retirements. While the political landscape has become more supportive of coal, we expect support to be focused on extending the life of existing plants rather than undertaking significant new builds. For many years, natural gas-fired generation has been the primary replacement for declining coal-fired generation. Recent electricity demand trends have added yet another growth driver for natural gas generation. However, natural gas turbine manufacturers (OEMs) are currently reporting over three-year lead times until delivery. Expanding development timelines could encourage developers to explore nuclear alternatives, particularly at a time when data centers have been willing to sign agreements at premium prices for nuclear generation.

NREL Mid-Case Generation Forecast
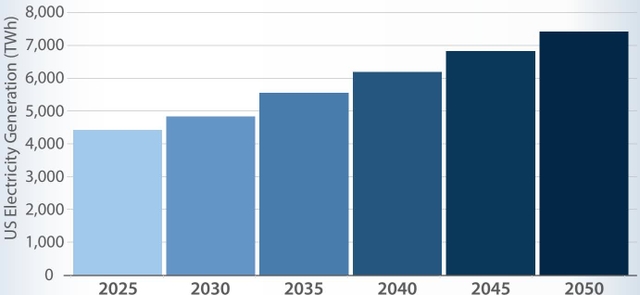
Bar chart showing NREL Mid-Case Generation Forecast for US Electricity Generation (TWh) from 2025 to 2050.

As of December 31, 2025. Sources: National Renewable Energy Laboratory’s (NREL); Miller/Howard Research & Analysis.

Policy and Public Support

There is renewed public support for nuclear development—a shift that was once considered unthinkable in the wake of incidents at Three Mile Island, Chernobyl, and Fukushima. According to a survey by the Pew Research Center, support for nuclear generation has steadily increased over the last 10 years with 59% of adults now favoring the use of more nuclear power. The survey also suggested that a majority of adults favored nuclear development regardless of political affiliation. Nuclear energy can also contribute to a shift away from high-carbon-intensity electricity generation. Pew also states, “Among those who favor more nuclear power, the most common reason why [40% of respondents] is that it is a clean or low-carbon way of producing energy.” To this point, nuclear development has received regulatory and legislative support under the last two administrations.

Initially, support was largely economic as nuclear power plants faced pressure from low electricity prices driven by low natural gas prices and renewable energy. In November 2021, the Infrastructure Investment and Jobs Act (IIJA) was passed. The bill included a nuclear credit program intended to provide financial support to economically stressed plants. The program was similar in many ways to previous state zero-emission credit programs, but it expanded their reach to the federal level. The bill also included funds for the Advanced Reactor Demonstration Program (ARDP) that was designed to help finance development of advanced reactors (e.g., the TerraPower project in Wyoming). The Inflation Reduction Act (IRA), passed in 2022, further altered the economics of nuclear development and put it on level ground with wind and solar. In addition to providing credits for new developments, the bill provided a production tax credit for existing reactors that helped to create a floor and preserve the existing nuclear fleet. The One Big Beautiful Bill Act ultimately accelerated the phase out of tax credits for solar and wind, but nuclear credits were largely maintained.

More recently, emphasis has shifted toward accelerating and streamlining development. The ADVANCE Act, passed in 2024, sought to reduce regulatory friction and speed up licensing. The bill directed the US Nuclear Regulatory Commission (NRC) to provide regulatory guidance on new technologies and on repowering coal sites, to reduce licensing application fees, and to authorize increased staffing. In 2025, a series of executive orders expanded on these nuclear ambitions and targeted a quadrupling of US capacity by 2050 (+300 GW). This incredibly ambitious target implies capacity additions of ~12 GW/year, well above the historic peaks achieved in the 1970s and 1980s. To enable such a rapid expansion, orders focused on expedited approval, faster testing, strengthening the domestic fuel cycle, and military installations.

Majority of Americans Continue to Support More Nuclear Power in the US

% of US adults who favor more nuclear power plants to generate electricity in the country
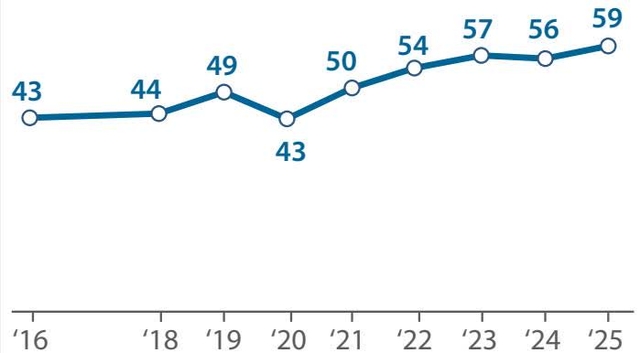
Line graph showing the percentage of US adults who favor more nuclear power plants to generate electricity in the country from 2016 to 2025. The percentage starts at 43% in 2016, rises to 44% in 2018, peaks at 49% in 2019, dips to 43% in 2020, and then steadily increases to 50% in 2021, 54% in 2022, 57% in 2023, 56% in 2024, and 59% in 2025.

Source: Pew Research Center, Survey of US Adults Conducted April 28 – May 4, 2025 . Note: Respondents who selected the response option “oppose” or did not give an answer are not shown.

Support for nuclear generation is beginning to translate into tangible results. After over a decade of decommissioning (US nuclear generating capacity peaked in 2012), nuclear plants are delaying closings and shuttered plants are being restarted. After being closed because of economic pressure, the Palisades Nuclear Plant (MI), Crane Clean Energy Center (PA), and Duane Arnold Energy Center (IA) are all expected to restart before the end of the decade; the Palisades Plant is currently expected to be the first previously retired nuclear plant in the US to return to operating status. While other plants are also being evaluated for restarts, there is a limited opportunity set. These restarts are low hanging fruit in a nuclear acceleration, however long-term growth will be predicated on new builds.
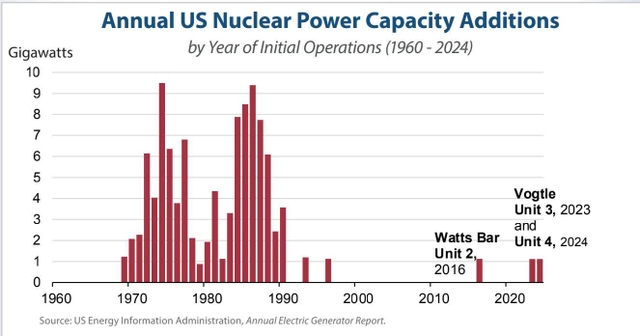
Bar chart showing annual US nuclear power capacity additions in gigawatts from 1960 to 2024. The chart shows a peak in the late 1970s and early 1980s, followed by a decline and then a resurgence in the 2010s with the completion of Vogtle Units 3 and 4, and Watts Bar Unit 2.

Source: US Energy Information Administration, Annual Electric Generator Report .

Small Modular Reactors

The completion of Units 3 & 4 at the Vogtle Nuclear Plant in 2023 and 2024, respectively, accounted for two of the three US nuclear units completed in the last 30 years. The third, the Watts Bar Unit 2, was completed in 2016 after being halted in 1985. The two Vogtle units had a combined nameplate capacity of over 2 GW, making it the largest in the US. Construction at the reactor sites commenced in 2009. After a series of construction delays and cost overruns, the units were completed seven years behind schedule and at a total capital cost of over $30bil—over double the project’s original estimate.

Due in part to the challenges experienced in constructing large scale nuclear reactors, focus is shifting to emerging technologies such as small modular reactors (SMRs, a class of small nuclear reactors). As the name implies, these reactors are modularly constructed and smaller in physical size and capacity. Commercial SMRs have been designed to deliver 5MW to 300MW; many SMRs work in the range of ~75 MW which is enough to power ~60,000 US homes. For context, each of the units at the Vogtle plant generates ~1,100MW. SMRs also utilize passive safety systems which enables them to cool themselves without power or human action.

SMRs provide multiple advantages compared to large-scale reactors. Due to their size and design, SMRs can be installed onto the grid or utilized independently off the grid, and they can be sited on locations that are not suitable for larger nuclear power plants. Siting flexibility took a major step forward when the NRC issued a rule effectively reducing the size of the Emergency Planning Zone (EPZ) for SMRs. This allows SMRs to be built next to data centers or on existing coal plant footprints (utilizing existing electric infrastructure) without the need for emergency planning considerations. Their scale and flexibility also match the needs of data centers. Recent data center announcements have power demands ranging from 50 MW to 2 GW. Given the wide range of potential outcomes, developers could potentially stack the required number of SMRs to service their design. The prefabricated units can be factory-assembled and transported to a location for installation. As a result of the scale and production benefits, SMRs have lower capital costs for developers and accelerated deployments. SMRs are expected to have development timelines of five to seven years (including a ~36-month licensing timeline and 18- to 36-month construction timeline). This compares favorably to the 10+ year time frame to build a traditional reactor.

Interest in SMRs has been accelerating and has culminated in a wide range of transactions. Hyperscalers have been among the most active, signing multiple power purchase agreements for SMR offtake. Utilities and industrial manufacturers have also announced plans to pursue SMR development.

Questions Remain

The most obvious impediment to SMR proliferation is the lack of proof of concept. SMRs are still very much an emerging technology, and regulatory, manufacturing, and installation timelines are still evolving. While there are SMRs operating in Russia and China, no US SMR has achieved commercial operation. Within the US, most of the SMRs under evaluation or development are targeting commercial operation near the end of the decade.

Like their larger peers, SMR developments have not been immune to cost overruns. Cost overruns have plagued early SMR development. The previously mentioned SMRs in Russia and China were completed at over 300% of their original cost estimates. Within the US, NuScale’s Carbon Free Power Project (SMRs) was terminated in 2023 after project costs rose to $9.3 billion from an earlier estimate of $5.3bil; the project’s final estimate of the levelized cost of electricity (LCOE) jumped to $89/MWh from $58/MWh. This is to be expected with a first-of-its-kind development, further demonstrating that the industry is in an early stage of development. Nuclear development in the US will likely be influenced by the cost trajectory of SMRs. The EIA’s Levelized Cost of Energy (LCOE) estimates (including tax credits) for new resources entering service in 2030 put nuclear at the high end of the cost curve at $81.45/MWh.

While LCOE does not capture all factors contributing to investment decisions—system reliability chief among them—it is useful in evaluating trends. A Department of Energy (DOE) study estimated a 2030 LCOE for SMRs and large nuclear reactors of $118/MWh and $104/MWh, respectively (excluding tax credits). By 2050, the report suggests the LCOE for SMRs and large reactors will drop to $74/MWh and $80/MWh, respectively. The change is driven by a reduction in the “overnight capital cost” (a method of comparing capex for power plants) as SMR builders incorporate learnings over time. If SMR construction timelines were to fall to 24 months, from the DOE’s assumption of 55 months, we believe SMR LCOEs would be below $70/MWh and, importantly, competitive with natural-gas combined-cycle turbines.

We view nuclear power generation as an exciting and growing opportunity set within the essential services space. We will continue to assess the risks and opportunities as the industry continues to develop.

Nuclear is at the High End of the Cost Curve – Levelized Cost of Energy by Source
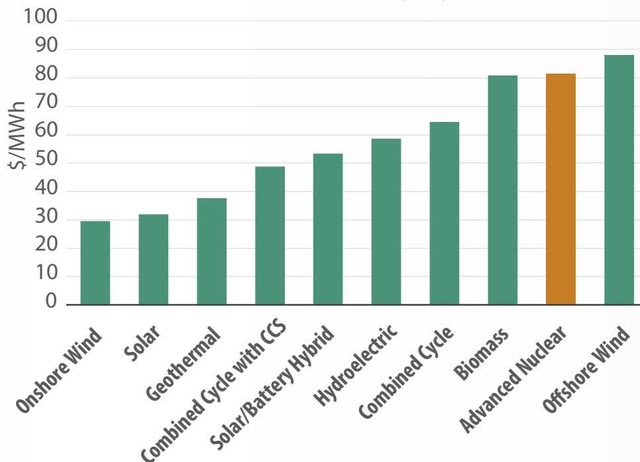
Bar chart showing Levelized Cost of Energy (LCOE) in $/MWh for various energy sources. The sources are Onshore Wind, Solar, Geothermal, Combined Cycle with CCS, Solar/Battery Hybrid, Hydroelectric, Combined Cycle, Biomass, Advanced Nuclear, and Offshore Wind. The y-axis ranges from 0 to 100 $/MWh. Advanced Nuclear is the highest at approximately 81.45 $/MWh, followed by Offshore Wind at approximately 85 $/MWh. Onshore Wind is the lowest at approximately 28 $/MWh.

Forecast for 2030. Source: US Energy Information Administration, Levelized Costs of New Generation Resources in the Annual Energy Outlook 2025 , published April 2025. Levelized cost of energy includes tax credits. CCS = Carbon Capture and Storage.


ANNUALIZED PERFORMANCE QTD YTD 1 YR 3 YRS 5 YRS 7 YRS 10 YRS
Income-Equity (Gross) 4.16 16.49 16.49 14.22 13.23 13.31 11.01
Income-Equity (Pro Forma 0.75% Net)* 3.96 15.63 15.63 13.38 12.40 12.47 10.18
Income-Equity (Pro Forma 3% Net)* 3.39 13.09 13.09 10.88 9.91 9.99 7.75
Russell 1000 Index 2.41 17.37 17.37 22.74 13.59 17.03 14.59
Russell 1000 Value Index 3.81 15.91 15.91 13.90 11.33 12.10 10.53

ANNUALIZED PERFORMANCE QTD YTD 1 YR 3 YRS 5 YRS 7 YRS 10 YRS
Income-Equity (No MLPs) (Gross) 3.53 16.43 16.43 13.18 12.57 12.92 11.23
Income-Equity (No MLPs) (Pro Forma 0.75% Net)* 3.34 15.57 15.57 12.35 11.73 12.08 10.40
Income-Equity (No MLPs) (Pro Forma 3% Net)* 2.77 13.03 13.03 9.87 9.26 9.61 7.96
Russell 1000 Index 2.41 17.37 17.37 22.74 13.59 17.03 14.59
Russell 1000 Value Index 3.81 15.91 15.91 13.90 11.33 12.10 10.53

ANNUALIZED PERFORMANCE QTD YTD 1 YR 3 YRS 5 YRS 7 YRS 10 YRS
MLP & Midstream Energy Income (Gross) 2.09 6.83 6.83 21.39 27.74 14.38 9.14
MLP & Midstream Energy Income (Pro Forma 0.75% Net)* 1.90 6.03 6.03 20.50 26.81 13.53 8.33
MLP & Midstream Energy Income (Pro Forma 3% Net)* 1.33 3.68 3.68 17.85 24.03 11.02 5.92
Alerian MLP Index 3.79 9.76 9.76 20.00 25.96 13.39 8.85

ANNUALIZED PERFORMANCE QTD YTD 1 YR 3 YRS 5 YRS 7 YRS 10 YRS
Infrastructure (Gross) (2.69) 9.60 9.60 10.94 11.95 11.33 10.37
Infrastructure (Pro Forma 0.75% Net)* (2.87) 8.78 8.78 10.12 11.12 10.51 9.55
Infrastructure (Pro Forma 3% Net)* (3.42) 6.38 6.38 7.68 8.67 8.06 7.12
Dow Jones Brookfield Global Infrastructure Index 0.04 14.10 14.10 9.44 7.97 8.38 7.75

ANNUALIZED PERFORMANCE QTD YTD 1 YR 3 YRS 5 YRS 7 YRS 10 YRS
North American Energy (without K-1s)(Gross) 1.18 6.87 6.87 9.44 24.02 16.51 12.65
North American Energy (w/o K-1s)(Pro Forma Net 0.75%)* 0.99 6.07 6.07 8.62 23.11 15.65 11.81
North American Energy (w/o K-1s)(Pro Forma Net 3%)* 0.43 3.72 3.72 6.22 20.41 13.10 9.34
S&P 1500 Energy Index 1.63 7.69 7.69 4.29 23.58 11.18 7.77

ANNUALIZED PERFORMANCE QTD YTD 1 YR 3 YRS 5 YRS 7 YRS 10 YRS
Utilities Plus (Gross) (2.20) 15.08 15.08 12.68 11.44 10.98 11.43
Utilities Plus(Pro Forma Net 0.75%)* (2.38) 14.23 14.23 11.85 10.61 10.16 10.60
Utilities Plus(Pro Forma Net 3%)* (2.94) 11.71 11.71 9.38 8.17 7.72 8.16
S&P 500 Utilities Index (1.40) 16.04 16.04 10.00 9.73 10.56 10.61

As of December 31, 2025. Source: Morningstar Direct. Parentheses represent negative performance data. Results are shown in US dollars. Past performance is not indicative of future results.

*Pro Forma 0.75% net returns are a simulation using a 0.75% annual fee, deducted monthly. Pro Forma 3% net returns are a simulation of the effects of a bundled annual fee of 3%, deducted monthly, which would include advisor and consultant’s fees, transactions costs, and maintenance fees. MHI’s highest annual management fee as stated in our ADV is 0.75%.

YOU MAY ALSO LIKE

ICE agents detain more than 100 people in Memphis

American couple shares experience escaping Nepal’s flood

Note: Investment returns include the reinvestment of dividends and other income. The Dow Jones index is net of dividend withholding taxes.

Miller/Howard Investments Inc. is an independent, research-driven investment boutique with over three decades of experience managing portfolios for major institutions and individuals in dividend-focused investment portfolios. The firm is 100% employee-owned through an Employee Stock Ownership Plan (ESOP). We continue to evolve and develop portfolios that strive to provide investors with various levels of current income and dividend growth. With a primary goal of reliable income and long-term returns, coupled with a belief that investors can play an important role in securing a sustainable future, our portfolios include environmental, social, and governance (ESG) research and/or screening, direct engagement with companies, filing shareholder resolutions, proxy voting, coalition building, and/or public policy involvement. This report represents Miller/Howard Investments’ views. The statistics and projections cited in this report have been provided by sources generally considered to be reliable, but are not guaranteed. Opinions and estimates offered constitute Miller/Howard Investments’ judgment and are subject to change without notice, as are statements of financial market trends, which are based on current market conditions. This material is solely informational. The information and analyses contained herein are not intended as tax, legal, or investment advice and may not be appropriate for your specific circumstances; accordingly, you should consult your own tax, legal, investment, or other advisors, at both the outset of any transaction and on an ongoing basis, to determine such appropriateness. The material may also contain forward-looking statements that involve risk and uncertainty, and there is no guarantee they will come to pass. Any investment returns—past, hypothetical, or otherwise—are not indicative of future performance. The information provided should not be considered a recommendation to buy or sell any security, and should not be considered investment, legal, or tax advice. Securities mentioned are being shown for informational purposes only. Buy and sell rationales are the express opinions of MHI’s investment team. These securities should not be considered a recommendation to buy, sell, or hold any of the securities and are not intended to imply that any one security listed above, or the portfolio as a whole, is appropriate for a particular client. There is no assurance that the securities purchased have remained or will remain in the portfolio or that securities sold have not been or will not be repurchased. To receive a list of all recommendations for the previous year, please email [email protected]. Common stocks do not assure dividend payments. Dividends are paid only when declared by an issuer’s board of directors, and the amount of any dividend may vary over time. Dividend yield is one component of performance and should not be the only consideration for investment.

ESG/Sustainable Investing Considerations: It is important to know that sustainable investments across geographies and styles approach the integration of environmental, social and governance (ESG) factors and other sustainability considerations and incorporate the findings in a variety of ways. Therefore, you should carefully review Miller/Howard’s ADV to understand how a particular product or strategy approaches sustainable investing and if the approach aligns with your goals and objectives. Sustainable investing-related strategies may or may not result in favorable investment performance and the strategy may forego favorable market opportunities in order to adhere to sustainable investing-related strategies or mandates. Issuers may not necessarily meet high performance standards on all aspects of ESG or other sustainability considerations. In addition, there is no guarantee that a product’s sustainable investing related strategy will be successful. Companies, as well as related investment strategies, face increasing risks associated with different and evolving industry and regulatory standards as well as public sentiment toward sustainable (ESG) and diversity (DEI) approaches; these risks include, but are not limited to, becoming the subject of investigations and enforcement actions, litigation, public boycott, and reputational harm. Speak to your financial advisor for more information.

DEFINITIONS: High-Yield Stocks reflects a basket of the total returns for deciles 7, 8, & 9 as provided by Fama/French (value-weighted). Inflation is the year-over-year change of the Consumer Price Index for All Urban Consumers (CPI Index). Free Cash Flow Margin is free cash flow (defined as cash flow from operations minus capital expenditure) divided by revenue. Price-Earnings Ratio (P/E) —The ratio of a company’s share price to its earnings per share. The ratio is used as a valuation tool and can help determine whether a company is overvalued or undervalued. EBITDA = earnings before interest, taxes, depreciation, and amortization. MLP = Master Limited Partnership. S&P 500 Index ® widely regarded as the best single gauge of large-cap US equities and serves as the foundation for a wide range of investment products. The Index includes 500 leading companies and captures approximately 80% coverage of available market capitalization. Russell 1000 Index ® measures the performance of the large-cap segment of the US equity universe. It is a subset of the Russell 3000 Index® and includes approximately 1,000 of the largest securities based on a combination of their market cap and current index membership. The Russell 1000 Index ® represents approximately 92% of market capitalization of the US market. Russell 1000 Value Index offers investors access to the broad value segment of US equity value universe and is constructed to provide a comprehensive and unbiased barometer of the broad value market.

For more information and to request materials:Visit Miller/Howard Investments | Sustainable Income Opportunities® or contact our Internal Sales Desk:Email [email protected] / Call (845) 679-9166To receive the current ADV Part 2A free of charge:Email [email protected] / Call (845) 679-9166

To receive a list of all recommendations for the previous year, please email [email protected] . Please see our website, Miller/Howard Investments | Sustainable Income Opportunities® , for our annual GIPS Report.© 2025 Miller/Howard Investments. All rights reserved. Please print on recycled paper.

The investment portfolios described herein are those of Miller/Howard Investments. These materials are being provided for illustrative and informational purposes only. The information contained herein is obtained from multiple sources that are believed to be reliable. However, such information has not been verified, and may be different from the information included in documents and materials created by the sponsor firm in whose investment program a client participates. Some sponsor firms may require that these Miller/Howard Investments materials are preceded or accompanied by investment profiles or other documents or materials prepared by such sponsor firms, which will be provided upon a client’s request. For additional information, documents and/or materials, please speak to your Financial Advisor.

INVESTMENT PRODUCTS: ARE NOT FDIC INSURED • MAY LOSE VALUE • ARE NOT BANK GUARANTEED


Original Post

Editor’s Note: The summary bullets for this article were chosen by Seeking Alpha editors.

Credit: Source link

ShareTweetSendSharePin

Related Posts

ICE agents detain more than 100 people in Memphis
Market & News

ICE agents detain more than 100 people in Memphis

September 20, 2026
American couple shares experience escaping Nepal’s flood
Market & News

American couple shares experience escaping Nepal’s flood

September 20, 2026
Baby goats spark rabies fears in North Carolina
Market & News

Baby goats spark rabies fears in North Carolina

September 20, 2026
D4vd abruptly parts ways with legal team in murder case
Market & News

D4vd abruptly parts ways with legal team in murder case

September 20, 2026
Next Post
How to Build Multi-Layered LLM Safety Filters to Defend Against Adaptive, Paraphrased, and Adversarial Prompt Attacks

How to Build Multi-Layered LLM Safety Filters to Defend Against Adaptive, Paraphrased, and Adversarial Prompt Attacks

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

Search

No Result
View All Result
Marathon Petroleum: The Focus Should Help (Rating Upgrade)

Marathon Petroleum: The Focus Should Help (Rating Upgrade)

September 15, 2026
John Harbaugh: Giants' win over Cowboys in debut 'really special' – espn.com

John Harbaugh: Giants' win over Cowboys in debut 'really special' – espn.com

September 14, 2026
New AI Glasses, A Mixed Reality Headset And More

New AI Glasses, A Mixed Reality Headset And More

September 18, 2026

About

Learn more

Our Services

Legal

Privacy Policy

Terms of Use

Bloggers

Learn more

Article Links

Contact

Advertise

Ask us anything

©2020- TradePoint.io - All rights reserved!

Tradepoint.io, being just a publishing and technology platform, is not a registered broker-dealer or investment adviser. So we do not provide investment advice. Rather, brokerage services are provided to clients of Tradepoint.io by independent SEC-registered broker-dealers and members of FINRA/SIPC. Every form of investing carries some risk and past performance is not a guarantee of future results. “Tradepoint.io“, “Instant Investing” and “My Trading Tools” are registered trademarks of Apperbuild, LLC.

This website is operated by Apperbuild, LLC. We have no link to any brokerage firm and we do not provide investment advice. Every information and resource we provide is solely for the education of our readers. © 2020 Apperbuild, LLC. All rights reserved.

No Result
View All Result
  • Main
  • AI & Technology
  • Stock Charts
  • Market & News
  • Business
  • Finance Tips
  • Trade Tube
  • Blog
  • Shop

© 2023 - TradePoint.io - All Rights Reserved!