
Georgijevic/E+ via Getty Images
Marvell Technology, Inc.’s (NASDAQ:MRVL) stock price has been on a roller coaster ride for the past three years with shares sliding from above $90 to about $35 in 2022 mostly as a result of the Fed aggressively tightening monetary policy. Then, May 2023 marked a recovery despite declining sales, driven mostly by the AI hype.
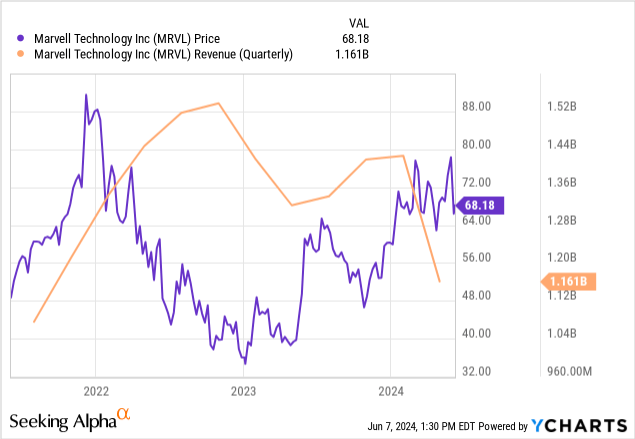
Now, AI has emerged as a key growth driver, but overall sales have been impacted by cyclicality, resulting in the stock being punished, but too hard according to this thesis, whose aim is to show that it is a buy as even a tiny piece of the data center AI chips market share can make a big difference in its income.
First, in an area prone to confusion, it is important to clarify how to compute (custom cloud) and network connectivity chips produced by Marvel fit in AI data centers in a market dominated by NVIDIA Corporation (NVDA).
Identifying Opportunities in Compute and Networking
The Generative AI space has been in ebullition since Open AI’s ChatGPT was launched back in November 2022. Through its partnership with OpenAI, software giant Microsoft Corporation (MSFT) has enhanced both its cloud and productivity tools, but, the company to have profited most financially is Nvidia whose accelerated computing GPUs are in great demand for AI data centers.
However, the semiconductor giant does not have a monopolistic position, and, it faces competition not only from Advanced Micro Devices, Inc. (AMD), but, also from the AI-customized chips being developed by hyperscalers like Alphabet Inc. (GOOG), (GOOGL) without forgetting Amazon.com, Inc. (AMZN), Meta Platforms, Inc. (META), or Microsoft. These could account for 10% to 15% of the market share. Now, these AI-customized chips also called ASIC or application-specific integrated circuits are designed primarily by two companies: Broadcom Inc. (AVGO) and Marvell, which owes its expertise after acquiring Cavium and Avera in 2018 and 2019 respectively.
Moreover, compared to Nvidia’s GPU chip which is general-purpose and ideal for processing large data blocks due to its parallel structure, ASICs, while also performing AI acceleration, are more customized and optimized for training and inference (usage) of AI models and come integrated with the cloud provider’s software development framework.
Looking deeper, Marvell’s initial shipment of custom AI chips was made in the first quarter of fiscal 2025 (FQ1-25) as part of its Data Center end market. However, compute chips are only part of Marvell’s AI story as there is also networking which has already contributed strongly to its data center business through electro-optics products, used to connect cloud AI applications. These include the 800 gig PAM products used for high-traffic deployments.
Company presentation (www.marvel.com)
Revenues from AI networking increased from approximately $200 million in the whole of fiscal 2023 to over $200 million in FQ4-24 alone, or a fourfold increase as production was ramped up.
Therefore, the growth of the AI portion of its Data Center market is being driven firstly, by custom compute chips (ASICs) used to build AI servers and cloud connectivity (networking) chips for linking both front-end users and back-end storage for the data part. These cloud-based chips have helped to more than offset the decline in enterprise on-premise products.
Valuing the AI Opportunities
As a result, the Data Center business grew by 87% YoY in FQ1-25 which ended in April, and 7% sequentially with the AI (custom compute and networking) accounting for about $500 million of sales out of a total of $816 million. Moreover, as production is further boosted, analysts at JPMorgan Chase & Co. (JPM) expect between $1.6 billion and $1.8 billion in AI chip sales this year. This is possible as Marvell is a fabless play that outsources production to third-party foundries, including Taiwan Semiconductor Manufacturing Company Limited (TSM) which means that it can scale rapidly.
Furthermore, for FY-2026, between $2.8 billion to $3 billion in AI sales are expected which is roughly half of Marvell’s overall revenues for FY-24. In addition, it is positioning itself to take advantage of Nvidia’s producing faster GPUs with its dynamic networking product roadmap with some customers qualifying (testing) the next generation of 200 gigs per-lane PAM solutions and DCI (Data Center Interconnects) for 800 gigs products in a market expected to grow to $3 billion by 2028. There are other growth markets as summarized below.
Table prepared using data from (SeekingAlpha.com)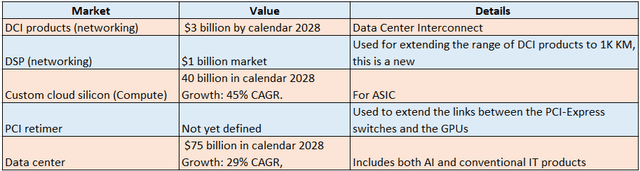
This table shows that in addition to the networking part for AI data centers, there are opportunities in compute (custom cloud silicon) since, the company boasts some key design wins including Google on its 5-nanometer Axion ARM CPU chip, Amazon on its 5-nanometer Tranium chip without forgetting Microsoft on its Maia chip.
Deserves Better Based on Comparison with Broadcom
Therefore, the company deserves a better value but the problem is its trailing price to sales of 11.27x is already overpriced relative to the IT sector by over 270%. However, comparing it to the wider sector ignores its potential in AI which makes a comparison with Broadcom which trades at 14.5x more appropriate. Thus, for those looking to diversify into a data center AI chip space, Marvell is an opportunity and it can potentially appreciate by 35% ((14.5-11.27)/11.27), based on its undervaluation relative to Broadcom.
SeekingAlpha.com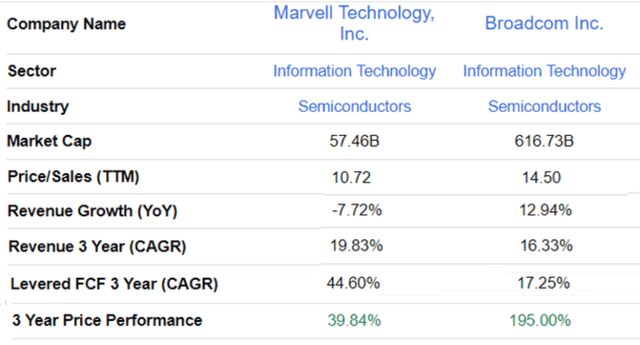
Applying 15% to the current share price of around $68, I obtained $78.3, which the stock has reached several times as shown below. Moreover, this was its peak just before the Fed aggressively hiked interest rates and was again reached at the end of May just before the plunge.
Justifying the target price (SeekingAlpha)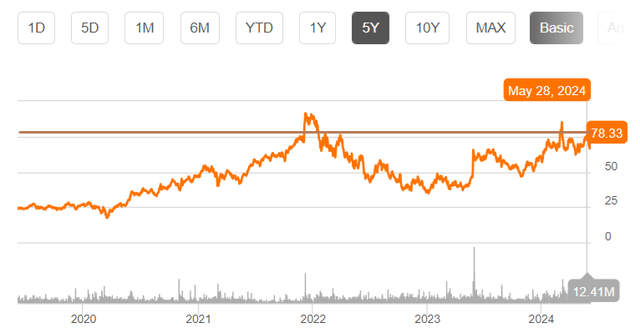
To further justify my bullish position, the company’s three-year performance remains well below Broadcom’s despite both its three-year revenue and FCF growths exceeding the latter as shown in the comparison table.
Still, investors will note this target is well below Wall Street’s average target of $89.41 but is justified given the risks in operating in a cyclical industry.
Cyclicality Risks but it Could Beat Topline Based on Data Center Strength
The revenue breakdown for the FQ1-25 as shown below indicates that Marvell has been facing a serious downturn with its exposure to enterprise networking, carrier infrastructure, automotive, and consumer markets. Only the data center segment which includes the AI growth driver progressed.
Therefore, the risk here is that amid high interest rates which continue to remain above 5% and inflation persisting at above 3%, economic growth suffers. To this end, GDP growth through May has been revised downwards from 2% to 1.8% by the Atlanta Fed following news about manufacturing weakness.
www.marvell.com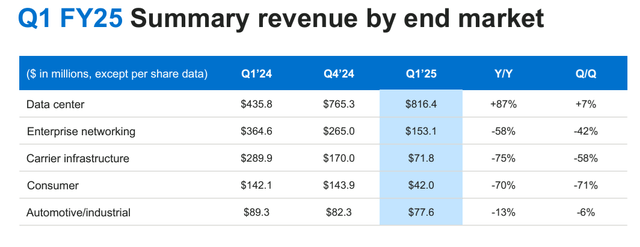
However, the economy remains resilient according to the nonfarm payrolls report for May. Still, as a rate-sensitive stock, Marvell has been impacted as economic resiliency indicates the Fed cannot start to ease up in its battle against inflation. Therefore, the stock could dip further, but I believe that it should receive some support during the FQ2-25 financial results based on Data Center strength.
This is due to the annual labor productivity benefits (of up to 0.6%) it engenders, that AI is being adopted rapidly and is becoming a secular trend just like digital transformation, but, to make supersmart applications widely available, data center infrastructures need to be revamped.
Hence, according to Gartner, spending on data center systems should surge from 4% in 2023 to 10% this year, driven mostly by Gen AI. Now, this is double the 5% (mid-single digits) that Marvell is expecting in its financial outlook for FQ2-25. Therefore, with strength in the Data Center business, the company could exceed the $1.250 billion (mid-point) sales guidance (pictured below), resulting in a stock upside.
SeekingAlpha.com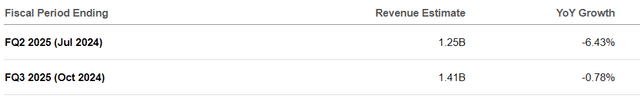
Such a performance could be further helped by a pickup in the Consumer business where sales are anticipated to double sequentially, which is aligned with industry-level expectations for a video game market recovery to accelerate this year compared to the lackluster growth last year. For the remaining segments, revenue growth is expected to be flat but resume in the second half. This is supported by inventory in FQ1-25 being reduced by 20% YoY and now being approximately the same level as in 2022.
Even a tiny piece of the data center AI chip Pie Means A Lot
In conclusion, this thesis has made a case for investing in Marvell which is gaining market share in AI chips for data centers covering both compute and networking.
Looking specifically at compute, AI servers are expected to account for nearly 60% of hyperscalers’ total server spending in 2024. Now, even, if Nvidia is expected to dominate this market with a 75% share, this will still be a $200 billion market by 2027 according to the latest update by BofA Securities. Now, even if Marvell obtains a 3% market share out of the 10%-15% possible with Broadcom enjoying the rest, this implies revenues of $6 billion for FY-27. Tellingly, this would be $500 million more than its entire revenues for FY-24.
Therefore, even a tiny piece of the data center AI chip pie can make a lot of difference for Marvell because of its smaller scale.
On the other hand, gross margins from hyperscalers are expected to be lower than for enterprise customers for a company already suffering from an operating loss given the high R&D expense. However, given that it has already made the bulk of investments in 2018-2019, capital expenses remain relatively low resulting in FCF margins of 27.4% which exceeds the median for the IT sector by more than 170% as shown below.
SeekingAlpha.com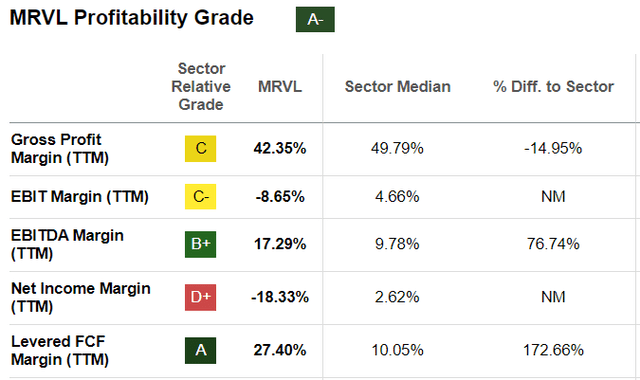
Moreover, this figure should rise in FQ2-25 as cash flow from operations will increase as they will not include the payment of annual employee bonuses. Thus, it can continue to pay dividends and perform stock buybacks, equipped with $848 million of cash versus debt of $4.15 billion. Still, the debt/equity ratio stands at 30%.
Credit: Source link