
Andy Feng
Investment thesis
I had a bullish thesis about Li Auto (NASDAQ:LI) in September 2023, but it did not age well as the stock price tanked by 34% since it went live. The share price decline does not seem to be related to the company’s fundamentals because deliveries are growing rapidly, which allows LI to exercise economies of scale and expand profitability. Fresh news about the company joining the price war with Tesla (TSLA) has been absorbed by the market with great pessimism, as the stock dropped by almost 10% yesterday. In my thesis, I explain why the price war is likely to be a sound strategic move from the management. I have also updated my valuation analysis, which suggests that the stock is dirt cheap. All in all, I upgrade Li Auto to “Strong Buy”.
Why I believe that the price war is good
The stock tumbled notably after the news about Li joining the price war with Tesla, but it looks like a noise to me. On the contrary, the fact that Li is able and brave enough to face Tesla in a price war is a strong positive indicator. Indeed, gaining market share in an emerging industry is crucial, and it is very important to mention that LI has enough fuel to sustain a price war even with Tesla.
First, the company’s balance sheet is a fortress. The company sits on a $14 billion cash pile with almost no leverage and sound liquidity metrics. Therefore, LI is apparently ready to stomach a temporary dip in profitability.
Seeking Alpha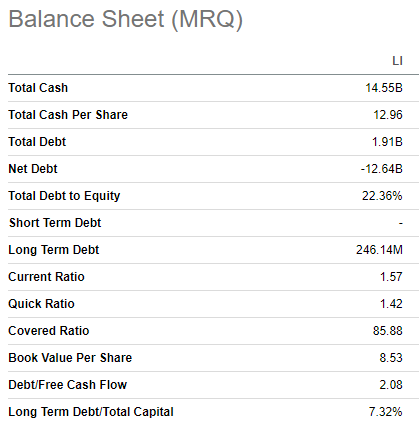
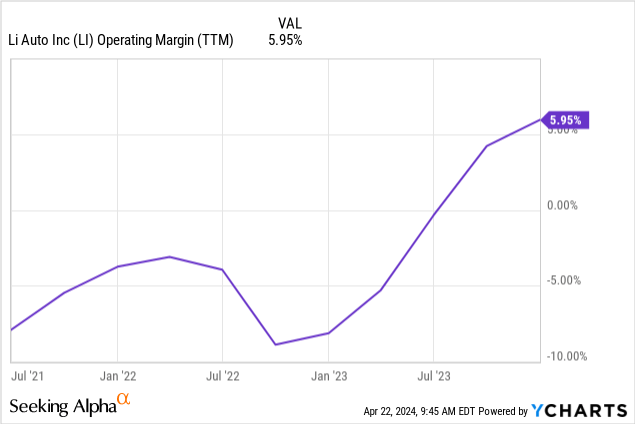
Second, the company has increased its deliveries by 182% YoY in 2023. This big increase in volumes allowed LI to enjoy massive economies of scale and helped to expand its operating margin substantially. The company has generated more than $7 billion in cash from operations, which is another strong indicator supporting the idea that LI is able to sustain a price war even against the largest EV players like Tesla.
Despite demonstrating Q1 actual deliveries numbers notably below initial guidance, LI Auto still managed to demonstrate a 52.9% YoY deliveries growth in Q1. To add context, the overall Chinese EV market grew by 31% in Q1 2024. The fact that LI’s growth outpaced the broader market’s dynamics is an apparent indication that the company continues expanding its market share in the world’s largest EV market.
I think that introducing around 5% discounts on its vehicles will help LI to sustain its stellar deliveries growth dynamics. Another factor likely to boost deliveries is the launch of the Li L6 model by the end of April. I think that at the current stage of its development, Li’s step to prioritize deliveries over profits is sound. Electric vehicles enable manufacturers to drive long-term revenue growth by selling software and subscriptions “on air”. Therefore, physical numbers of deliveries are likely to play a crucial role over the long-run.
Moreover, I think that Li’s rapidly expanding deliveries numbers will likely offset the effect of 5% discounts on the company’s bottom line. As we have seen in the above chart, the company demonstrated solid ability to exercise the economies of scale effect in 2023, which adds to my optimism.
Valuation update
LI’s share price increased by 7% over the last twelve months, but 2024 has been bumpy so far, as the stock plunged by 30% YTD. Valuation ratios of LI look quite moderate for an EV company, which has almost tripled vehicle deliveries between in 2023 compared to 2022.
Seeking Alpha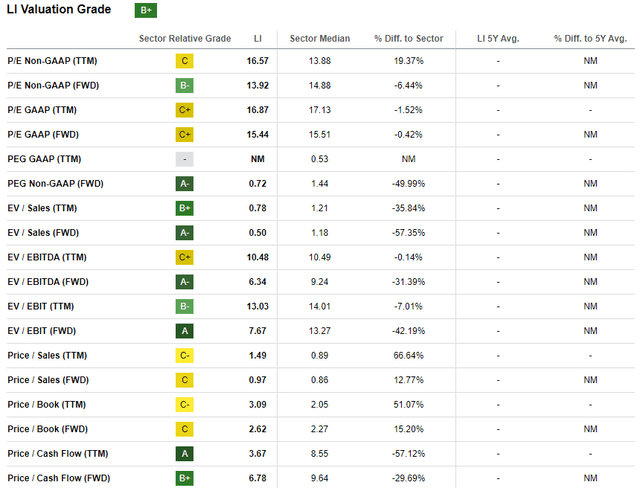
I want to proceed with the discounted cash flow [DCF] simulation. I use a high 15% WACC, considering all inherent risks of investing in Chinese companies. I use revenue consensus estimates for my DCF, which project a 15% CAGR. The TTM FCF ex-SBC margin is 30.2%, which appears to be very aggressive. To be conservative, I use a 6% TTM EBIT margin and expect it to expand by one percentage point yearly. This aligns with the projected revenue growth rate.
Author’s calculations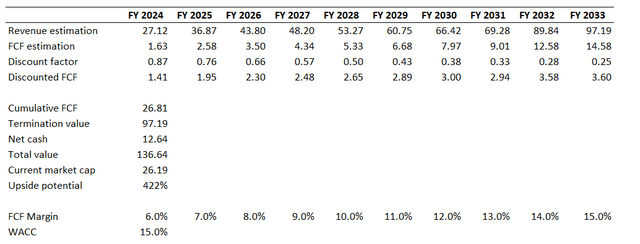
With all the above underlying assumptions, the business’s fair value is $137 billion. This means that the stock is around 5.2 times undervalued, which means that my target price is $130 per share.
Risks update
Despite being incorporated in the Cayman Islands, Li is a company, which operates and manufactures its vehicles in China. The company’s cars are also mostly sold in China. Therefore, investors of LI face all the risks, which are inherent to Chinese companies. These include political and geopolitical risks, together with legal risks related to a possible delisting of Chinese entities from the U.S. stock markets.
Another big risk for investors is the sentiment around the overall EV industry. The biggest EV brand in the world, Tesla faces massive skepticism from investors this year. As the big EV name, TSLA drags down all peers and rivals down as well. TSLA is already down 40% this year and the momentum is extremely weak. It might be a headwind for LI’s share price, even in case the company’s fundamentals keep improving further. The weak sentiment around the biggest EV name might weigh on LI’s price as well.
Bottom line
To conclude, the recent dip provides a strong opportunity to buy LI shares at a compelling price. The company is likely to experience a temporary drawdown in profitability due to the price war with Tesla, but I see long-term potential in this move. The valuation is extremely attractive, which makes Li a “Strong Buy” now.
Editor’s Note: This article discusses one or more securities that do not trade on a major U.S. exchange. Please be aware of the risks associated with these stocks.
Credit: Source link