
serts
Shares of British life & savings giant Legal & General (OTCPK:LGGNY)(LGNNF)(L&G hereafter) have done okay since my last update on the firm in May, with the ADSs delivering a circa 15% total return in that time and more than holding their own against broader European financials.
Of course, equities in general have been on a great run recently, with dovish expectations with regards near-term interest rates driving a huge rally in stocks since around October time. That rising tide has also helped to lift L&G after a previously subdued performance in 2023.
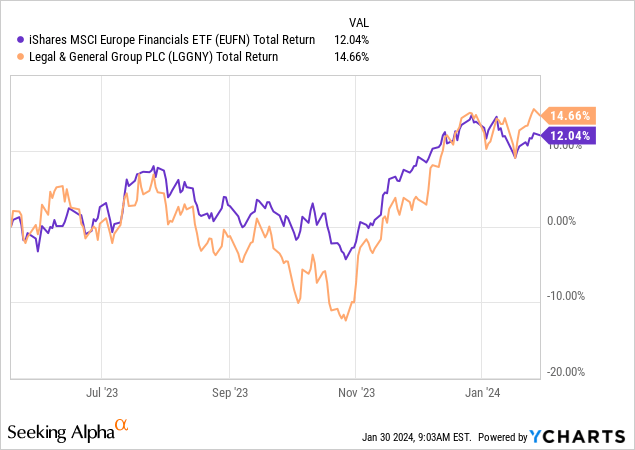
While the rally leaves the shares slightly less of a bargain compared to a few months ago, I would say this was a well deserved performance, with a supportive macro environment for earnings and moderating credit risk concerns justifying a move higher.
Valuations have been the main driving force behind my bullish view of British life/savings players, with Buy ratings also attached to peers Phoenix Group (OTCPK:PNXGF) and Aviva (OTCPK:AIVAF)(OTCPK:AVVIY). This remains the case at L&G, too, and alongside the two points from above these are the three main reasons I remain optimistic ahead of full-year results due in March. As such, I maintain my Buy rating on the stock.
Operating Environment Looks Supportive Of Earnings
To quickly recap, L&G operates a relatively complex business that sees it active across group and individual annuities, life insurance, workplace pensions provision, original asset origination and asset management. As readers will know, the broad pitch here is that these activities are complimentary, with original asset origination also used to back the company’s insurance contracts, for example, ultimately contributing to relatively attractive group-level profitability. Below is a breakdown of L&G’s operating profit by division:
Data Source: Legal & General 1H 2023 Results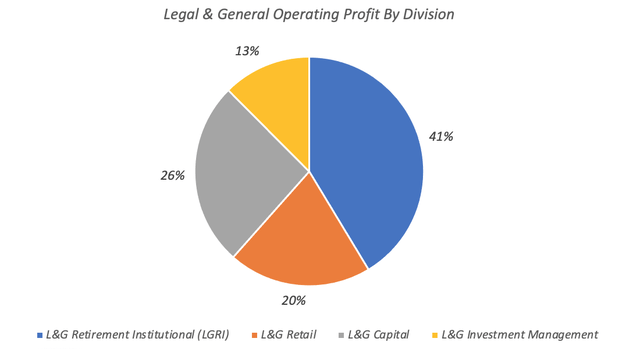
Domestic bulk annuity deals form a big chunk of LGRI’s business. Back in H1, L&G wrote around £5 billion in UK pension risk transfer (“PRT”) business, further anticipating “record PRT market volumes for the full year”. While that is old news by now, we do have more recent data to chew on, with L&G confirming £12.1 billion in 2023 UK PRT volumes through the end of November following the £4.8 billion full buy-in of the Boots Pension Scheme.
With U.K. interest rates having risen from basically zero at the start of 2022 to above 5% currently, the funding positions of legacy DB pension schemes have improved. Companies are often keen to offload these onto insurance companies as, being legacy schemes, they are seen tying-up a disproportionate share of resources that management would rather spend elsewhere. This is helping drive the record activity that L&G’s management sees for 2023.
Data Source: Legal & General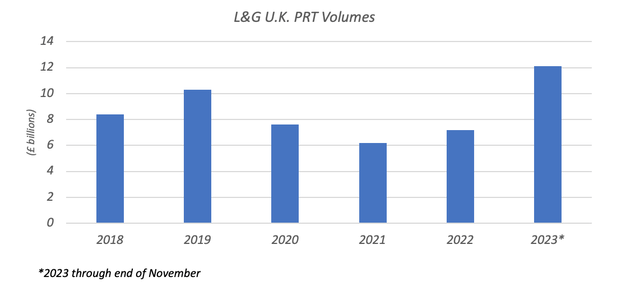
While clearly good for the company in terms of near-term volumes, one extra factor to consider looking forward is the possible knock-on impact in terms of margins. The process of working up a quote and sealing a deal is costly, and ultimately there is no certainty that a provider like L&G will actually close on any given transaction. Throw in competition from other providers to win contracts, and you can see how this might put pressure on margins. However, with demand from schemes significantly up, I would expect this to be positive for the providers, basically putting them in something of a ‘buyer’s market’ for want of a better phrase. This should be supportive of margins and earnings.
Ultimately, PRT will be a melting ice cube type of business, but for now the growth runway remains strong, with L&G expecting around £50 billion in total annual UK PRT market volume in the medium term. The company’s market share is around 25%, so call it around £12 billion annually for L&G. That would allow it to sustain decent growth and, given the dynamics just outlined, should be reasonably profitable growth to boot.
There are also reasons to be optimistic in its Retail business. Firstly, higher interest rates are also good for individual annuity sales, and indeed L&G reported £575 million in H1, up around 25% year-on-year. The macro environment remains supportive, and as a result I expect the company to continue reporting solid volumes for H2 2023 and 2024. It still has nice structural growth drivers in this division, too, with the U.K. DC pensions market expected to grow at a circa 9% CAGR over the medium-term. This will translate into nice fee income growth for L&G, which holds a 20%-plus share of the market.
Credit Risk May Have Abated
One of my main concerns last time out was credit risk. Rapid interest rate hikes had put the U.K. economy on very shaky ground, with the country accounting for around 45% of the bond portfolio that backs the company’s annuity business. Furthermore, and more generally, ‘BBB’ rated bonds accounted for a fairly weighty ~35% of the bond portfolio.
Credit spreads have tightened in the U.K. in that time, in line with the trend seen in other places like the United States following the banking jitters seen early in 2023. While this could obviously represent complacency and end up being the calm before the storm, it could also represent well-founded optimism that a soft landing is within reach.
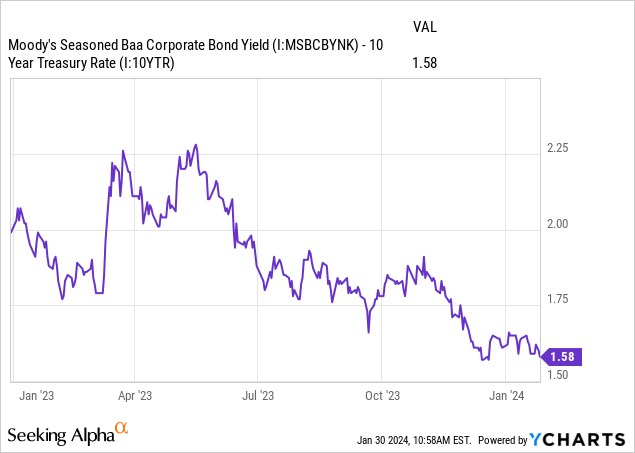
The U.K. economy does remain relatively weak, albeit it is still muddling through amid eventual expectations of a technical recession. All told, I am now slightly less concerned than I was in the middle of 2023.
Property exposure was slightly less of a concern to me for a couple of reasons, namely that, one, direct exposure to real estate valuation swings was modest, and two, counterparty risk was mitigated by quality. That remains the case and I don’t see that the outlook is currently weaker than it was back in H1.
Source: Legal & General 1H 2023 Results Presentation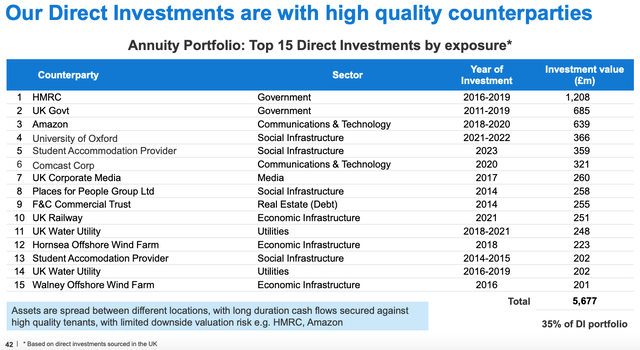
Valuation Remains Attractive
L&G’s ADSs trade for $16.54 at time of writing, around 12% higher than at previous coverage in May. The stock’s valuation remains attractive, with the current quote equating to a TTM dividend yield of 7.7%, circa 20% above its recent historical average.
Data Source: Yahoo Finance, Legal & General, Author Calculation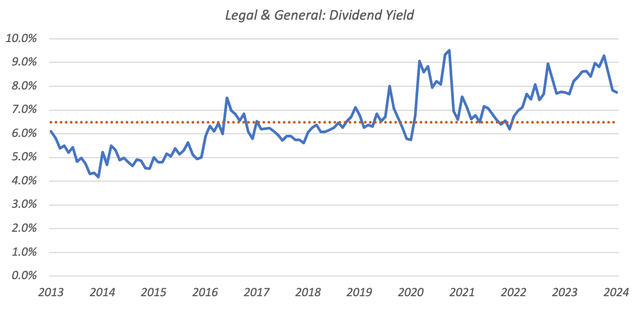
Various explanations have been offered for this, including a complexity discount given the nature of L&G’s underlying business. While logical, an alternative explanation is simply that U.K. stocks in general remain quite cheap across nearly all sectors, and I would note that peers with relatively simpler businesses like Phoenix Group also trade on historically high yields.
In H1, L&G posted a 7% year-on-year increase in its contractual service margin. That should be a decent yardstick for overall medium-term growth prospects in its insurance business, though management also thinks this rate will map to the overall group too. Reported earnings and EPS developments can be more volatile given mark-to-market swings in the investment portfolio, but over time this should roughly net out:
Yes, EPS, DPS, we did say, if we wrote £10 billion on the annuity business, that would lead to growth of 6% to sort of 8% overall.
Stuart Jeffrey Davies, L&G Group CFO, H1 2023 Earnings Call.
A dividend yield near 8% is too high for a company that can post 5%-plus annualized growth on top. I maintain my £3.25/share fair value estimate (~$20.70 per ADS), which maps to a circa 6% dividend yield and ~4.3x book value per share following recently-implemented IFRS 17 accounting standards. Upside is supported by aforementioned growth prospects in PRT, plus above-average profitability, with L&G reporting a circa 40% underlying ROE in H1 2023. As such, I maintain my Buy rating on the stock.
Risks
L&G presents insurance and investment risk. The latter has been touched on already, with its asset portfolio subject to credit risk among other factors. Insurance risks include longevity risk in its annuity businesses, with some degree of offset given the mortality risks inherent in its life insurance business. Due to the long-dated nature of their contracts, life insurers often don’t know the true costs associated with their policies for many years, which I would view as an extra layer of risk for investors to consider.
Editor’s Note: This article discusses one or more securities that do not trade on a major U.S. exchange. Please be aware of the risks associated with these stocks.
Credit: Source link