
Luis Alvarez
Summary
Following my coverage of Kone (OTCPK:KNYJF) in Jan’24, which I recommended a buy rating due to the cheap valuation and positive growth outlook for FY24, this post is to provide an update on my thoughts on the business and stock. I stay buy-rated for Kone as key parts of the business (ex-China) are performing really well with a positive demand outlook, especially in modernization deals that carry a higher margin, and the inflationary environment provides Kone with a reason to raise prices aggressively for its service segment.
Investment thesis
On 19 July 2024, Kone released its 2Q24 earnings, which saw flattish revenue performance, with 2Q24 reporting EUR2.8 billion in revenue vs. 2Q23 reporting EUR 2.83 billion in revenue. By region, Europe revenue saw 6.1% comparable sales growth to EUR1.053 billion; Americas revenues saw 9.9% comparable sales growth to EUR669 million; APMEA revenue saw 6.6% comparable sales growth to EUR 382 million; and Greater China revenue was down 17.2% to EUR698 million. By business, New Building Solutions revenues saw a comparable sales decline of 11% to EUR1.174 billion; however, service revenues reported positive comparable sales growth of 9% to EUR1.114 billion, and modernization revenues saw comparable sales growth of 11% to EUR512.7 million. Profitability continues to improve nicely, with 2Q24 reporting an adj. EBIT of EUR 335 million, implying a margin of 12% (30 bps improvement vs. 2Q23 and 180 bps improvement vs. 1Q24). Profitability would’ve been better if not for the decline in margin in China.
Kone Kone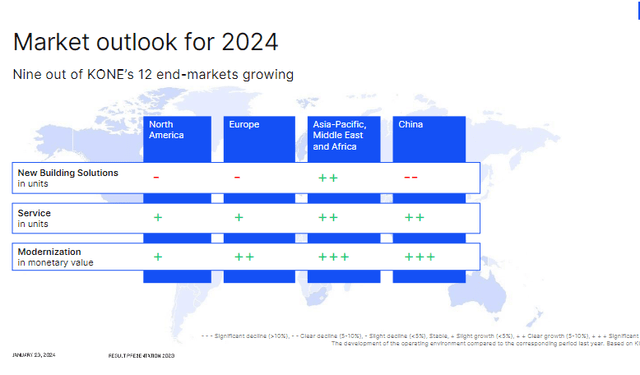
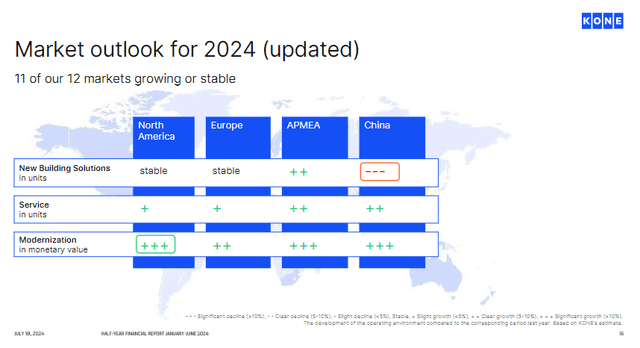
Putting China’s performance aside (which I will talk more about later), Kone continues to see strong demand, with most all markets (ex-China) turning more positive than six months ago. The leading indicator of growth—orders—showed really strong performance in 2Q24, where all countries (ex-China) demonstrated double-digit growth vs. 2Q23, which is particularly noteworthy since this is a continuation of double-digit growth in 1Q24 for the rest of Asia and Europe and an acceleration for the Americas (from high single-digits in 1Q24). The key driver was modernization, which I am very happy to hear because these orders carry much higher margins than Kone’s current consolidated margins. On this front, I believe there is strong potential for more modernization projects and deals, as modern technology has made operating lifts and elevators more efficient and improved consumer satisfaction. Multiple notable deals in the industry also prove the point that building owners are positive about modernizing their lifts.
Examples of such deals include:
- KONE to modernize the elevators at the Thirty High office skyscraper in Central London
- KONE to modernize escalators along Liverpool’s commuter rail network
- KONE to modernize Stamford Harbor elevators
- Otis Wins Modernization Project and 10-Year Service Contract Extension for Burj Khalifa
- Otis Indonesia Begins Replacement and Modernization Project at Jakarta’s Millennium Mall
Another aspect that deserves highlighting is Kone’s service revenue, which saw very strong growth of 9%, driven by 7.5% organic growth (5% volume and 2 to 2.5% pricing), which paints a sustained trend against 1Q24 organic growth of 7.5%. With more than 1.7 million units in the maintenance base, the service revenue stream should continue to see stable mid-single-digit volume growth. In the near term, Kone should be able to exert a fair amount of pricing power given the inflationary environment. Kone’s management did point out specifically in the call that they can potentially drive up pricing more aggressively, which I take as a hint that more pricing increases are going to materialize. For what it’s worth, OTIS’s management also mentioned in their 1Q24 earnings call that the service pricing environment has been really positive. One other thing to note on pricing is that with more units being modernized, it increases the penetration rate for digital, which gives Kone further pricing power.
But overall in pricing, we’ve developed quite well. But definitely, there’s an opportunity to continue to drive pricing more aggressively going forward. That we’ve actually seen as we’ve gone through the last years with inflation, that once you start to really look at it in more detail, there’s more opportunities to it. 2Q24 Kone earnings results call
It is early in the year, but what we’re seeing, again, with the portfolio growth of 4% plus, what we’re getting in Service pricing, like-for-like, over 3 points, we’re feeling good there.
So it’s a gross pricing. The net for the quarter was a little bit higher than being flattish over there, but it’s consistent to what we are seeing in pricing, in the Service business. So EMEA is seeing mid single-digit price increases. Otis 1Q24 earnings results call
Kone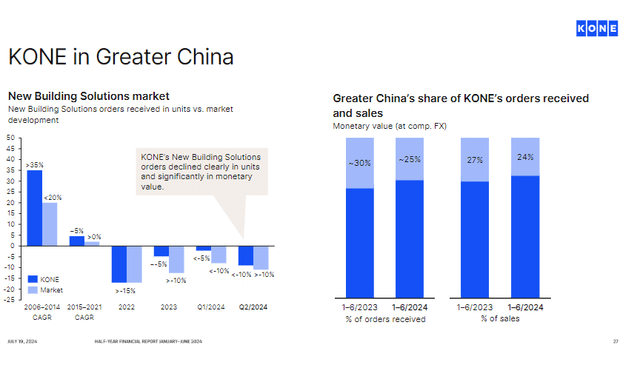
China remains the softest part of Kone’s portfolio, which saw sales fall by 17% and poor new building order performance. The near-term outlook doesn’t look all that great either, given how the Chinese property market is developing so far. As bad as it sounds, I am actually positive on how Kone has performed because it continues to win share—a positive point that I have highlighted previously where scaled players are able to compete aggressively on price to capture share. I mention this because Kone’s ability to grow in China is very much dependent on the macroeconomic situation, where a bad economy equals less new construction. This is something that is outside of Kone’s control, but eventually, the Chinese market should recover, and Kone would be in a much better position to win more deals given its larger scale (better economies of scale to compete more aggressively).
Valuation
Own calculation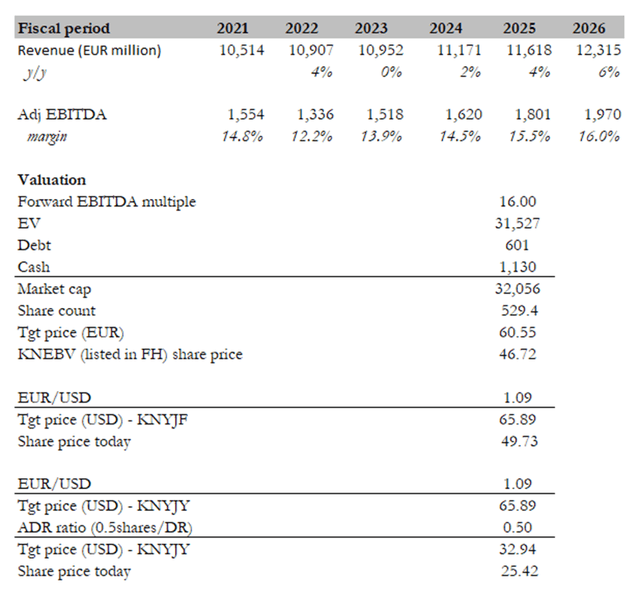
My target price for Kone (for KNYJF) based on my model is ~USD66. My model assumptions are that Kone will continue to see adj. EBITDA growth over time, supported by more modernization deals that provide higher margins; stable service revenue growth, for which Kone has strong pricing power in the near term; and an eventual Chinese economy recovery by FY26. With these growth drivers, I modeled Kone to experience growth similar to the organic growth that it saw between FY14 and FY19. In terms of margin, I used Kone’s historical adj. EBITDA margin as a benchmark for my model. I believe Kone should at least be able to achieve a similar level of 16% adj. EBITDA margin as the business scales, which provides it with more economies of scale.
The valuation has come down to an attractive level of ~14.5x forward EBITDA, similar to where it traded when I gave my last update. While China’s performance is weak today, dragging down Kone’s overall performance, it deserves credit for winning share that better positions itself for the next growth cycle. Coupled with other regions’ strong demand trends, I expect the stock to trade back to 16x forward EBITDA (Kone’s historical average) over time.
Risk
Although Kone is winning share in China, the fact is that China represents 25% of Kone’s business, and the overall market demand is very poor with little potential for near-term recovery. The Chinese government has stayed persistent in not providing direct stimulus to address this problem. Suppose this becomes a massive financial crisis. It could drag down Kone’s business significantly, so much so that overall performance turns negative on a reported basis.
Conclusion
In conclusion, my rating for Kone is still a buy as strong demand persists in all regions except China, particularly for high-margin modernization projects. Notably, Kone’s service segment is doing really well with positive volume growth and could see more pricing upside due to the inflationary environment. While China’s weakness is a concern, Kone’s market share gains position it well for future recovery. The stock’s valuation is also attractive, and I expect it to return to its historical average of 16x forward EBITDA.
Editor’s Note: This article discusses one or more securities that do not trade on a major U.S. exchange. Please be aware of the risks associated with these stocks.
Credit: Source link