
JasonDoiy
Kinder Morgan, Inc. (NYSE:KMI) is seeing its share price approach $20 / share, which outside a brief spike in mid-2022, is the company’s highest share price since the COVID-19 price collapse. As we’ll see throughout this article, despite the company’s lofty valuation, it is still a reliable investment with strong cash flow generation potential.
Kinder Morgan Portfolio
Kinder Morgan has one of the largest portfolios of midstream assets in the industry, including the largest U.S. natural gas terminal.
Kinder Morgan Investor Presentation
Overall, the company has ~66k miles of natural gas pipelines, or ~40% of U.S. natural gas production. Additionally, the company has an interest in ~15% of U.S. working storage capacity, or more than 700 bcf. The company is also one of the largest CO2 transporters, with ~1.5 bcf/d of capacity, and the largest U.S. independent refined products’ transporter & terminal operator.
That combination shows how the company has a valuable and nearly impossible to reproduce portfolio of assets, driving continued shareholder returns.
Kinder Morgan Results
The company’s results come from its strong overall portfolio of assets and continued focus on driving shareholder returns.
Kinder Morgan Investor Presentation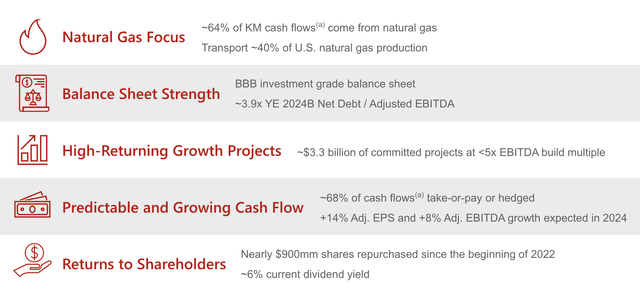
The company sees 64% of its cash flow from natural gas and transports 40% of U.S. natural gas production. The company is maintaining an investment grade balance sheet while planning to spend $3.3 billion on growth-projects. It’s a substantial amount of spend. From a shareholder return perspective, the company plans to spend almost 6% on dividends while repurchasing shares.
It’s worth highlighting here that the company has minimal cash for share repurchases, given hefty spending on growth projects and dividends. Still, the company is generating high single-digit returns and focus on overall shareholder returns.
Kinder Morgan Multi-Year Performance
Kinder Morgan has a strong multi-year history of improving its balance sheet and generating shareholder returns.
Kinder Morgan Investor Presentation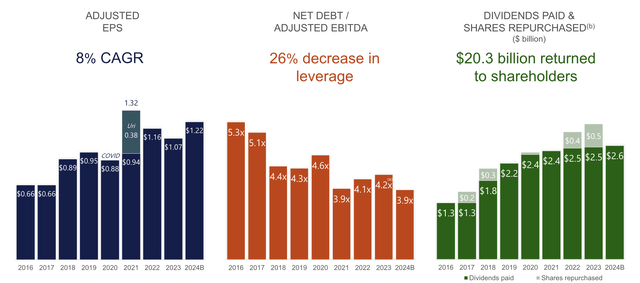
The company has managed to grow EPS by 8% annually while decreasing leverage by 25% overall to 3.9x from 5.3x. That’s strong improvement since 2016. That’s despite continued punishment for the company’s massive dividend cuts in the mid-2015s. The company has managed to return more than $20 billion to shareholders over the same time.
Run-rates for shareholder returns are approaching $3 billion, a substantial amount for a company with a market capitalization of just over $40 billion. The company’s strong commitment to shareholder returns, along with its debt at a safe level, will enable the future use of cash flow for additional shareholder returns.
Kinder Morgan Project Backlog
Kinder Morgan has a substantial project backlog, as it continues to invest, with expectations that capital spending would remain on the high-end of its $1-2 billion range.
Kinder Morgan Investor Presentation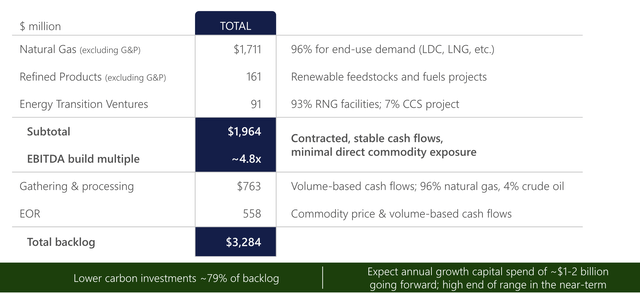
The company’s current backlog program is more than $3 billion, with $1.7 billion of natural gas spending and almost $2 billion in total spending. The company’s anticipated EBITDA build multiple is 4.8x, which will provide hundreds of millions of $ in additional EBITDA for the company. The total backlog includes primarily natural gas-based gathering and processing assets.
The company plans to invest heavily in its backlog, which should enable several % annualized EBITDA growth as long as it continues to see additional opportunities, especially bolt-on opportunities for its portfolio of assets.
Kinder Morgan Shareholder Returns
Putting this all together, the company can continue driving strong shareholder returns, making it a reliable long-term investment.
Kinder Morgan Investor Presentation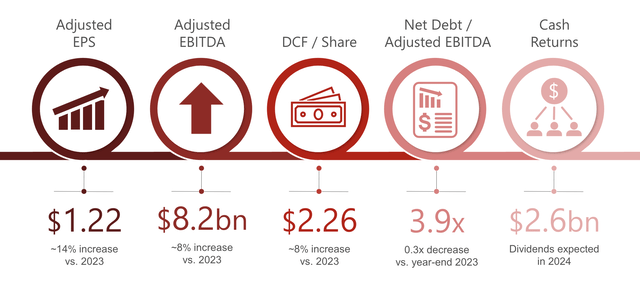
The company expects to generate growing EPS in 2024, although that number is much less important than DCF / share, which at $2.26 is a double-digit yield that affects continued shareholder returns. The company expects a 0.3x net debt / adjusted EBITDA, supported by a strong 8% increase in adjusted EBITDA.
That adjusted EBITDA increase translates to a similar increase in DCF. As the company continues to put more projects into service in the upcoming years, we expect the company’s DCF to continue increasing. The company expects $2.6 billion in dividends, an almost 6% yield it can comfortably afford, with other potential shareholder returns.
Currently, most of the company’s cash is going towards growth after its dividend, however, regardless of what it spends its cash on, we still expect strong overall shareholder returns.
Thesis Risk
The largest risk to our thesis is the long-term demand for Kinder Morgan’s midstream assets in the upcoming decades. The company has a weak renewables pipeline, although its focus on natural gas protects it for the upcoming decades. Still, looking past that, the company has substantial weakness in its long-term plans.
Conclusion
Kinder Morgan is a unique investment opportunity thanks to its incredibly strong portfolio of assets and commitment to both growth and shareholder returns. The company has a dividend yield of almost 6%, one that it can comfortably afford, and one that we expect it to continue paying. We expect it to continue moderate dividend increases.
Going forward, the company’s debt load is well within its targets. That means the company can focus on dividends and growth with modest share repurchases. Depending on opportunity, the company can increase share repurchases, and while the opportunity remains, it’s a valuable investment. Please let us know your thoughts in the comments below.
Credit: Source link