
Robert Way
Since the last time I wrote about China’s retailer JD.com (NASDAQ:JD) in January, its price has risen by 11%. This comes as a relief after it lost 48% of its value in 2023. Even more interestingly, the stock’s rise is at odds with a decline in the price of both its competitors Alibaba (BABA) and Temu owner PDD Holdings (PDD) by 5% and 18% respectively.
Back in January, the stock’s lacklustre performance was explained by its weakening fundamentals, particularly compared with peers. It didn’t help that China’s consumer economy wasn’t as robust as had been hoped, and there were genuine risks to it going forward as well. Here, I take a closer look at whether there are any changes to both the macroeconomic and company level context to assess what’s next for the stock.
China’s economy looks better
While there’s no change to the relatively muted outlook for China’s economy for 2024, recent data does indicate some positive developments are afoot. First, retail sales continue to grow. For the January-February period, the number rose by 5.5% year-on-year (YoY). While this is a slowing down from the 7.2% growth seen in 2023, the number is still higher than the 3.5% growth seen in the corresponding period of 2023 (see chart below).
Also, the relevant figure for JD.com is the online sales growth. At 15.3% in January-February 2024, the number is significantly higher than the 6.2% increase seen in January-February 2023. It’s also a faster increase than the 11% seen for the full year 2023.
Source: National Bureau of Statistics of China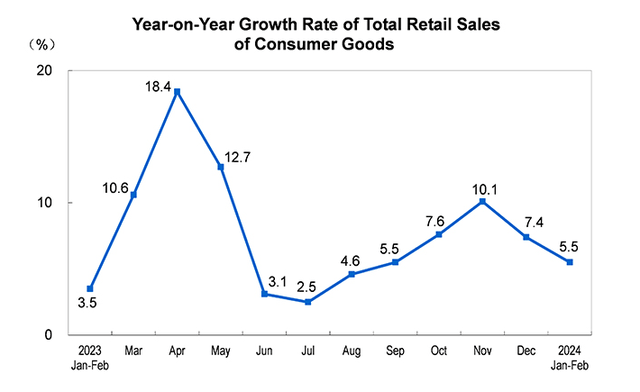
Also, consumer prices increased by 0.7% YoY in February 2024 after a year of actual or near-deflation, which could be a genuine sign of a return to good health for the economy if the trend continues. Interestingly, though, producer prices are still deflationary, which is actually a positive for margins.
Numbers improve slightly on strategic changes
The company’s revenues for the full year 2023 continued to be underwhelming, though. Net revenues grew by just 3.7% in RMB terms, much smaller than the 9.95% growth seen in 2022.
However, zoning in on Q4 2023 reveals signs that JD.com might just be turning a corner. Net revenues during the quarter grew by 3.7%, the second-fastest growth in the year. The company reported a sub-2% increase in two of three quarters, with Q2 2023 being the only exception when it saw a 7.6% increase.
Specifically, I like the relative upturn in the JD retail segment, which accounts for 88% of the net revenues, with JD logistics accounting for the remainder. The segment saw a 3.4% increase in Q4 2023, up from just 1% growth up to the first nine months of the year.
There has been some decline in operating margin to 2.6% from 3% in Q4 2023 compared with the corresponding quarter of 2022, even as net margin for JD.com as a whole actually improved on an uptick in non-operating income (see chart below).
Operating and Net Margins (Source: JD.com)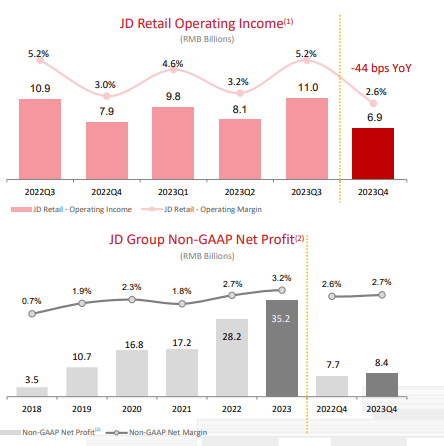
Both the decline in operating margin and revenue growth improvement was to be expected considering the strategic changes in force. These changes included supporting merchants and reducing prices. In line with this, the company has reduced fees for merchants and provided price incentives for customers.
Tapping into promising markets
JD.com is also making efforts to tap into promising product and geographical markets. In terms of products, in Q3 2024, the likes of Kering (OTCPK:PPRUY) owned luxury fashion brand Gucci and multicommodity miner Anglo American (OTCQX:NGLOY) owned diamond brand De Beers opened their flagship stores on JD’s platform, among others (see bullet three under the JD Retail section on Page 2 of the link for details). China’s luxury market is the second biggest in the world, and saw 12% growth in 2023, slightly higher than overall retail sales’ growth. Roping in big global brands may just be the move the company needs to give revenue a boost.
In terms of geographical plans, until recently, it was in the race to buyout the UK’s electronics retailer Currys (OTCPK:CURYY), which has 300 stores in the UK and 800 stores across the world. It has since dropped out, but this does indicate that international growth is still part of its plans, which were revealed in 2021 as well.
Outlook and market multiples
Promising as the possibilities for JD.com are, for now, the recovery is still limited to one quarter and also muted in its extent. Moreover, analysts are also less optimistic about the company’s prospects for 2024 compared to when I checked last. They now expect revenues to grow at 6.1% in USD terms in 2024 compared to 7.6% earlier. They also expect EPS to increase by 2.8% compared to 9.7% in January.
The market multiples don’t offer convincing enough upside either. The stock’s forward non-GAAP price-to-earnings (P/E) ratio, at 8.2x, is still competitive compared to PDD at 13.9x, but it’s now at the same level as BABA, which wasn’t the case in January. Its forward GAAP P/E is still relatively lower at 10.45x compared to BABA’s at 13.1 and PDD at 14.7x.
But I wouldn’t pin my hopes on the 60% upside indicated by the GAAP multiple if it were to equal BABA’s, not when none is indicated by the non-GAAP figure. Even if we consider that JD’s revenue growth isn’t much smaller than BABA’s, the fact remains that BABA still boasts of a much higher trailing twelve months [TTM] operating margin of 13.7%, which can justify a relative premium on the stock.
What next?
In essence, JD.com has definitely become a more interesting stock in the past quarter, but the story isn’t convincing enough yet to make it a definite buy. While revenue growth showed some uptick in Q4 2023, it still can’t be called robust growth. Even though the company’s strategic decisions of supporting merchants and slashing prices can boost growth in the near future, that remains to be seen. In the meantime, the operating margin has expectedly softened a bit.
It does need to be highlighted that the prospects for China’s consumer economy have improved recently. Online retail sales in particular have seen healthy growth, and the consumer price inflation is a welcome sign too. If the economy does pick up, the prospects for JD.com can improve. That remains to be seen though too. For now, I’m retaining the Hold rating.
Editor’s Note: This article discusses one or more securities that do not trade on a major U.S. exchange. Please be aware of the risks associated with these stocks.
Credit: Source link