
Aneese/iStock Editorial via Getty Images
JAKKS Pacific (NASDAQ:JAKK) has reported the company’s Q4/2023 and Q1/2024 results after my previous analysis on the stock. In my previous analysis, titled “JAKKS Pacific: I Am Cautious Despite Great Potential”, I initiated the stock at a hold rating despite the stock seeming very cheaply priced as JAKKS’ long-term revenue trends haunt the company. The analysis was published on the 24th of January.
The stock has performed extremely poorly after my previous analysis, posting a negative result of -41% compared to an S&P 500 appreciation of 7% as the quarterly reports have been short of expectations. As the stock price has fallen, the valuation now seems attractive in my opinion. JAKKS’ evergreen toy revenues continue to grow modestly, and the weakness in content-led sales should still stabilize returning JAKKS into a better revenue trajectory after a weak Q1, making the stock now an intriguing investment.
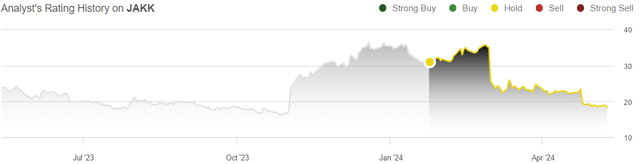
My Rating History on JAKK (Seeking Alpha)
Financial Performance After My January Analysis
The company has reported two quarterly results after my analysis. JAKKS ended 2023 with a year-over-year revenue decrease of -3.4% in Q4. Despite slightly slower sales, JAKKS’ operating income ended up increasing by around $0.4 million into -$15.3 million in the seasonally slow quarter. The poor revenue performance was driven by a dramatic -40% decline in year-over-year costume segment sales. As the segment represent a small portion of JAKKS’ total revenues, the total revenue decline was still modest.
The Q1 results, reported on the 24th of April, were incredibly weak, as revenues fell by an astounding -16.2% year-over-year. The company’s gross margin was pressured by 5.8 percentage points, and JAKKS’ operating income was pushed to -$21.3 million compared to -$4.4 million in Q1/2023. In the quarter, both JAKKS’ toy and costume sales were hit with a large decrease. The company relates the weakness mainly to the fact that no significant films or other content were released during the quarter to help JAKKS with content-led sales that JAKKS experienced in the previous Q1.
In my previous analysis’ DCF model, I anticipated a revenue growth of 5% for 2024 as demand improves. The scenario now seems way too optimistic as revenues have continued to stall – the stock’s negative price action seems to be justified considering the reported Q1 results. The reported Q1 results did still surprise analysts positively as the anticipated revenue weakness had been already communicated, but the normalized EPS of -$1.09 missed by $0.24.
JAKKS Needs New Branded Sales
JAKKS has separated its sales into content-led toy sales, evergreen toy sales, costumers, and outdoor/seasonal revenues in the Q1 earnings presentation. From the data, it is clear that the company’s content-led sales have been the most dominant contributor in the recent sales decreases. JAKKS is fundamentally reliable on content-led sales, contributing around 20.4% of JAKKS’ entire revenues in 2023, and investors can currently see the effect of slower content releases affecting revenues.
In my opinion, investors should look at JAKKS’ ability to strike new branded deals, and at the company’s ability to generate sales from the segment in the future. JAKKS currently sees potential for good content-led sales in Q4 due to new film releases, but the sales of the films are yet to be seen. The company still has a good portfolio of deals with well-known brands, but the ability to leverage the deals has been lowering quarter by quarter.
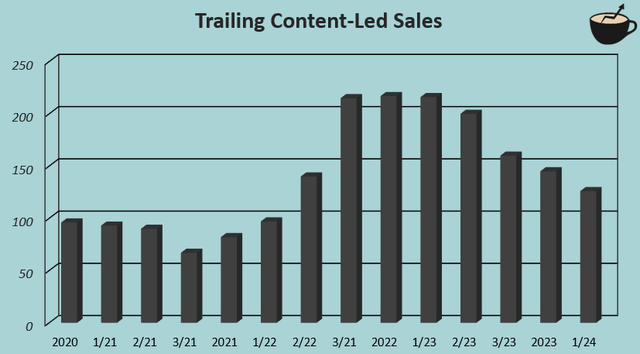
Author’s Calculation Using Q1 Investor Presentation Data
On the other hand, JAKKS’ larger revenue contributor is performing well. Evergreen toy sales have had a clearly upward trend, showing that JAKKS’ performance as a company isn’t turning bad yet. In Q1, evergreen revenues were up by approximately 12.3% year-over-year.
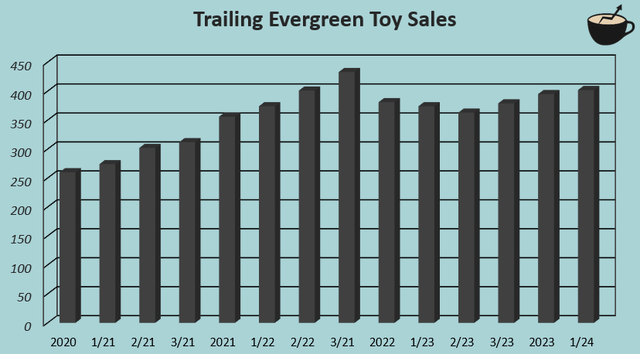
Author’s Calculation Using Q1 Investor Presentation Data
It still must be noted that both costume and outdoor/seasonal revenues have been on a downward trend. The segments contribute quite a small portion of JAKKS’ total revenues, but the decreases still have had a clearly negative impact on JAKKS as a company. As evergreen sales become a larger part of JAKKS’ total revenues, though, the revenue trend should start to show more positive signs in the medium-term future. Also, while I suggest high caution regarding content-led sales expectations, Q4 could show good signs of improvement in the segment. With JAKKS’ cost structure, keeping up a good total revenue level is critical to generate healthy margins from operations, making revenue improvements critical for the investment case.
JAKKS’ strategy still seems to involve a good number of branded collaborations. I believe that the strategy should work out, although the timing of content releases makes the strategy quite volatile. Unless JAKKS gets stuck with no significant new collaborations, I believe that the strategy should contribute towards continued healthy revenues.
Updated Valuation: Cautious Upside Remains
After the company has reported its Q4 and Q1 results, my DCF model is due for quite significant updates. As content-led sales have continued to drag JAKKS’ revenues downwards, I now estimate a revenue decrease of -7% in 2024 compared to a growth of 5% in my previous model. Afterwards, I still estimate quite a similar revenue trajectory, with the perpetual growth again ending at 1% after a couple of years of elevated growth with better content-led segment sales. For example, for 2032, I now estimate revenues of $787.9 million compared to $868.4 million in the previous DCF model due to a previously more positive 2024 estimate.
Due to the lower revenue anticipation, I also updated the EBIT margin estimate downwards into a sustainable level of 5.4% compared to 6.0% in the previous model. I’ve slightly adjusted the cash flow conversion upwards as the previous estimate seems to have been too conservative in my opinion. The total DCF model estimates now represent a more conservative level, and I believe that JAKKS’ stable evergreen revenues should make achieving the figures quite likely.
With the mentioned estimates, the DCF model estimates JAKKS’ fair value at $22.23, around 22% above the stock price at the time of writing. In my previous analysis, I had a significantly higher fair value estimate of $35.44, but with the reported revenue weakness, my financial estimates have taken a hit. After the stock price has fallen, the stock now represents a fairly good buying opportunity in my opinion despite a lower fair value estimate. Still, I suggest caution with the stock, as further revenue declines could potentially ruin the investment case.
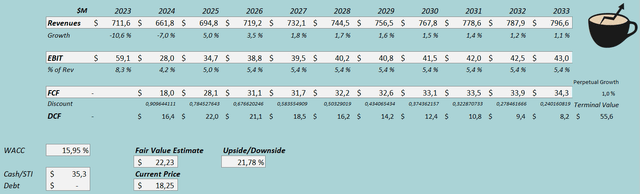
DCF Model (Author’s Calculation)
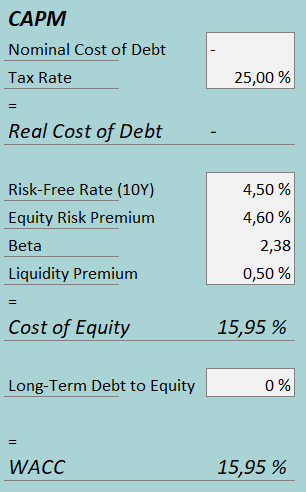
A weighted average cost of capital of 15.95% is used in the DCF model. The used WACC is derived from a capital asset pricing model:
CAPM (Author’s Calculation)
JAKKS Pacific continues to finance operations through equity after paying off the company’s debts – I keep my long-term debt-to-equity ratio estimate at 0%. For the risk-free rate on the cost of equity side, I use the United States’ 10-year bond yield of 4.50%. The equity risk premium of 4.60% is Professor Aswath Damodaran’s latest estimate for the United States, updated on the 5th of January. I keep my beta estimate the same at 2.38. Finally, I add a small liquidity premium of 0.5%, creating a cost of equity and WACC of 15.95%.
Takeaway
JAKKS reported a very wide year-over-year revenue fall in Q1 combined with incredibly bad margins leading to a large year-over-year EPS fall. The company hasn’t had as good content-led sales due to no significant film releases, leading JAKKS to have a series of quarterly sales falls in the content-led sales. Due to JAKKS’ cost structure, keeping up a good revenue level is critical to maintain a good operating margin level.
Still, evergreen revenues continue to be on a good upward trend, and the company anticipates better content-led revenues in Q4 due to new film releases – it seems to me that revenues should still stay at a good level despite recent weakness. I believe that the fallen stock price now reflects quite an attractive level, although the recent revenue trajectory warrants extreme caution with the stock. Due to the attractive stock price, I upgrade my rating on the stock into buy.
Credit: Source link