
Evgenyi_Eg/iStock via Getty Images
Inotiv, Inc. (NASDAQ:NOTV) shares have sold off by more than 30% following a recent court ruling denying the company’s effort to dismiss a class-action lawsuit.
The issue goes back to the company’s acquisition of “Envigo RMS” and “Orient Bio Resource Center,” which was later alleged by regulators to have violated the Animal Welfare Act. The suit alleges that Inotiv executives failed to properly make necessary disclosures at the time of the deal, which ultimately led to large losses through 2022.
While the outcome of this case is yet to be determined, it follows a long list of controversies related to Inotiv’s animal testing business, including a 2023 SEC investigation on its importation of monkeys from Asia.
Unfortunately, the headlines have overshadowed what has been an ongoing financial turnaround including the company’s latest quarter report, which beat estimates and included strong forward guidance. Recognizing the company’s leadership position and what remains a positive long-term outlook, we expect Inotiv shares to remain volatile amid this latest round of uncertainties.

NOTV Financials Recap
Inotiv reported its fiscal Q1 results in February with a GAAP EPS loss of -$0.60, narrowing from -$3.41 in the period last year which included a large impairment chart.
Favorably, the bottom line this quarter came in $0.25 ahead of expectations. Adjusted EBITDA of $9.6 million reversed a -$5.5 million loss in Q1 fiscal 2023.
Revenue of $136 million climbed by 10.3% year over year, capturing a 12% increase from the Research Models and Services (RMS) group, while the smaller Discovery and Safety Assessment (DSA) segment posted a 9% sales increase.
Margins have also improved through a combination of higher pricing and cost savings initiatives. General and administrative expenses declined by -30% decline in general and administrative expenses.
source: company IR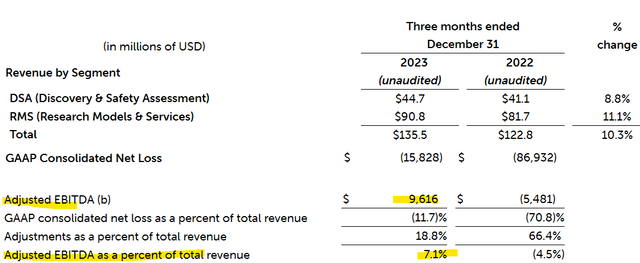
Within the RMS segment, the bulk of sales are large and small animals covering purpose-bred rats, mice, rabbits, as well as non-human primates (“NHP”) for use by researchers.
Management notes that even as volumes of NHP are down by -20% over the past year, higher pricing into strong demand has covered that spread. The company also commercializes related consumables for the ongoing care of the “models.”
In the DSA business, a major theme for the company has been investments on expanding capacity toward opportunities in diagnostics. On this point, the DSA backlog ended the quarter at $152.3 million, up sequentially from $132 million just since the prior quarter.
source: company IR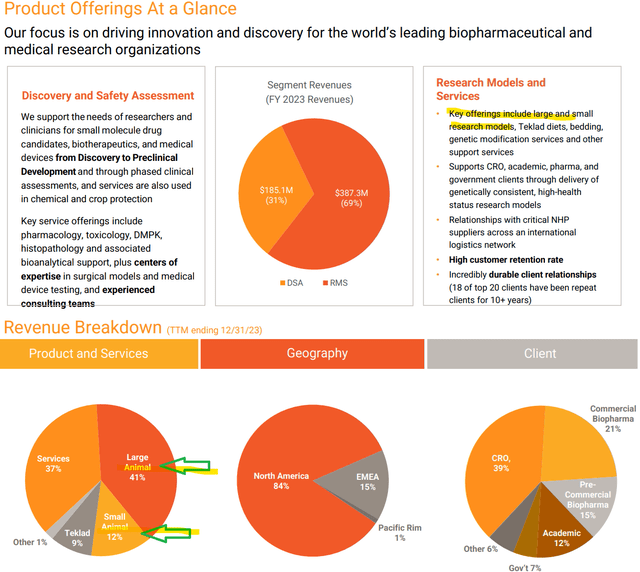
The messaging by the company is that demand is strong with the strategy focused on driving margins and profitability higher. Inotiv expects fiscal 2024 revenues in the range of $580 to $590 million, compared to $572 million in 2023. The target for 2024 adjusted EBITDA growth is stronger, in a range of $75 to $80 million representing an 18% y/y midpoint increase.
Inotiv ended the quarter with $22 million in cash against $428 million in total debt between a term loan and a convertible issuance. Considering the adjusted EBITDA guidance, a net leverage ratio around 5x is elevated but stable under the current circumstances considering an expectation of improved cash flows going forward. Nevertheless, we’d say that the balance sheet is a weakness in the company’s investment profile.
What’s Next For NOTV?
It would be a matter of speculation to guess the outcome and any particular lawsuit Inotiv is facing or potential monetary damages. At the same time, we can look at the litigation risk as representing a one-off charge with the assumption the company will continue to operate normally under the current regulatory environment.
On the other hand, considering the company’s debt position, there is a real concern that a materially large penalty or settlement could undermine the company’s liquidity position. In other words, Inotiv with a current market cap of just $200 million has limited flexibility to deal with these types of legal matters compared to larger and more diversified companies.
When looking at Inotiv, it’s also worth considering the backdrop for animal testing for the pharmaceutical and cosmetics industries are undergoing significant changes and remain a sensitive subject.
In 2023, the FDA announced a change in policy that no longer requires animal testing as part of the regular drug approval process. There are still exceptions, and some companies may choose to test on animals anyway, but the appearance is that the addressable market has gotten smaller. Separately, several countries have completely banned testing cosmetics on animals.
For Inotiv, this means that its strategy will need to evolve balancing higher pricing in support of margins while also looking at monetization opportunities in new services.
Research from Wall Street bank Jefferies Financial Group Inc. (JEF) has cited Inotiv’s growing direct sales force as a tailwind for operations in its bullish cash for the stock.
Long term, the company is targeting “high-single digit to low-double digit” annual revenue growth with room for the adjusted EBITDA margin to triple from the current level. How effectively it delivers on those targets will define stock price potential.
source: company IR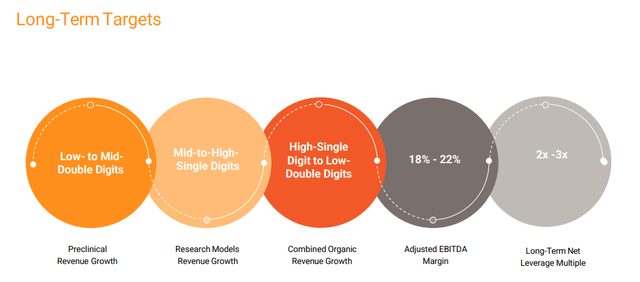
Final Thoughts
We rate Inotiv, Inc. as a hold, balancing the improved financial trends against this latest layer of controversy adding to ongoing financial risks. We believe the number of uncertainties justifies the otherwise modest valuation with shares trading at an 8x EV to forward EBITDA multiple.
Given the sharp selloff in recent weeks, there is a case to be made that some of the negatives have already been priced in. We see the $6.50 share price level as an area of technical support.
On the upside, seeing a favorable resolution to the legal proceedings and a string of solid quarterly results will be important. Monitoring points here include the cash flow trends, profitability margins, and headlines related to the animal testing market.
Credit: Source link