


































Gary Yeowell
Dear readers/followers,
A week ago or so, I published an update article on Gecina (OTCPK:GECFF) – now the same thing has become relevant to do for the company Icade (OTCPK:CDMGF), which is the second Parisian/French REIT that I have invested in. While my position at the time of writing is currently at almost a negative RoR, I am completely and utterly unworried about the prospects of the business and the capital that I invested in it.
I’m of a very high conviction that there will be an eventual upside – that is why I continue to invest here, and why I believe there’s merit in continual investment here.
This is a follow-up/reminder sort of article, for the quality and the appeal of some French REITs – where this is an attractive one.
I understand that some of you might be tired of me pounding the table for French REITs, of all things, but I will continue to pound the table for undervalued and quality companies wherever I find them. And if the risk-reward is attractive to a degree where I have a very hard time seeing a general downside, well, then I will pound the table twice as hard.
That is the case for Icade here, and you can read more about it in my article here.
Let me update the case for the company and show you why this is a good deal.
Icade – both this company And Gecina are likely to see a big valuation boost
In this article, a continuation or follow-up on my latest Icade article, you’ll be shown why I believe that Icade is not only a worthy investment but even a conservative one. These sorts of non-standard REITs can be difficult to understand, especially if one does not come from Europe.
But that’s why I am here. My job is to help you to understand these REITs, and to understand why an investment here is in your best interest, provided the company meets your goals.
I made my first investments in Icade over the course of the last 24 months or so, trying to get it whenever the prices were comparatively cheap – and I have been successful so far in doing so.
So, we have 1Q24, where the company did a few things. Chief among them was the strategic plan with priorities for 2028, given that the company has gone through quite a number of changes.
At its heart, Icade like Gecina is a CRE company – an office REIT with a strong property development arm, which is supported by a resilient overall backlog that is unlike those found across the pond.
The company also went ahead and confirmed the dividend, fully paid in cash as opposed to shares, in late April of this year.
More importantly, 2024 guidance is now confirmed.
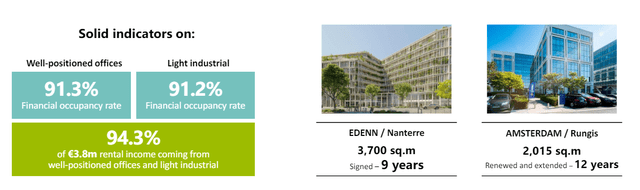
A word or two on leasing activity – and the important thing here to understand is that it mirrors Gecina in some ways. 14,000 sqm worth of signed/renewed leasing, with €3.8M in annual rental income at nearly 7 years, with a financial occupancy rate of 87.8%. Not the best in the industry, certainly, but good enough – and this was for 1Q leasing. For the portfolio in its entirety and some of the company’s new projects, here is what we have.
Icade IR (Icade IR)
Like any REIT, the company is working to sell some of the underperforming assets in its portfolio or the properties it finishes in its property development pipeline, in this case, residential units. The company sold 207 units at a €48M price. Overall, the orders continue to come in, albeit at a lower rate, but Icade still has €1.7B in order backlog.
Like some US REITs, Icade also owns an expansive portfolio of land. While Icade is experiencing the same sort of building trends as the rest of the market – meaning that construction starts are currently cratering, and Icade is actually selling land opportunistically, it remains a solid upside for the company. The company is in the process of renegotiating
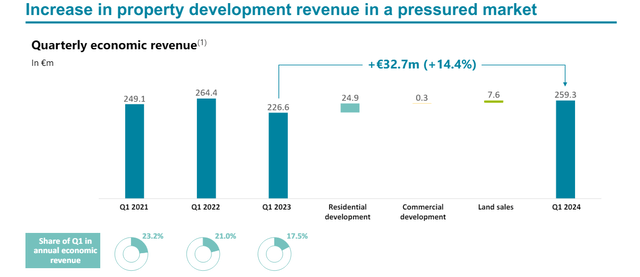
On the hard data side, gross rental income is growing – with consolidated revenue up 16.2%, and with rent growing 4%, Icade continues to be in a very good position.
It’s a good position for Icade when the company can grow its revenue and its gross rentals during a time that is characterized by significant overall pressure. The company also managed a solid indexation increase. Most of the upside came not from land sales or CRE, but from residential development sales.
Icade IR (Icade IR)
On the fundamental side, Icade remains extremely solid. The company continues to have a net cash position of around €1.4B, with another €1.5B in uncommitted revolving credit, next to a total debt until 2028 of less than that, meaning the current cash and available immediate credit/revolver ability completely covers the entirety of the company’s financial commitments until 2028.
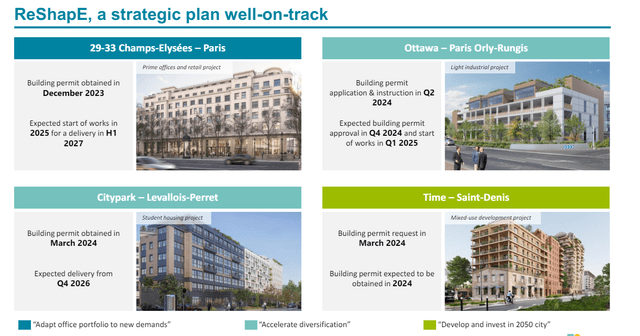
The company’s plan going forward includes new construction and renovation.
Icade IR (Icade IR)
Remember, that this year’s dividend was a once-off, and that future Icade dividends are going to be much lower than this one. The guidance for 2024 calls for a Group NCCF of around €2.9 on the high side. Current estimates for the 2025E dividend call for around €3/share – though this company has plenty of forecast uncertainty in its current operations. Icade has been on a continuous journey of optimization for a few years, that have really changed the nature of its portfolio. If you look at some of my initial Icade articles, you’ll see that it was a completely different REIT at this time (Santé and the like).
While the company now seems to be nearing its goal, it remains uncertain, or at the very least somewhat open, at what level earnings eventually do end up. At the current price of €26/share, it seems clear that with current dividend forecasts and a BBB+ rating, the company is going to remain a relatively high-yielding real estate business. Here are the current dividend estimates for Icade, which also include a divestment dividend in 2028. It does show you, however, that even in the next few years, the company is likely to be a very solid dividend yielder.
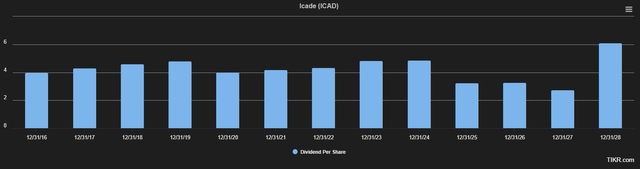
Tikr.com Icade Dividend (Tikr.com Icade Dividend)
Based on the continued dividend certainty and the company’s successful repositioning of its portfolio with new projects, good sales, and continued demand, I would continue to characterize the business as very appealing, provided you have the patience to take a stake for a number of years going forward.
The company is currently in a bit of a slump, though higher than when I bought my last set of shares.
However, on the valuation side, it’s possible to, as I see it, pick this business up at a discount due to the uncertainty that in some ways is visible here at this time (from the portfolio positioning perspective).
Icade – A speculative upside, but an upside nonetheless
Out of Gecina and Icade, Gecina is by far the more stable French real estate business. This one is somewhat speculative – but I also want to remind you that it does trade at BBB+. So while some would say that it’s not necessarily a conservatively safe business, I would say that based on the company portfolio, it most certainly is a safe business to invest in.
The company has disposed of much of what made the business volatile and what resulted in much of the re-evaluations that the company was previously highlighted for – including by me. What remains is a surprisingly solid core of attractive assets which, I believe, will generate substantial attractive cash flows. At the same time, Icade has moved to conserve and to put itself in a position of very little overall debt.
S&P Global gives Icade an average valuation of around €22 low to €37 high, and that’s a fairly conservative range even now, considering it was at almost €70 a year ago, and only a few things have really changed for Icade. The average at this time is €30/share, which gives us an average upside of 10% – conservatively speaking. However, I believe the company is easily worth more than that. This is because the current valuation target represents no more than around 0.6x to NAV. And I believe that Icade, with Parisian core assets, should be valued closer at 0.8-0.9x. (Tikr.com Paywalled information) I can get on board with not going for 1x or above that – but a 10-15% discount is all I’m willing to give, before I call the company “cheap”, which is what I am doing here.
In my initial article, which was before the full impact of rate changes, I discounted the company by 40% to EPRA NTA, which put it at the time around €48/share. I’m maintaining my price target of a further discount to €42/share to account for further downside in the rate environment here, and I’m not going lower than this.
Even just forecasting Icade at the 15-year normalized earnings multiple, which comes to around 15.62x, the company would, based on this and the 2026E earnings, easily be worth around €45-€47/share.
I expect more volatility out of this company. However, if we normalize the dividend expectations for the next few years, we come to around €3/share, we could even discount that to €2.5/share (a conservative payout ratio based on NCCF estimates). At that level, you’d be getting a yield of around 10% here – and that’s based on some of the most attractive assets in Paris, which gives the company a very decent coverage, including by their own NCCF estimates.
If you expect this, and you’re fine holding the business as it goes up and down quite a bit, then this is a solid speculative play that you might consider taking or doing.
I own Icade in my own portfolio and have no plans to divest my holding here, but rather add to it.
Questions? Let me know! Otherwise, my thesis for Icade is as follows.
Thesis
-
Contrary to popular belief, Europe does have a couple of REITs that are worth getting into, as well as straight real estate companies. I’ve looked at a few of them so far, and I intend to continue doing so.
-
Icade is, post-disposal of healthcare, an interesting mix of office, and residential development with a 39% stake from the French government. These things, together with the fundamentals, make the company an appealing prospect to me. Once we’ve established that a company is an appealing prospect, what’s left to estimate is the valuation.
-
Post disposal and considering relevant EPRA numbers, I would put the company at a discount of 50% to its EPRA NTA. This still puts the PT at over €40/share, which is a considerable upside from the current share price.
-
I consider the company safe, and a “BUY” here for the 2024E period.
Remember, I’m all about:
1. Buying undervalued – even if that undervaluation is slight, and not mind-numbingly massive – companies at a discount, allowing them to normalize over time and harvesting capital gains and dividends in the meantime.
2. If the company goes well beyond normalization and goes into overvaluation, I harvest gains and rotate my position into other undervalued stocks, repeating #1.
3. If the company doesn’t go into overvaluation, but hovers within a fair value, or goes back down to undervaluation, I buy more as time allows.
4. I reinvest proceeds from dividends, savings from work, or other cash inflows as specified in #1.
Here are my criteria and how the company fulfills them (italicized).
-
This company is overall qualitative.
-
This company is fundamentally safe/conservative & well-run.
-
This company pays a well-covered dividend.
-
This company is currently cheap.
-
This company has a realistic upside based on earnings growth or multiple expansion/reversion.
While certainly speculative at this point in time, I believe Icade is still an absolutely solid investment, and I’m buying more shares and expanding my overall position.
Editor’s Note: This article discusses one or more securities that do not trade on a major U.S. exchange. Please be aware of the risks associated with these stocks.
Credit: Source link










