
Michael Derrer Fuchs
IBM Falls On Fears Over HashiCorp Acquisition
International Business Machines Corporation (NYSE:IBM) investors who attempted to defy gravity and didn’t layer out (cut exposure) from their positions in March 2024 are likely hurting. IBM stock plunged toward the $165 zone this week after IBM released its first-quarter earnings release. International Business Machines Corporation also confirmed its acquisition of HashiCorp, Inc. (HCP), paying a nearly 43% premium over HCP’s April 22 close. As a result, IBM has dropped almost 17% from its March 2024 highs, declining firmly into the correction zone.
In my previous IBM article, I highlighted a buying opportunity on IBM that could be due if we get a steep pullback. While IBM surged toward its 2024 highs in March, the post-earnings decline could provide a timely chance for dip-buyers to consider adding exposure. Let’s assess further on whether we should capitalize on IBM’s near-term weakness.
HCP Quant Grades (Seeking Alpha)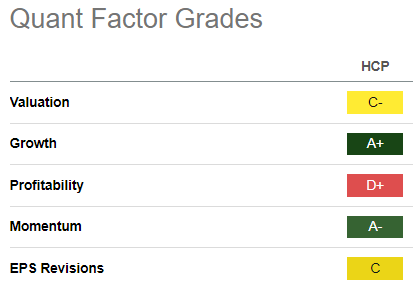
Notwithstanding the surge in HCP in response to the IBM deal, Seeking Alpha Quant assigned a “C-” valuation grade to HCP. IBM’s offer price of $35 per share represents a premium of about 6.7% over April 25’s closing price. Therefore, it seems reasonably priced, considering HCP’s best-in-class “A+” growth grade.
While HashiCorp is classified along with IBM in the tech sector (XLK), HCP is categorized into the application software industry, while IBM is rated along with its IT consulting peers. As a result, I assessed IBM’s efforts to incorporate HashiCorp indicates the company’s commitment to driving cross-selling synergies and consolidating IBM’s value proposition in multi-cloud and end-to-end hybrid platforms.
HCP Acquisition Is Expected To Be Accretive
IBM management believes acquiring HashiCorp will help “address the increasing complexity of infrastructure in the technology landscape.” HashiCorp’s leadership in “application, infrastructure, and security lifecycle management” should strengthen IBM’s hybrid positioning. Therefore, it seems like a reasonable acquisition to complement IBM’s current strategy, reducing the execution risks from the integration.
Moreover, International Business Machines Corporation management expects the HCP deal to benefit its operating performance in the near term. Accordingly, the HashiCorp acquisition is expected to be “accretive to adjusted EBITDA within the first full year.” IBM management anticipates the deal to close by the end of 2024. Hence, IBM investors should expect a profitability lift by FY25.
HCP free cash flow estimates (TIKR)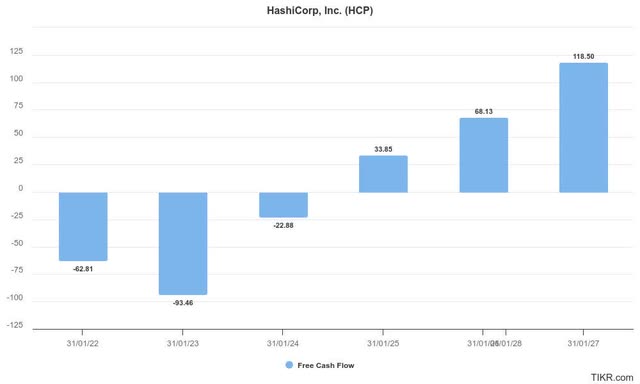
However, it’s clear that IBM expects free cash flow accretion to progress more gradually as it works out the integration challenges. Despite that, HashiCorp’s pre-acquisition FCF estimates trend in the correct direction. However, given the IT consulting leader’s massive FCF generation, they aren’t expected to provide a significant lift to IBM in the near term. Consequently, IBM expects the deal to be accretive to FCF in year two (FY2026).
While analysts and the market will likely focus on the HCP acquisition, investors should also consider the near-term weakness in IBM’s consulting segment. Management noted the impact of “higher-than-expected interest rates,” which affected discretionary tech spending as enterprises pulled back. However, IBM is confident of a growth reacceleration in the second half, suggesting we should expect headwinds to peak by Q2.
Accordingly, IBM posted revenue growth of just 1.5% in the first quarter. IBM’s adjusted EBITDA growth has remained resilient, as the company delivered an increase of 4.1% in Q1. While IBM’s software segment delivered reported revenue growth of 6%, it faced challenges in Consulting, as growth remained flat. Infrastructure was down close to 1%, as the quarter was relatively tepid.
However, IBM management’s guidance of mid-single digit constant currency revenue growth for FY2024 (midpoint forex headwinds about 1.75% point) suggests a relatively strong revenue growth reacceleration in H2. As a result, I believe it should provide a more decisive impetus for long-term IBM investors to consider adding exposure at the recent pullback.
IBM Quant Grades (Seeking Alpha)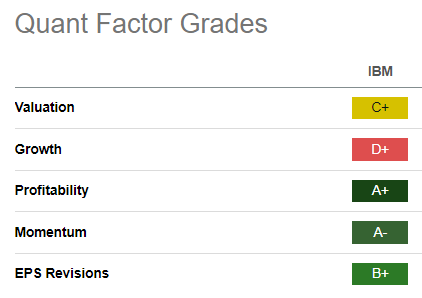
With IBM’s fundamental thesis predicated on its IT consulting business, I believe it’s reasonable to consider IBM’s bullish thesis relative to its direct peers. IBM’s “C+” valuation doesn’t suggest a dislocation, notwithstanding its recent pullback.
However, IBM’s momentum has remained robust (“A-” momentum grade), corroborating strong buying sentiments. Therefore, should investors anticipate dip-buyers returning to underpin IBM’s recent battering to add exposure?
Is IBM Stock A Buy, Sell, Or Hold?
IBM price chart (weekly, medium-term, adjusted for dividends) (TradingView)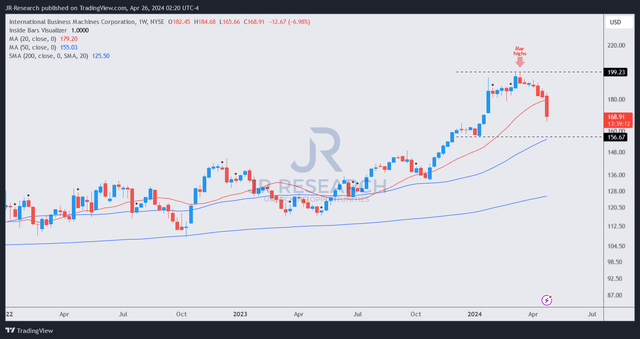
IBM has dropped toward levels last seen in January 2024, digesting three months of gains. There could still be downside volatility toward the $155 zone before I expect a more robust consolidation phase.
However, the risk/reward has improved even as IBM needs to justify the $6.4B acquisition in enterprise value for HCP. With no anticipated dilution, IBM has significant flexibility in funding the deal with cash on hand of $19.3B. IBM management also guided for $12B in FCF for 2024, above last year’s $11.2B. Therefore, I believe the market’s pessimism seems overstated as investors assess the trajectory of HCP’s growth thesis.
With IBM stock clearly in a medium-term uptrend, I’m confident that the battering represents a solid opportunity for investors to add more shares.
Rating: Upgrade to Buy.
Important note: Investors are reminded to do their due diligence and not rely on the information provided as financial advice. Consider this article as supplementing your required research. Please always apply independent thinking. Note that the rating is not intended to time a specific entry/exit at the point of writing unless otherwise specified.
I Want To Hear From You
Have constructive commentary to improve our thesis? Spotted a critical gap in our view? Saw something important that we didn’t? Agree or disagree? Comment below with the aim of helping everyone in the community to learn better!
Credit: Source link