
Trevor Williams
Hims & Hers Health, Inc. (NYSE:HIMS) provides medical prescriptions for generic medicine, and prescription-free health products through the company’s ecommerce platform, focusing on sexual health, hair loss, mental health, and weight loss products. The more non-recurring offered products include skin care, shampoos, and other similar health products. Hims & Hers sources the products and services through a network of partnerships and the company’s own built technology, enabling a capital light business model.
After a merger with a SPAC in 2021, Hims & Hers stock has now risen from the $10.00 SPAC price into $20.37. The stock has over doubled in the past year, only slowing down in the past few weeks as the company continues to push for aggressive earnings growth through new product launches and increased subscribers.
One Year Stock Chart (Seeking Alpha)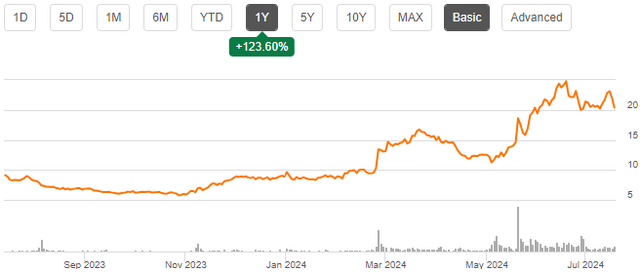
Financials: Continued Rapid Growth Has Finally Pushed Earnings Positive
Hims & Hers has grown its revenues impressively well – from Q1/19 to Q1/24, the company’s quarterly revenues’ CAGR stands at 72.8%. The growth momentum is still well ongoing as revenues grew by 45.8% in Q1 into $278.2 million.
Hims & Hers also raised the 2024 guidance to $1.20-1.23 billion (a growth of 37.6% to 41.1%), and guides for revenues of $292-297 million in Q2. New product launches, increased marketing, and a good share of recurring revenues from subscribers provide a great platform for Hims & Hers to continue the growth. Subscribers, defined as customers with automatic billing for a recurring product purchase, grew 41% year-over-year in Q1 into 1.71 million and by 11% sequentially from the end of 2023.
Author’s Calculation Using TIKR Data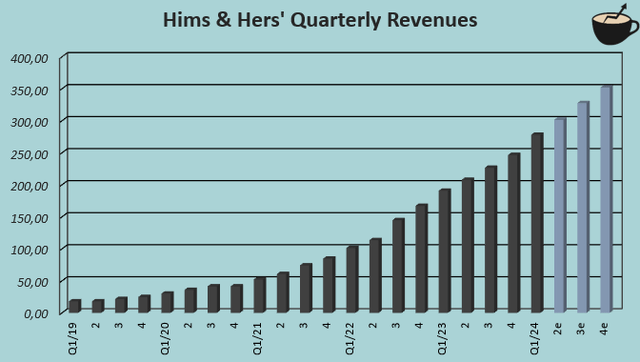
While very high marketing expenses and SG&A have pushed earnings negative in most of Hims & Hers’ history, the company achieved positive operating income in Q4 for the first time. Providing generic drugs comes with minimal R&D expenses and high gross margins at 82.4% in Q1. The distribution relying on national partnership also makes Hims & Hers’ business model incredibly capital light, with minimal working capital and capital expenditure needs.
Hims & Hers targets for an adjusted EBITDA margin of 20-30% in the long term, up from 11.6% in Q1. The growing scale and high gross margins should aid Hims & Hers with operating leverage through marketing, G&A costs, and other fixed costs, making the considerably higher margin target very believable to achieve considering the gross margin level. Hims & Hers has already demonstrated a series of sequential improvements in the operating margin.
The target still leaves quite a wide range of possibilities with a wide 10 percentage point range, which seems to suggest that the growth potential and incremental marketing spend effectiveness is still unknown as Hims & Hers scales. The company doesn’t yet guide for any long-term revenue target.
The Business Relies on Building Brand Recognition
Selling generic drugs isn’t protected by a patent moat, and the space has quite a low barrier for entry — ultimately, Hims & Hers’ business relies on building a trusted brand and on good distribution capabilities to create growth.
The company’s marketing spend is also ultimately where Hims & Hers creates its competitive edge. Hims & Hers spent $446.4 million in marketing in 2023 alone, 51% of the year’s revenues, to attract customers and to drive the brand’s recognition. The marketing spends only increased further by $33.3 million in Q1.
I believe that Hims & Hers has succeeded in creating a well-respected brand, as the focus on initially especially taboo offerings in an ecommerce platform has turned out well. While the company offers generic medicine alternatives, the ecommerce platforms themselves have become a known brand, contrary to branded medicine manufacturers’ often recognized medicine-specific brands but less-recognized company names. Hims & Hers has become known for multiple medicine types under the same roof.
The marketing spend has only grown, but has already started to show improving economics – in Q1/2023, marketing costs were 51.0% of revenues, but only 46.9% in Q1/2024 as prior marketing’s achieved subscribers continue generating recurring revenues while Hims & Hers attracts new customers.
Hims & Hers could still face rising competition in the space eventually, with the brand building being the most notable competitive edge – many companies with the needed resources could compete in the incredibly capital light model business. The company’s main advantage is being a first mover in building such a brand, and the great position could still erode with time.
GLP-1 Medicine: Hims & Hers’ Latest Development in Product Launches
With the rise of Novo Nordisk’s (NVO) Ozempic drug for diabetes, largely used for general weight loss purposes, the GLP-1 market for weight loss drugs has quickly garnered attention. Novo Nordisk’s sales in Q1 alone in Diabetes and Obesity care reached around $8.9 billion (61.0b DKK).
Hims & Hers is also aiming for a share of the market’s success, as the company announced the commencement of the sale of generic GLP-1 medication alternatives in May at only a fraction of branded medication’s cost. The company already expects weight loss solutions to bring $100 million in revenues by 2025, acting as a major revenue catalyst in the coming years likely after 2025 as well.
While the GLP-1 medication adds incredible potential to the company’s growth, Hims & Hers’ generic version has been critiqued as less effective than the branded alternatives. Furthermore, the FDA hasn’t approved Hims & Hers’ GLP-1 medicine still — the growth market isn’t a very clear-cut win for the company yet.
The weight loss prescription is still just one of Hims & Hers’ many launches, as the company has rapidly expanded from just erectile dysfunction medication into minoxidil for hair loss and acne treatment in 2021, skin care in 2022. The company has only increased new products with multiple other launches throughout the years, especially in 2023 – although the GLP-1 addition seems to be one of Hims & Hers’ most high-potential single products, the growth doesn’t rely solely on the product.
Insider Sales
Despite the impressive growth performance, Hims & Hers’ insiders have been selling, with many insiders reported to have sold shares during July. The sales have been constant in the past year as multiple insiders continue lightening their position in the company.
While investors should note the large amount of insider sales and the lack of insider buys, I don’t necessarily believe that the sales are a notable sign of fundamental weakness. The sales have already been happening with the stock at a third of the current level, as the insiders seem to be deleveraging personal risks.
The Stock Valuation Should Still Have Room to Run
Hims & Hers’ historical valuation analysis is challenging due to the company’s only recent turn profitable, and the lack of very well comparative companies. Instead, as usual, I constructed a discounted cash flow [DCF] model to estimate a fair value for the stock.
I estimate the company’s growth to continue through the extensive marketing and new product launches, with especially the GLP-1 medicine ultimately continuing to convert into rapidly increasing recurring subscribers. After a 40% growth in 2024, I estimate the revenue growth to gradually slow down into a perpetual growth rate of 2.5% after 2033, representing a total CAGR of 16.0% from 2023 to 2033.
Operating leverage should drive great margin expansion. I estimate Hims & Hers’ EBIT margin to expand into an eventual 17.0% from growth, representing an adjusted EBITDA margin of around 25% — in Q1, the operating margin was 8.0 percentage points below the adjusted EBITDA margin, being used as the conversion. The high gross margins could even provide space for better margins, but I believe that a 17.0% margin is a fair baseline assumption.
Hims & Hers should have a great cash flow conversion going forward due to the very capital light business model. I estimate a 10% dilution to the current outstanding shares from the company’s notable share-based compensation.
DCF Model (Author’s Calculation)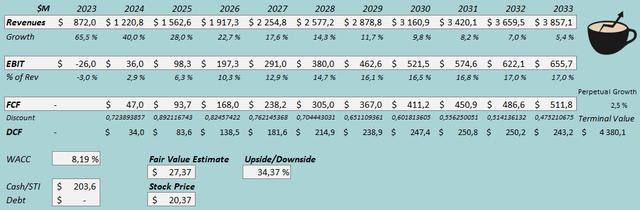
The estimates put Hims & Hers stock’s fair value at $27.37, 34% above the stock price at the time of writing. After the rally, I believe that the stock still has room to go further as great growth catalysts still exist and as margins are slowly improving.
CAPM
A weighted average cost of capital of 8.19% is used in the DCF model. The used WACC is derived from a capital asset pricing model:
CAPM (Author’s Calculation)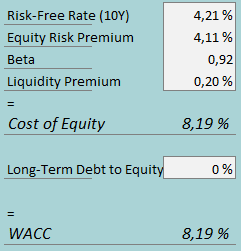
Hims & Hers doesn’t leverage any debt for now, and I estimate the equity-based capital strategy to continue far into the future. To estimate the cost of equity, I use the 10-year bond yield of 4.21% as the risk-free rate. The equity risk premium of 4.11% is Professor Aswath Damodaran’s estimate for the US, updated in July. Aswath Damodaran estimates the pharmaceutical drug industry’s unlevered beta at 0.92, which I believe to be the most representative of Hims & Hers’ operations. With a liquidity premium of 0.2%, the cost of equity stands and WACC stands at 8.19%.
Notable Risks Still Exist
The stock doesn’t come without risks. I believe that the most notable risk is Hims & Hers’ reliance on brand relevancy. The competitive position isn’t very well protected, and although being the first very notable brand in solely ecommerce medicine & health sales brings an advantage, the position could be threatened in the long term.
Furthermore, with the GLP-1 medicine being new, and with Hims & Hers’ generic offering not being approved by the FDA, the market’s potential could still shift to the downside, especially with Hims & Hers’ generic medicine being critiqued.
The continuous insider sales could also be a sign of a poor underlying fundamental factor, but I believe that such a risk is unlikely.
Takeaway
Hims & Hers has built an impressive growth story on the ecommerce medicine & health product platform. While the company sells generic medicine with a network of company partnerships, it has been able to build a unique brand around the offering that initially began on more taboo products. Marketing expenses continue to account for nearly half of total revenues, but with increasing operating leverage, the company has finally turned profitable from Q4/2023 forward on a GAAP basis as the strategy has paid off. Continuous new launches, especially in the growing GLP-1 market, are still a good long-term catalyst.
While the company’s story comes with risks as the generic medicine market comes with low competitive moats, the GLP-1 market being risky, and insiders continue selling shares, the stock seems attractive at the current price. As such, I initiate Hims & Hers Health, Inc. stock at a Buy rating.
Credit: Source link