
Kokkai Ng
Grab: Southeast Asia’s Leading Platform Company
Grab Holdings Limited (NASDAQ:GRAB) is a Singapore-headquartered platform company that operates a leading ride-hailing and delivery business. It also has a nascent fintech business, aiming to become Southeast Asia’s leading super-app platform. The company has managed to improve its profitability metrics markedly in the mobility segment, aligned to its medium-term adjusted EBITDA margin targets. Accordingly, Grab management underscored its confidence in maintaining the adjusted EBITDA margin of Grab’s mobility segment “at around 12% or higher.” Since mobility accounted for nearly 80% of Grab’s corporate adjusted EBITDA in the fourth quarter, it will continue to be a core earnings driver.
Despite that, observant investors should be cognizant that the GRAB fell steeply after its earnings release in late February 2024. While the Q4 performance was robust, as it demonstrated continuing operating leverage gains, the market was likely concerned with Grab’s forward guidance.
Accordingly, Grab articulated revenue guidance of between $2.7B and $2.75B for FY24. While it represents an estimated 14% to 17% YoY improvement, it’s a steep deceleration from 2023’s 65% growth. As a result, Grab’s growth cadence is expected to normalize to a mid-cycle momentum through FY25 before management expects topline growth to reaccelerate. Grab highlighted it projects “revenue acceleration from 2025 onwards as new initiatives gain traction.” Accordingly, the company will execute several growth initiatives across its delivery and fintech verticals. Grab believes these opportunities will help to “diversify its future growth” while allowing it to capture market share.
Grab’s Profitability Inflection Is Still Early
There’s little doubt that Grab is the market leader in the region in the mobility segment, as seen by its profitability inflection to sustain its core business. As a result, I believe Grab remains well-positioned to leverage its core mobility business to invest more aggressively in the food delivery and fintech segment to develop its moat against its smaller peers. Accordingly, Grab guided for an adjusted EBITDA of $190M at the midpoint of its outlook range for 2024, a significant improvement from 2023’s adjusted EBITDA loss of $22M. Analysts have confidence that Grab’s operating leverage should benefit from its growth and scaling initiatives, estimating an adjusted EBITDA CAGR of 95% through FY26 from its 2024 base.
However, execution risks abound as the delivery segment is, after all, a relatively low-margin segment compared to its mobility business. Grab management expects to deliver at least a 3% delivery segment adjusted EBITDA margin this year, with a medium-term midpoint target of about 4.5%. With Grab accounting for 55% of the region’s food delivery market by GMV in 2023, the company is well-positioned to scale. However, the potential margin upside seems limited, suggesting Grab may need to rely heavily on its fintech segment for growth. However, with the segment still nursing losses as it attempts to secure its foothold in an intensely competitive digital finance market, I believe the market is likely accounting for higher execution risks as Grab’s topline growth normalizes this year.
GRAB’s Valuation Isn’t Aggressive
GRAB Quant Grades (Seeking Alpha)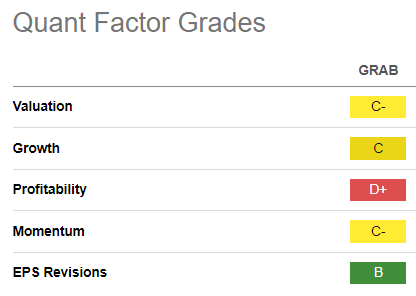
Seeking Alpha Quant assigns GRAB a “C-” valuation grade, suggesting a reasonable valuation. However, its “D” profitability grade might not provide sufficient confidence to value investors seeking a fundamentally strong company.
Despite that, investors must consider that its nearly 100% 2Y adjusted EBITDA CAGR offers substantial upside potential if management executes well. Its “B” earnings revisions grade suggests Grab management has likely sandbagged its previous guidance, helping the company to perform well relative to the market’s expectations. As a result, steep pullbacks in GRAB could be capitalized as dip-buying opportunities for investors with a speculative portfolio.
Is GRAB Stock A Buy, Sell, Or Hold?
GRAB price chart (weekly, medium-term) (TradingView)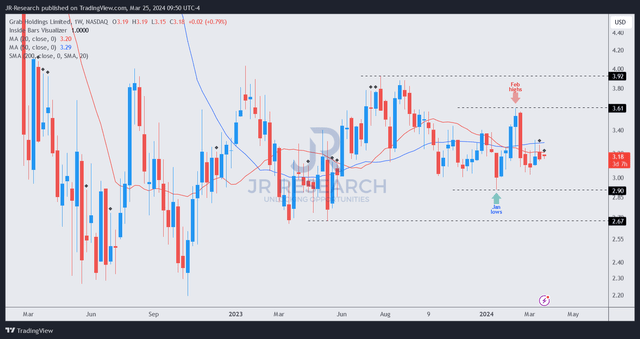
I assessed the market has remained tentative over GRAB’s buying sentiments. As a result, I believe the market isn’t convinced (yet) of the company’s ability to drive faster growth in its delivery and fintech businesses amid potentially slowing revenue growth projections.
Notwithstanding my caution, GRAB buyers have defended steep pullbacks over the past year, helping the stock consolidate constructively. In other words, the worst selling downside seems to be over, as buyers loaded up at solid dip-buying opportunities.
However, I caution investors to avoid chasing GRAB at critical resistance zones between the $3.6 and $4 levels. Buyers should consider buying closer to the $3 support level, leveraging GRAB’s accumulation zone.
Rating: Initiate Speculative Buy.
Speculative/Cautious Rating:
See the additional disclosure section below for important notes accompanying the Speculative/Cautious Buy rating presented.
I Want To Hear From You
Have constructive commentary to improve our thesis? Spotted a critical gap in our view? Saw something important that we didn’t? Agree or disagree? Comment below with the aim of helping everyone in the community to learn better!
Editor’s Note: This article covers one or more microcap stocks. Please be aware of the risks associated with these stocks.
Credit: Source link