
SweetBunFactory
Investment action
I recommended a hold rating for GLOBALFOUNDRIES, Inc. (NASDAQ:GFS) when I wrote about it the last time (Oct’23), as the semiconductor landscape was not favorable for GFS. Despite my belief that GFS is well positioned to be a leader in the field of quantum computing and AI chips, the near-term dynamics simply weren’t a good set-up to invest in the stock. Based on my current outlook and analysis of GFS, I recommend a hold rating. The near-term pressure continues to persist and is expected to last through 1Q24. Aside from the inventory situation, I am also concerned about customers transitioning towards lower nanometer chips (single digit), which could be a permanent loss in business as GFS does not provide those types of chips.
Review
My worries about the weak industry dynamic came true, as GFS continues to see headwind in its 4Q23 results (13 Feb 24). GFS reported revenue of $1.854 billion, down ~12% against 4Q22. While there were some strengths in Auto and Personal Computing, it was not enough to offset the pressure seen in Smart Mobile Devices, Home and Industrial IoT, and Communications Infrastructure and Data Center. The main problem is that most end markets are still dealing with an excess of inventory. Given the ongoing soft demand environment and customer inventory adjustments, management is expecting a slower recovery than initially predicted because excess customer inventories are taking longer to normalize. Hence, management is guiding for 1Q24 revenue to see another round of major decline (high-teens percentage decline) sequentially. As a result, gross profit is also expected to be 24% at the midpoint on lower utilization.
Apart from this near-term inventory surplus situation, I am also worried about the transition from the 12nanometer-16nanometer FinFET technology to <12nanometer will put further pressure on GFS performance. Management has mentioned that clients who have used GFS FinFET technology in the 16nm, 14nm, and 12nm ranges are currently transitioning to low nanometer chips, and this is a bad situation for GFS as they do not currently offer these products. So, while GFS can still rely on back-filling revenue in the near future as auto customers begin to integrate GFS into their new auto-compute chipset programs, I don’t think this volume ramp will be enough to make up for lost shipments from existing customer programs in the medium to long term. The competitive threat to GFS is intensified when we consider that TSMC is expanding its manufacturing capabilities outside of Taiwan, in countries like Japan and Germany. As technology advances towards chips with fewer nanometers in size, GFS may play an increasingly smaller role in the value chain.
And then that second question, you type it through in there on the FinFET moving out. We reported earlier that, yes, in these downturns, this is when customers move more quickly and some of our technology in our FinFET 12 nanometer was getting displaced by going to single-digit nanometer. 4Q23 call
On the other hand, the news that GFS could receive $1.5 billion in direct funding as a component of the CHIPS Act is encouraging news that will help the company grow in the long run. On top of that, GFS received an additional $600 million in financing from the state of New York. Grants and programs at the federal and state levels will help GFS increase its investments, which will allow it to build a new factory on the same campus and expand its current one, tripling its production capacity in ten years. The money will reportedly go toward updating the Essex Vermont fab, which is owned by GFS. The CHIPS Act and the New York funding will, in my opinion, help GFS become more profitable in the long run by allowing them to take advantage of geopolitical trends toward dependable, localized capacity as well as semi-sector-wide trends that demand more lagging-edge capacity for markets like the automotive, internet of things [IoT], defense, and automotive industries. So, even if GFS does not penetrate the single-digit nanometer space, with its expanded capacity, it will be able to capture share, and they can do this aggressively since the cost of capital is basically “free” (funded by the government).
All in all, in the near-term, management’s approach is likely to focus on resolving the inventory situation, and to monitor this, we simply need to look at inventory days and inventory as a percentage to sales. As for the longer-term risk (Fabs moving outside of Taiwan), how management will utilize the government funding to maintain its competitive position is something to continuously monitor too.
Valuation
Author’s work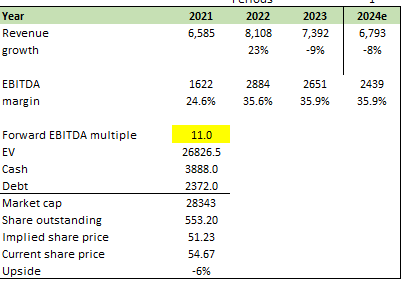
The pressure seen by GFS is worse than I expected; as such, I am revising my growth assumption downwards to a high-single-digit revenue decline in FY24 (I assumed 14% growth in FY24). This 8% is benchmarked against consensus estimates, so I am not being overly conservative. That said, I gave GFS the benefit of doubt that they are able to manage costs; hence, the EBITDA margin is not expected to go down (I assumed flat). Overall, the upside remains unattractive, even if I were to assume GFS to trade at 11x forward EBITDA, the high end of its valuation range. Because of the uncertainty in the timing of recovery, I don’t think the market will start to value GFS based on its FY25 expected performance yet. The market is likely to be in wait-and-see mode now as they await results to show that 1Q24 is indeed the trough the management is calling for.
Final thoughts
My recommendation is to maintain a hold rating. The persistent inventory surplus, coupled with customer transitions to lower nanometer chips, raises concerns about sustained business losses. The shift to <12 nanometer technology may also further impact GFS’s performance. However, positive aspects include potential financial support from the CHIPS Act and additional funding from New York state, enabling GFS to expand and update facilities. My take currently is that the market is adopting a wait-and-see approach, and until clearer signs of recovery emerge, the upside for GFS remains unattractive, warranting a hold recommendation.
Credit: Source link