HJBC
Shares of Equitable Holdings (NYSE:EQH) have been an excellent performer over the past year, rising about 75% as buoyant financial markets, elevated interest rates, and a favorable business mix shift have enhanced the company’s profitability. I last covered EQH in December, rating shares a “buy,” and since that recommendation the stock has rallied about 25%, more than 10% above the market’s return. Shares have also eclipsed my $36 price target, making now an opportune time to revisit shares. I remain bullish.
Seeking Alpha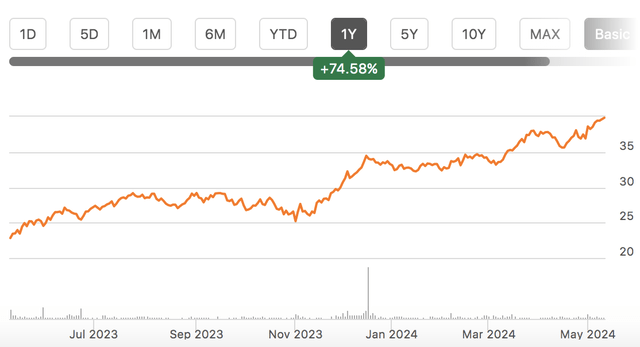
On April 30th, Equitable reported Q1 earnings, and it was another solid quarter. EQH earned $1.43, beating consensus by $0.11; this was up 18% from last year, above its target for 12-15% growth through 2027. Operating earnings were $491 million from $456 million last year, as the company benefits from a favorable interest rate environment, earning wider spreads on the annuities and insurance product sales.
The majority of its earnings comes from its annuities division, which is broken into two components. Retirement fee income rose by 8% to $411 million as Equitable benefits from higher account values on which it charges fees. Overall, retirement sales and deposits were up 42% from last year. Retirement organic growth was 5% in Q1, driven by record index-linked annuity net inflows. With interest rates being higher and equity markets also at elevated levels, many investors are finding now to be an opportune time to roll some retirement funds into an annuity to lock in much of their equity gains and earn a more attractive yield than several years ago.
This has created a favorable sales dynamic. This fact has accelerated the change in EQH’s book of business as it now is selling less risky, registered index-linked annuities (RILA), where it is capturing a spread on what investments it buys vs the yield it pays out. This spread business should have less volatile earnings than legacy variable annuities, and it anticipates a 15% internal rate of return on RILAs.
Digging deeper into results, individual retirement is its biggest unit, driving 39% of profits in Q1. Spread income rose to $259 million from $206 million, and as a result, operating earnings rose by 12% to $229 million. Account values rose by 25% to $98.3 billion. Account values have been boosted by the strong pace of sales as well as increases in markets, which have lifted values. As you can see below, individual retirement inflows and outflows are both rising. Rising inflows is due to the elevated level of sales. Higher outflows have two drivers. First, a growing book of business naturally means more payments each month to annuity holders. Additionally, policyholders can at certain points surrender their policies, releasing EQH of its liability and receiving a cash payment (typically with a penalty relative to its true economic value). With many policies written when rates were lower, surrenders have increased across the industry, as policyholders take back low-yield annuities and buy new ones with higher yields.
Equitable Holdings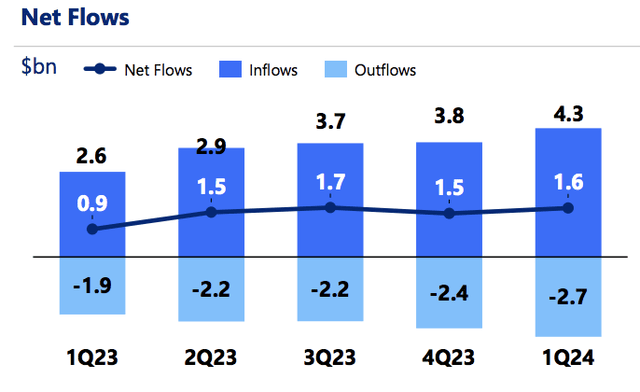
In fact, some of these flows are linked with EQH seeing many policyholders buying a new EQH policy after surrendering an old one, driving both an inflow and outflow. I view this trend as having both positives and negatives. On the positive side, surrenders typically lead to a profit, given the implied penalty vs the liability, and they free up capital to support new sales. On the other hand, new annuities tend to have higher funding costs. Still, given the demand for annuities, the spread environment has been favorable, though over time management expects spread income to rise with RILA annuity growth after a period of spread expansion the past year.
Group retirement contributed 21% of profits in Q1, and spread income jumped an even stronger 48% from $61 to $90 million; this unit’s alternative investments are focused more in private equity, which was favorable in the quarter. Operating earnings rose to $124 from $97 million as its fee income rose. Accounts values rose by 15% to $38.5 billion. This was slower than individual retirement because flows are less strong, given a larger existing franchise. Indeed, it saw $132 million of outflows, consistent with the pace over the past year. Its K-12 education platform saw $18 million of inflows, and it continues to have a leading presence providing teachers with annuities.
While these are its primary insurance units, its protection solutions (life insurance) business earned $46 million from an adjusted $47 million last year. Alternatives were a $6 million headwind. Mortality continues to improve after COVID-related pressures, which should support stable to rising earnings over time. While it sells simpler annuities now, Equitable used to sell variable annuities, which caused problems across the industry after the financial crisis. These are housed in its run-off Legacy unit where earnings declined to $52 million from $64 million. There were $659 million of outflows and an 8% drop in policy count. It is not selling products here, so declines will continue at a $2-3 billion pace, making this unit less and less relevant to earnings over time.
Aside from insurance, Wealth management accounts for 7% of profits. Advisory fees rose by 18% to $150 million, given the strength in markets. This was a bit slower than the 22% jump in assets under advisement, given ongoing fee pressure. Still, revenue per advisor rose by 11%, and given the limited variable costs, there are strong incremental margins, so operating margins expanded 180bp to 13.7%. Accordingly, operating earnings rose by a third to $43 million. There was a $200 million outflow, but this was because an advisor team was acquired by another firm, and this should be a one-time headwind..
In addition, Equitable also owns about 62% of AllianceBernstein (AB). While results are consolidated, I also believe it is best to exclude earnings of a separate entity that is publicly traded and instead value it based on the current equity value. With where AB is trading, that stake is worth about $2.3 billion today or $7/share for EQH. I would note AB did have $3.7 billion of net active inflows in Q1, a strong performance.
Thanks to higher rates, EQH deployed new money at a yield of 6.2% in Q1, 140bps accretive to the portfolio average. Its portfolio is fairly conservative with an A2 average rating. 97% is investment grade. About 18% is in mortgages, which is an area I am focused on given pressures facing commercial real estate. However, its underwriting is conservative. Commercial mortgages have a 66% loan-to-value and more than 2x interest coverage ratio. As such, occupancies and property values would both have to worsen materially before EQH faces losses. I would continue to monitor this part of the portfolio but view risks as manageable.
Equitable Holdings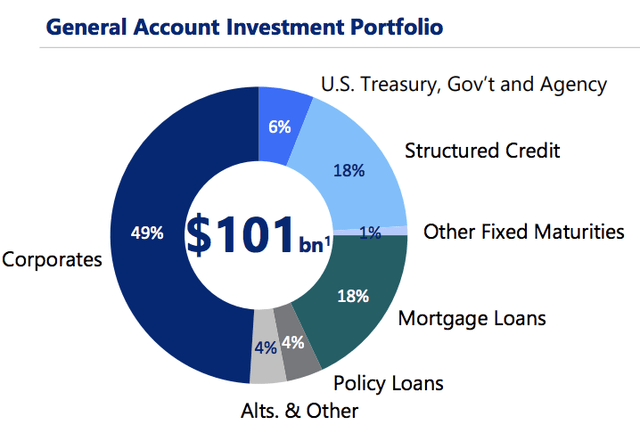
One area of weakness was that alternatives returned 5.8% in Q1 vs its 8-12% target. It expects about 6% in Q2 as well. Performance tends to lag public markets by a quarter, so EQH should have good visibility into likely Q2 returns. For the full year, it expects to just undershoot the 8-12% target, implying a 9-10% H2 return. Within alternatives, equity real estate investment weakness is offsetting gains in private equity. In Q1, private equity rose by 9.5% while real estate fell 5% after an 11% drop last year. EQH has generated a 10% return since 2013 in alts. However, returns have been lumpy, and if not for 2021, returns would be a bit below target the past decade. Given real estate pressures, I see risks that returns do not accelerate as much in H2 as hoped.
Equitable Holdings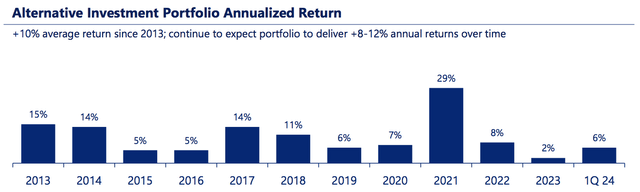
Still even with slightly lower returns here, EQH is very profitable and cash generative. It anticipates $1.4-1.5 billion of cash generation this year and targets $2 billion by 2027. It aims to pay out 60-70% of earnings, and its 66% payout in Q1 was right in-line with this target. It did $253 million of buybacks, and its share count is down by 9% over the past year. Alongside earnings, it announced an intent to raise its dividend to $0.24 from $0.22, giving shares a 2.4% yield.
EQH has a strong balance sheet enabling capital returns with a 31% debt to capitalization, including AB’s consolidated financials. The EQH holding company (the entity that does buybacks) is very well capitalized. It has $1.9 billion of liquid assets, well above its $500 million minimum target. That provides ample breathing room for insurance entities to retain capital to support growth as well as maintain this pace of buybacks. Management also said M&A is not accretive relative to buybacks, and so I do not expect any large transactions.
EQH has an 11% distribution yield, assuming it allocates all cash flow to dividends and buybacks as I expect. I continue to view this as attractive, and ongoing share count declines should support further upside. Additionally, as its legacy unit declines and consumes less capital, I do believe management’s target of increased cash generation is plausible, which will support ongoing increases in distributable cash flow. With legacy becoming a smaller piece of the pie, I do believe shares should trade at no more than a 10% distribution yield, as its buybacks/dividends should grow, and so this provides a safe cushion to double-digit medium term returns. With the share count likely to fall at least 8% more over the next year, that can push shares to the $46-48 area, providing about 20% upside. Given its fee revenue and legacy units have exposure to equity markets, prolonged downturns could weigh on EQH shares. But with its spread business growing, this sensitivity should continue to decline over time. As such, I view the risk/reward compelling and reiterate EQH as a buy even after its outperformance.
Credit: Source link