Tom Werner
Summary
Following my coverage on Envista (NYSE:NVST) in Feb’24, which I downgraded to a hold rating given the visible headwinds that I believed would impact margins in the near term, along with the poor macro conditions that continued to pressure growth, this post is to provide an update on my thoughts on the business and stock. I wouldn’t say that my recommendation for a hold is correct, but shifting away from a buy rating was the right recommendation as the stock price drifted down by ~20% since Feb. I remain hold-rated for NVST stock as I do not see any positive catalysts that will drive the near-term growth and share price upwards.
Investment thesis
On 1 May 2024, NVST released its 1Q24 earnings, which saw organic revenue growth of 0.4% to $624 million (-0.6% on a reported basis). By segment, Equipment & Consumables organic revenue fell 0.2%, and Specialty and Technology products organic revenue grew 0.8%. Gross profit of $358 million (a 57.4% margin that is down 70bps), which led to adj. EBITDA of $87.2 million and underperforming street estimates of $97.5 million. On adj EBITDA margin, it was down 420bps y/y to 14%, missing street expectations by 120bps. Overall, adj EPS declined by ~31% to $0.26, also missing the street expectation of $0.315.
Own calculation
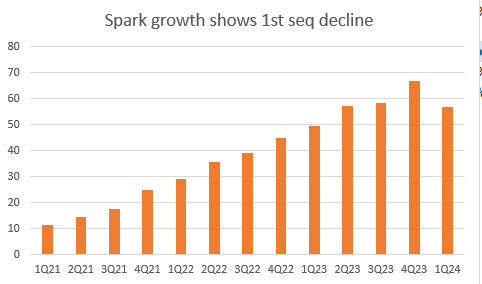
Growth headwinds remain apparent for NVST, and I don’t see any positive catalysts that would drive growth up in the near-term. Even the expected growth driver – Spark – saw growth deceleration in 1Q24. In the quarter, Spark grew 15% y/y to $57 million, but this marked the first sequential decline in Spark growth since launch. Although management did point to double-digit sequential growth in active doctors in 1Q24 to show that demand remained strong, this suggests to me one of two things that are not setting up a good demand outlook for NVST at the moment:
- NVST is facing pricing headwinds for this product. Doing the math, Spark saw a 15% sequential decline in revenue growth. Assuming the “double digits” of sequential active doctors referred to by management are ~10%, this implies a potential pricing headwind of 25%. I admit that this number is not precise, but my point is that NVST seems to be facing pricing headwinds, and in order to keep growing volume, they may need to keep prices low, which is a margin headwind.
- The conversion rates of active doctors to cases ordered have slowed. I am unsure why this is the case, given that the “Spark growth model” is not a new model that management just implemented.
During the quarter, we saw over 15% growth in Spark with double digit sequential growth in the number of active doctors. Our growth remains widespread, with robust progress both in North America and Europe, as well as rapid growth in our emerging markets. 1Q24 earnings call
This comes at a time when management remains steadfast in investing to improve margins, and I think this is a good long-term maneuver (using automation to reduce cost per case), but I remain concerned that a poor demand outlook and a step-up in investments would put further pressure on margins in the near term. We have seen how this played out in 1Q24, where NVST missed the street’s EBITDA estimates by 10%.
Implants also continue to decline against a challenging backdrop. In the quarter, implants declined by low single-digits, following the same trend as in 2H23, showing no signs of improvement. The main region that saw weakness was in North America, for high-end procedures. My view is that the macro environment has played a part in this demand weakness, as consumers delay any of such procedures for as long as they can. This demand weakness is also in line with what Straumann Holding’s management said in their 1Q24 earnings call.
Now, as expressed also in the past quarter’s communication, those high-interest rates have impacted patient spending and as a consequence, have reduced patient demand. First, for large full-arch reconstruction as also I think we have been commenting on a regular basis since the second quarter last year, but we have now also seen through our customers, who we have a lot of, of course, communication and exchanges, that it has reduced some patient demand for smaller indications. And this is where we have seen then that the market overall dynamic has been then slowing down. Straumann Holding 1Q24 earnings call
To counter this demand weakness, management’s strategy is to add more people (60) to its commercial and field support to improve customer experience and clinical training, and expect a return to market growth in North America by the end of this year. I believe this is too optimistic. Looking at the current macro situation, even though inflation has shown positive development in the latest April data, rates have not moved down yet. As such, I continue to expect consumers to delay their procedures until they are confident that the economy is recovering and their wallets are not going to face pressure from high rates. In addition, competitor Dentsply Sirona (XRAY) is also stepping up investments on this front. Overall, with the macro weakness continuing to pressure demand, along with a step-up in hiring and competitive pressure, I expect NVST to continue seeing weak growth plus near-term margin pressure.
We are ramping our investment in treatment planning, clinical support and sales. XRAY 4Q23 earnings call
Valuation/Guidance
My view on valuation tracks similarly to my last update (note I did not put out a price target as I had no confidence in making any key assumptions back then).
The lack of clarity on guidance was incrementally disappointing. While I understand this may be due to the leadership transition, I believe it is a negative message to the market that management lacks confidence in the near-term demand outlook. While NVST’s current valuation at 14x forward PE represents a discount to its historical trading average of 19x forward PE, I don’t see any strong, visible catalysts that will drive the share price upwards.
Nonetheless, in this post, I attempt to derive a price target. NVST used to have a good track record of beating consensus EPS estimates before 4Q22, but this track record has flipped to consecutive misses for the past 3 quarters (miss by 6% in 3Q23, 14.4% in 4Q23, and 17.5% in 1Q24). Giving NVST the benefit of doubt that they can achieve consensus FY24 estimates of 1.24 (the market has already downgraded their EPS estimates to reflect the outlook), and at 14x forward PE, this implies a share price of $17.36 (~6% lower than the current share price).
My expectation for how things will play out moving ahead is that near-term growth to remain pressured until the macroeconomic environment recovers. Meanwhile, reinvestment into the business is unlikely to see any slowdown, and this will put pressure on margins. Put together, NVST is likely to see near-term earnings pressure until such time when the macro environment sees a recovery.
Risk
Upside earnings will likely come from an earlier-than-expected macro recovery, which gives the Fed more confidence in lowering rates. This will definitely have a positive impact on consumer demand. Management’s investments in automation for Spark could see benefits faster than expected as well, thereby supporting margins despite a poor demand outlook.
Conclusion
In conclusion, I am maintaining a hold rating for NVST. The lack of positive catalysts, sluggish growth, and margin pressure paint a negative outlook for the near term. While management remains optimistic about the Spark product line and a North American rebound, I am skeptical given the current macroeconomic headwinds and competitive landscape. The absence of clear guidance further reinforces my cautious stance. Even though the valuation seems attractive, I would wait for a clearer demand outlook or a more positive catalyst before considering an upgrade.
Credit: Source link