
Thomas Barwick
I published my ‘Strong Buy’ thesis for Emerson (NYSE:EMR) in May 2024, indicating the company’s transition into a stronger growth industrial technology company with a focus on software, control, sustainability, decarbonization and energy transitions. The company released its Q3 result on August 7, showing only 3% organic revenue and order growth. The stock price took a hit after the earnings due to the weakness in maintenance, repair, and operations (“MRO”) and discrete automation orders. However, I think these issues are short-term challenges, and I am buying into the weakness. I reiterate a ‘Strong Buy’ rating with a one-year target price of $140 per share.
Weak MRO and Discrete Automation
Over the earnings call, the management highlighted the softness in the MRO and discrete automation markets. The management expects a slow recovery in the discrete automation market, particularly in factory automation, with flat to slightly positive growth anticipated in Q4.
As a result, Emerson delivered only 3% organic revenue and order growth, as illustrated in the chart below. It represents a deceleration in their organic revenue growth compared to the past few quarters.
Emerson Quarterly Earnings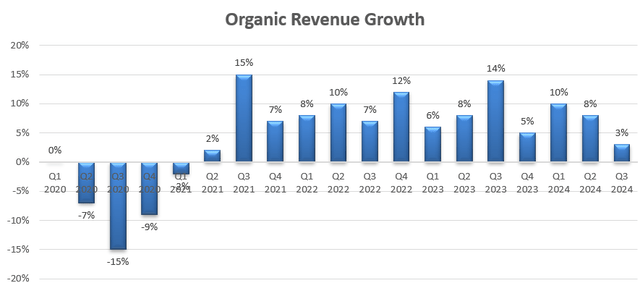
The reasons for the weak order growth can be summarized as follows:
- Over the earnings call, the management indicated that the current high-interest rate has caused some delays in some general industrial projects, resulting in weak demands for discrete automation and MRO. As shown in the table below, the manufacturing production has been quite weak in 2024 due to the current high-interest rate environment.
Federal Reserve Bank of St. Louis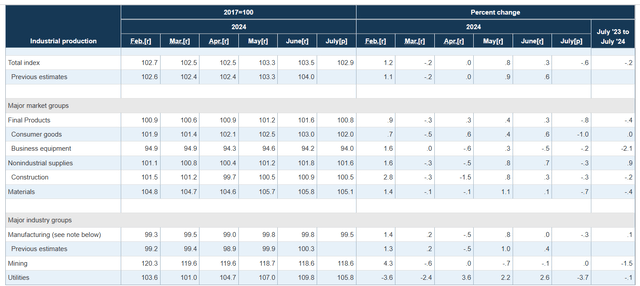
- Automotive is an important end-market for Emerson. The auto production has experienced a year-over-year decline in 2024 due to the weak consumer consumption environment. This decline in the automotive market has created growth challenges for Emerson’s discrete automation and test & measurement portfolios.
FRED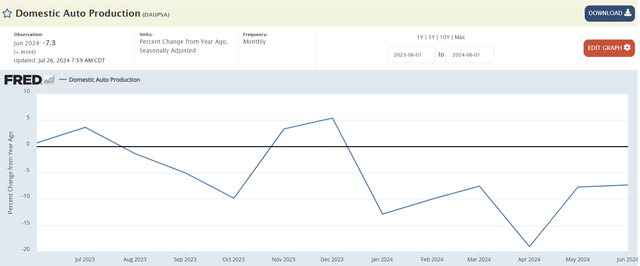
Growth Projection and Valuation
Emerson guides for 6% organic revenue growth, and 9.5% acquisition growth for FY24, as detailed in the slide below.
Emerson Investor Presentation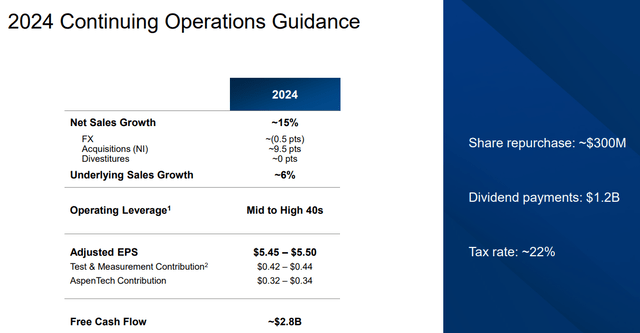
I am considering the following factors for FY24’s growth:
- Intelligent Devices: As discrete automation represents around 20% of total Intelligent Devices revenue, the weakness in general industrial market is expected to create some growth headwinds for the segment in FY24. I forecast Discrete Automation revenue will decline by 1% in FY24, while other businesses including Final Control, Safety & Productivity and Measurement & Analytical will grow by 6%. Thus, I anticipate the Intelligent Devices segment will grow by 4.6% in FY24.
- Software & Control: As indicated in my previous article, Emerson has been expanding into software, services and control systems, which will generate recurring revenue for the company. I forecast the business will grow by 10% in FY24.
Combining the two segments, I estimate Emerson will achieve 6% organic revenue growth in FY24. For the growth rate from FY25 onwards, I assume the intelligent devices business will recover to its historical 6% growth rate, while Software & Control will increase by 10%. Therefore, the overall growth rate is estimated to be 7% from FY25 onwards.
On the margin side, I assume 20bps annual margin expansion driven by:
- 10bps from gross profits due to new product launches
- 10bps from SG&A operating leverage
The DCF summary:
Emerson DCF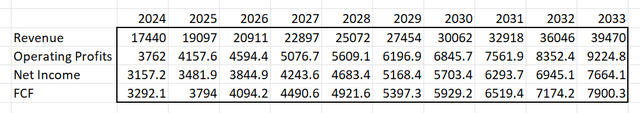
I calculate the free cash flow from equity as follows:
Emerson DCF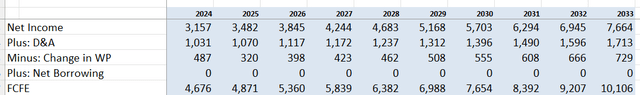
The cost of equity is calculated to be 10% assuming: risk free rate 3.8% (US 10Y Treasury Yield); beta 0.98; equity risk premium 7%. The one-year target price is calculated to be $140 per share discounting all the future FCFE, as per my estimates.
Key Risk
Over the earnings call, the management highlighted the weakness in China, which has impacted Emerson’s Test & Measurement business. The management lacks the visibility regarding the recovery of their business in China. In the next quarter, Emerson will provide guidance for FY25, and I expect that they will offer cautious guidance for their China business for FY25, which may concern the market.
End Notes
The current high-interest rates and weak automotive market have created some growth challenges for Emerson in the near term. In my view, the discrete automation and MRO businesses will recover when the economy and interest rates begin to moderate. I reiterate my ‘Strong Buy’ rating with a one-year target price of $140 per share.
Credit: Source link