Photon-Photos
The Q1 earnings season for gold miners (GDX) has finally begun and results have started to trickle out from the larger producers. One of the more recent names to release its results was Eldorado Gold (NYSE:EGO), a mid-tier producing aiming to grow to ~800,000 gold equivalent ounces [GEOs] later this decade once its Skouries Project moves into commercial production by mid-2026. This will elevate the company above its mid-tier peer group with the addition of a large-scale and low-cost asset and further diversify the company away from Turkiye where it has two of four operations currently. In this update, we’ll dig into the Q1 results and look at its valuation vs. peers following a year of outperformance.
Olympias Drill Core – Company Website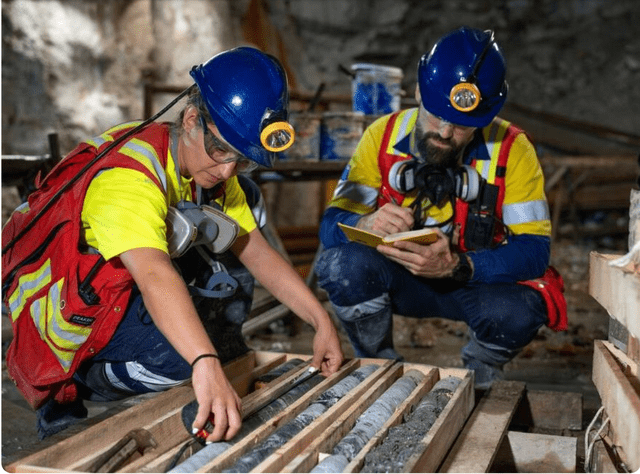
Eldorado Gold Q1 Production & Sales
Eldorado Gold released its Q1 results last week, reporting quarterly production of ~117,100 ounces of gold, a 5% increase from the year-ago period. The increased production was driven by a much stronger start to the year from its Lamaque Complex in Quebec (+12% year-over-year), where Q1 is typically its weakest quarter, and a better quarter from Olympias (+6% year-over-year), which is in the process of turning around. And while Kisladag had a slow start at just ~37,500 ounces but did so at industry-leading costs and the remainder of the year will be much stronger with implied average quarterly production of ~50,000 ounces (guidance mid-point). Let’s dig into the results below.
Eldorado Gold Quarterly Gold Production – Company Filings, Author’s Chart Lamaque Quarterly Production & Q1 – Company Filings, Author’s Chart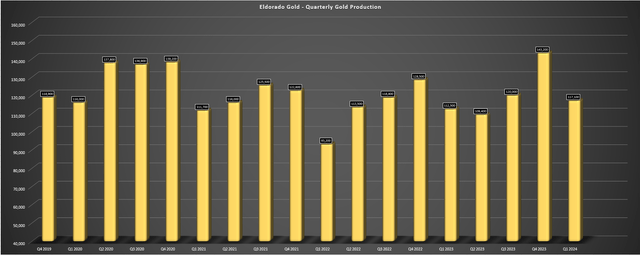
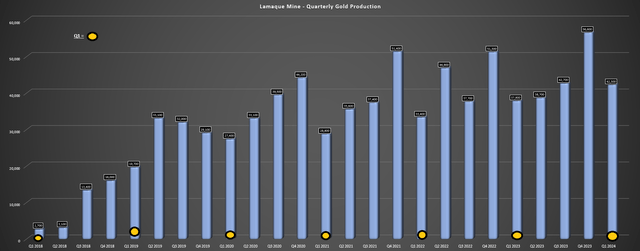
Starting with Canada, Lamaque benefited from higher throughput of ~234,600 tonnes in Q1 2024, more than offsetting the lower grades (5.81 grams per tonne of gold vs. 6.06 grams per tonne of gold) and lower recoveries in the period. The increased throughput was related to better mill utilization and the ability to process stockpiled ore, and all-in sustaining costs of $1,262/oz were up year-over-year but benefited from higher ounces sold (~44,600 ounces vs. ~38,600 ounces) which mostly offset the higher sustaining capital in the period (equipment rebuilds, underground development). According to Eldorado, grades are expected to improve in Q2 at Lamaque, setting up significant margin expansion when combined with the higher gold price.
As for Kisladag in Turkiye, production was ~37,500 ounces, up marginally year-over-year, but at industry-leading costs of $916/oz (Q1 2023: $875/oz). The lower production in Q1 was related to slower leach conditions in the winter months, which is not unusual for this asset, and higher grades stacked on the heap leach pads (0.77 grams per tonne of gold) were partially offset by fewer tonnes stacked. According to the company, this was due to planned maintenance and work in the crushing circuit. On a positive note, the mine has held costs well below its peer average with the benefit of optimization work in the past two years and a depreciating Turkish Lira and its relatively low sustaining capital relative to other operations of its scale.
Kisladag Operations – Google Earth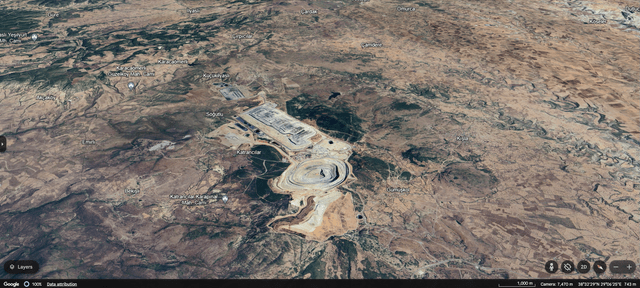
Finally, Efemcukuru and Olympias combined for ~37,300 ounces in Q1, with the lower production at Efemcukuru offset by higher production at Olympias (~18,800 ounces vs. ~16,500 ounces). The increased production at Olympias was related to a much higher throughput rate with ~118,600 tonnes milled at slightly higher gold grades, offset by lower recovery rates. Eldorado noted that this was related to productivity improvements which have been underway for the past year, with the ultimate goal being to increase throughput to ~650,000 tonnes per annum or ~40% from Q1 run rate levels. Meanwhile, the company expects better production and should see improved cost performance in H2 with increased by-product credits with mining moving into the Flats Zone which carries higher base metals grades than what it’s processing currently (Flats M&I grade: ~4.8% lead and ~6.6% zinc vs. ~3.6% lead and ~4.0% zinc in most recent quarter).
Eldorado Gold Quarterly Revenue – Company Filings, Author’s Chart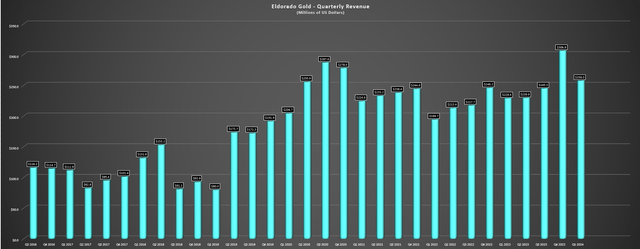
Overall, Eldorado had a solid start to the year, and while Q1 production is tracking behind its FY2024 guidance midpoint of 530,000 ounces (22% in Q1), this was largely expected with gold production set to be back-end weighted this year. Plus, while this will be the lightest quarter of the year, the financial results certainly didn’t disappoint with the benefit of a higher gold price, as evidenced by Eldorado’s revenue improving 13% year-over-year to ~$258.0 million while operating cash flow soared to $95.3 million (+132% year-over-year).
And while free cash flow was negative because of Skouries spend ($52.5 million, and $122.0 million in total capex), the free cash outlook is looking much better in what will be a busy year for construction at Skouries with expected growth capital of ~$400 million and a consolidated capex profile for Eldorado Gold of ~$680 million in FY2024. In fact, free cash flow outflows could come in below $190 million this year assuming a $2,225/oz gold price (which looks like it could be conservative), significantly better than the ~$260 million cash outflow I was expecting as of Q4 2023 based on a more conservative $2,050/oz gold price. Hence, even during a heavy build phase, Eldorado will maintain a solid balance sheet with its net debt of just ~$150 million at the end of Q1.
Costs & Margins
Looking at costs and margins, we saw a significant improvement in Q1 2024, with all-in sustaining costs [AISC] only up 5% year-over-year to $1,262/oz (Q1 2023: $1,207/oz), which was more than offset by the higher average realized gold price of $2,086/oz. The result was that margins surged to ~39.5% ($824/oz) vs. ~37.5% ($725/oz) in Q1 2023, but the Q1 results do not reflect the significant follow through in the gold price from its breakout that occurred late in the quarter. In addition, the company’s Q2 results will benefit from a delayed shipment in Q1 that resulted in slightly higher AISC at Olympias and higher production across the peer group. Hence, even using conservative assumptions of $1,240/oz AISC in Q2 and a $2,240/oz gold price, AISC margins could jump another 23% sequentially (Q2 2024 vs. Q1 2024) to ~$1,000/oz. And on a year-over-year basis, this would translate to 53% growth.
Eldorado Gold – All-in Sustaining Costs & AISC Margins – Company Filings, Author’s Chart Eldorado Gold Annual AISC Margins & 2024 Estimates – Company Filings, Author’s Chart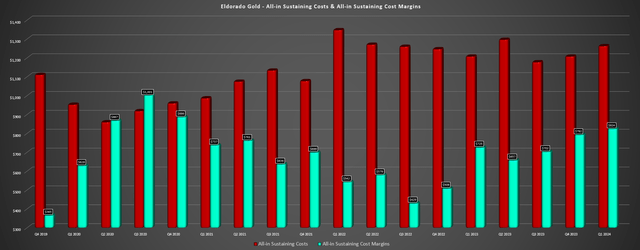
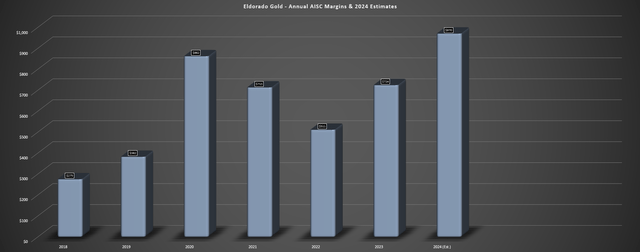
As for the annual AISC margin outlook, we could see AISC improve to ~$970/oz this year assuming a $2,240/oz gold price and $1,270/oz AISC. This would represent the best margin performance since 2020, with margins only slightly behind FY2020 levels at ~43.3% vs. ~48.4% in FY2020. As for commentary on costs, Eldorado noted that cost increases were related to higher royalties, labor costs, and consumables, with an impact on royalties from sliding scale royalties at Olympias and Efemcukuru. This includes a much higher royalty rate of 18.75% above $2,101/oz gold at Efemcukuru, higher than the previous royalty structure that it benefited from in 2020 with rates between below 15% at $1,800/oz to $2,100/oz gold when the metal saw its spike in mid-2020.
Efemcukuru (Previous Royalty Structure – Left, Current – Right) – Efemcukuru Technical Report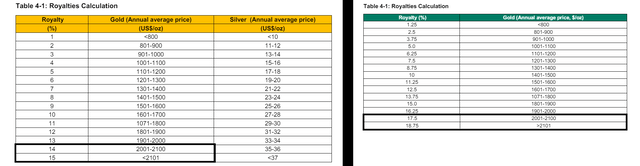
Recent Developments & Three-Year Outlook
Moving to recent developments, the major development worth discussing is Skouries, a massive gold-copper asset in Greece which is looking even better at $2,200/oz gold and $4.50/lb copper vs. the assumptions that went into the 2021 study at $1,500/oz gold and $3.85/lb copper. And while we have seen significant inflation since then, the project did benefit from construction already being partially complete before it was halted in 2015. As it stands, the overall project is 73% complete, engineering is just shy of 70% complete and ~$240 million of $920 million in total capex has been spent, up from a previous estimate of $845 million. And while there’s still significant expenditures left that will result in negative free cash flow for Eldorado in 2024 and 2025, Eldorado will morph into a cash cow in 2026, with the potential to generate upwards of $550 million in free cash flow even assuming no further upside in the gold price and that it averages only $2,250/oz.
Eldorado Gold Annual Revenue, Free Cash Flow & Forward Outlook – Company Filings, Author’s Chart & Estimates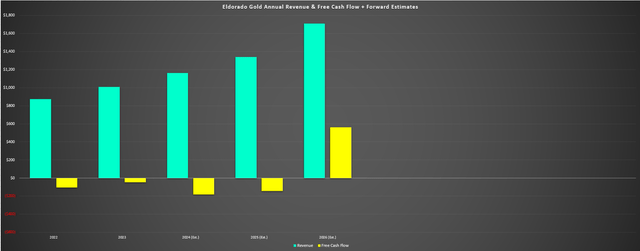
Valuation
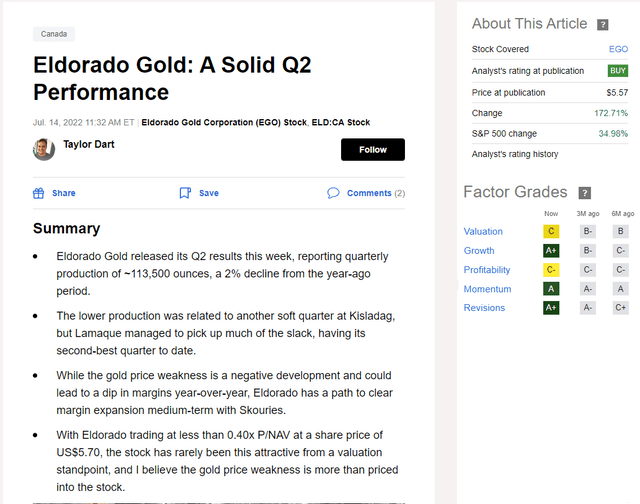
Based on ~209 million fully diluted shares and a share price of US$15.60, Eldorado Gold trades at a market cap of ~$3.26 billion and an enterprise value of ~$3.41 billion. This makes it one of the higher market cap names in the mid-tier producer space currently, with it trailing only Lundin Gold (OTCQX:LUGDF), Alamos Gold (AGI), and Evolution Mining (OTCPK:CAHPF). However, Alamos Gold has a path to ~950,000 ounces of gold later this decade based on its current pipeline, Evolution Mining is a solely Tier-1 jurisdiction producer which affords it a premium valuation and Lundin Mining may be a single-asset company, but it’s the sector’s lowest-cost producer among the 500,000+ ounce producer space. And with Eldorado now trading at closer to 0.90x P/NAV (6% discount rate), it’s hard to argue for the stock offering a margin of safety vs. when I highlighted the stock as a Buy below US$5.00 per share in Q3 2022 when it traded below 0.50x P/NAV.
Eldorado Gold EV/EBITDA Multiple & Margins/Valuation vs. Peers – FinBox, TIKR EGO Buy Rating Q3 2022 – Seeking Alpha Premium/PRO 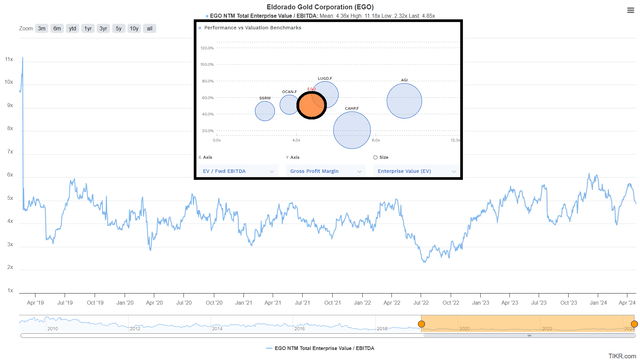
So, what’s a fair value for the stock?
Using what I believe to be fair multiples of 1.0x P/NAV and 6.0x FY2024 P/CF and a 65/35 weighting to P/NAV vs. P/CF given that it’s primarily non-Tier 1 jurisdictions offset by an attractive organic growth, I see a fair value for Eldorado Gold of US$18.00. This points to a fair value of US$17.80 or a 14% upside from current levels. And while this fair value estimate suggests EGO could make a run at its 2017 highs before its waterfall decline following the Lamaque acquisition, I don’t see nearly enough of a margin of safety at current levels. That said, EGO is quickly growing into its valuation, especially with a further increase in cash flow per share expected in FY2025 with estimates of ~US$2.80.
Some investors might argue that the current outlook doesn’t factor in the surge in free cash flow coming from Skouries in 2026 and Eldorado is certainly set to hit significant inflection point for free cash flow as Skouries capex winds down in late 2025. However, I prefer to buy names that are hated and trading at massive discounts to fair value with extremely low expectations, and while EGO fit this bill in mid-2022, I think there are far more attractive names out there today that are trading at higher free cash flow yields, much deeper discounts to NAV and in B2Gold’s (BTG) case, also paying a ~6.2% dividend yield. So, for contrarian investors looking for to put new capital to work in the gold sector, I see B2Gold as the superior opportunity today at US$2.60. This is especially true given that B2Gold has a glowing track record of per share growth, beating out over 95% of its major and mid-tier peers, including EGO.
B2Gold Annual Gold Production, Year-End Shares & Production Growth Per Share – Company Filings, Author’s Chart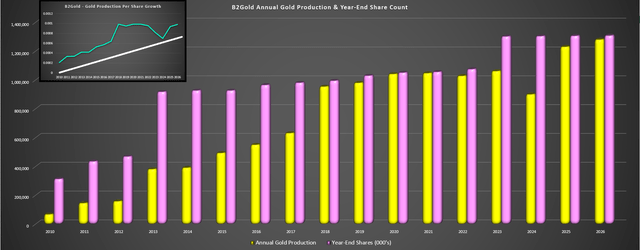
B2Gold’s impressive track record of production growth per share is evidenced by the chart above, with gold production per share growing ~5x from 2010 to 2018 and set to remain near-record highs after adding one of the best undeveloped projects that has improved its jurisdictional profile last year.
Summary
Eldorado Gold had a solid quarter in Q1 and is set to report a much stronger H2 with the benefit of higher gold production from its lowest-cost Kisladag Mine, improved cost performance at Olympias with higher by-product credits, and the benefit of a higher gold price than Q1 levels. Meanwhile, the previous outlook of significant free cash outflows has improved given the recent gold price strength, and Eldorado remains well positioned to deliver on its growth with a decent balance sheet relative to other highly leverage peers like Equinox Gold (EQX) with ~$1.0 billion million in net debt following the Greenstone purchase. That said, I don’t see enough of a margin of safety in EGO at current levels after its massive rally, and I continue to see more attractive bets elsewhere in the sector where expectations are low and there’s still the potential for 60-100% upside on re-ratings even without further help from the gold price.
Credit: Source link