
tota/iStock via Getty Images
I last covered CrowdStrike (NASDAQ:CRWD) in March; I put out a Buy rating at the time, and since then, the stock has gained around 16% in price. Now, I am reiterating my Buy rating while giving investors a careful understanding of the risk versus reward they are getting, particularly in relation to the stock valuation, if investing in the company at this time. CrowdStrike is likely positioned for exceptional long-term fundamental growth as a result of its being exposed to the high-growth advanced cybersecurity market and establishing itself as one of the leading players in the field.
In fiscal 2024, the company reported a net income of $89.3m, marking its first full year of profitability. Therefore, investors are also likely to start benefitting from increased market enthusiasm for the stock as its net margin begins to scale. This is not to mention that the company was listed on the S&P 500, as reported by CrowdStrike today, June 24.
Future Growth Catalysts
There are multiple critical catalysts that are contributing to CrowdStrike’s future growth prospects. In aggregate, these position the business as one of the leaders in the cybersecurity industry, arguably justifying the valuation at a small position in growth-oriented portfolios.
After scaling its product offerings beyond its initial focus on endpoint security, the company now provides a comprehensive suite of cybersecurity solutions. These include cloud security, identity protection, and next-generation Security Information and Event Management (‘SIEM’). Multiple major players are now recognizing CrowdStrike as an integral company in the broader technology ecosystem, including Marc Benioff of Salesforce and Matt Garman of AWS. The success in the scale and breadth of its cybersecurity operations is further evidenced by the fact that it delivered an ARR of $3.65 billion in Q1, a 33% year-over-year increase.
CrowdStrike is also adopting AWS technologies like Amazon Bedrock, Claude chatbot, and Amazon SageMaker to help it develop its AI-driven cybersecurity solutions further. In addition, CRWD management has partnered with Google Cloud to transform AI-native cybersecurity, and it has acquired Flow Security to expand its leadership in data protection across cloud-based services, third-party APIs, and GenAI applications.
These developments catalyze ongoing growth for CrowdStrike, which I believe will be significant over the next decade. Primarily, CrowdStrike is likely to benefit from the rapid scaling of AI and digitalization, and management has been very clever in positioning the company to act as one of the leaders in security solutions for the exponentially growing intelligent technology industry.
Peer Analysis
While the above operations analysis points to significant future growth prospects for CRWD shareholders, we should remember that there are multiple high-level competitors that may inhibit management’s ability to drive expansion.
For example, Microsoft (MSFT) Defender for Endpoint held a 16.4% market share in the endpoint security market in 2021/2022 based on an IDC report, compared to 17.7% for CrowdStrike. Microsoft has to be given particular concern, as it is a compelling choice for the many organizations that are already using Microsoft services.
SentinelOne’s (S) Singularity Platform also leverages advanced AI and machine learning in an effort to provide autonomous threat detection and response. This competes directly with the Falcon platform offered by CrowdStrike.
Palo Alto Networks (PANW) also offers a broad range of cybersecurity solutions and is one of the most well-known companies in the field. Its Cortex XDR platform integrates network security, cloud security, and endpoint protection.
VMware (acquired by Broadcom) (AVGO) Carbon Black is also another significant competitor. It integrates with VMware’s virtualization and cloud infrastructure products, making it an appealing option for organizations using VMware solutions already.
Author, Using Seeking Alpha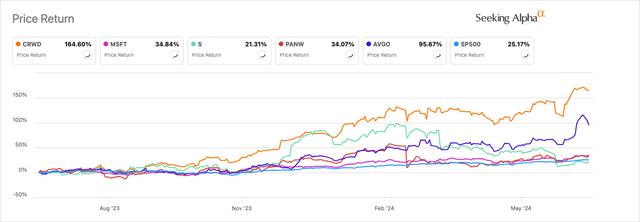
| CRWD | MSFT | S | PANW | AVGO | |
| Historical FWD Revenue Growth 5Y Avg | 51.02% | 12.99% | 53.63% | 22.06% | 10.89% |
| Historical FWD EPS Diluted Growth 5Y Avg | 75.21% | 15.66% | Negative | 21.97% | 13.83% |
| Historical FWD FCF Growth 5Y Avg | 87.10% | 12.66% | Negative | 24.42% | 15.29% |
| Equity-to-Asset Ratio | 0.37 | 0.52 | 0.7 | 0.25 | 0.4 |
| FWD Price-to-Sales Ratio | 23.15 | 13.65 | 7.05 | 12.96 | 15.03 |
Evidently, CrowdStrike is highly valued for a reason. Its FWD revenue, diluted EPS, and FCF growth are far higher than the second-place competitor in terms of growth, Palo Alto Networks. Investors would likely be wise to consider whether the valuation is actually as problematic as it seems. In my opinion, it opens up the company for potential downside volatility in the event of growth inhibitions in the future, but at the moment, Wall Street analysts’ YoY forecasts are very positive, with 30% normalized EPS growth expected in 2025, 23% in 2026, and 30.5% in 2027. Therefore, at a small allocation for risk-mitigation purposes, CRWD stock could provide very large growth-oriented returns. In my opinion, the near-term catalysts are there for the stock to continue rising in price, even if the price-to-sales ratio contracts significantly.
Stock-Based Compensation
In my last analysis of CrowdStrike, I outlined the potential long-term downside for shareholders of its incredibly high SBC. However, the SBC concern is a double-edged sword, as I believe that providing stock to management is an incredible way to incentivize and drive a results-oriented ethos within the company. I don’t think this should be underestimated for how much it may have driven the firm to achieve high levels of growth and recently turn a profit.
Currently, the SBC expense takes up approximately 19.24% of CrowdStrike’s total revenue of $3,284m. Its SBC has increased from $21m in 2019 to $632m in 2024. The 2024 amount is a 19.92% YoY increase from 2023 when it paid $527m in SBC. The negative implications of this include that the high SBC rate can increase operating losses, worsen EPS, and cause declines in the FCF margin.
AlphaQuery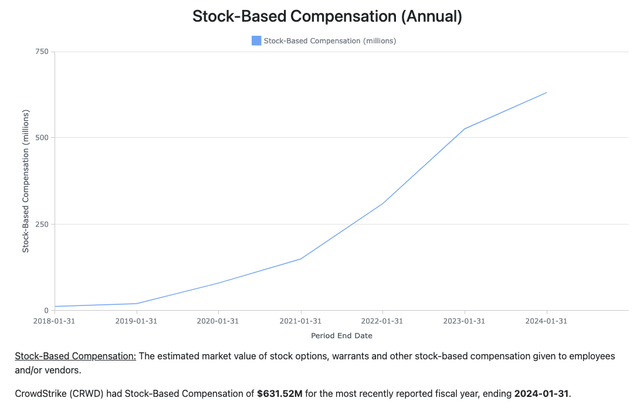
In total, the SBC YoY increase has been declining, and I am certain that this will reduce further over time as the company continues to scale. In my opinion, thus far, the net benefit of SBC has likely been positive for the company as a whole, but it now needs to be monitored more carefully by management as it can likely hire talent without such rigorous equity incentives.
2034 Price Target
In my opinion, given the company’s historical revenue, EPS, and FCF growth record that is likely to now contract in YoY % over time, and the fact that its P/S ratio has also been in a long-term downtrend, I think it is reasonable to predict that the firm hit a P/S ratio of around 20 in 2034. If its revenues grow at a 20% rate annually over the next 10 years, the stock will be worth $1694.06, as the present revenue per share is $13.68.
Author’s Graph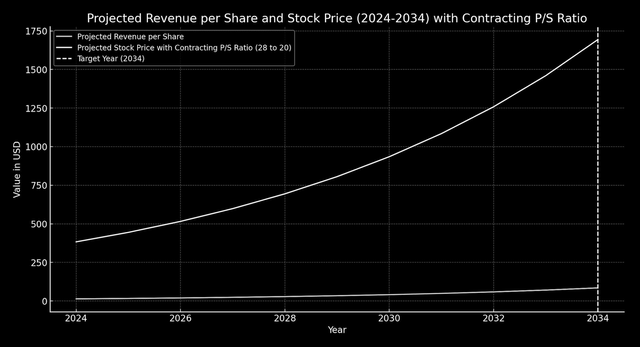
This graph is a base case, and it shows a 2034 revenue per share of $84.70 and a 2034 price target of $1694.06. The P/S ratio is charted as contracting at an equal proportion over the 10-year time period. The compound annual growth rate for the stock price over the next decade is estimated at 16% in this base case.
It is important to remember that over this 10-year period, there may be times when the company underperforms and doesn’t meet its guidance or analyst estimates. Therefore, there might be periods of severe stock price volatility (as a result of its high valuation multiples) that are not accurately reflected in the trend graph I have presented here.
There are also scenarios to consider where the P/S ratio may reduce less, leading to higher stock growth, and also instances where the firm’s revenue growth may be lower than 20% annually over the next 10 years, leading to reduced stock growth. However, the likelihood of the stock generating a 15%+ annual price return over the next decade is reasonably high, in my opinion, when we consider the trends in digitalization and CrowdStrike’s position as one of the foundational companies in advanced cybersecurity solutions. In addition, the market is likely to become so large that there will be no sole company claiming all of the major cybersecurity contracts, leaving room for multiple key players to grow exponentially along with the trends in AI and cloud services adoption.
Conclusion
CrowdStrike is undeniably highly valued. However, I don’t believe the valuation is significantly unfair when we consider the historical growth that the company has delivered in comparison to its major competitors. In my opinion, there is likely to be some contraction in the P/S ratio moving forward. However, the high growth forecasted by Wall Street and implied by the firm’s position in cybersecurity for advanced technology platforms and interfaces means that investors are likely to achieve a CAGR of at least 15%+ over the next decade, based on my models.
It is important to be aware that there are significant risks, including its high levels of SBC diluting shareholder value and the fact that Microsoft Defender likely has a significant portion of the market cornered through its ecosystem approach. However, the main risk shareholders are currently debating is the valuation, and in my opinion, given the growth the company has delivered historically, this isn’t too much of a concern. The important point here is to have CRWD in a diversified portfolio that isn’t only subject to high-growth, richly valued stocks, which would make returns highly prone to volatility over long time periods.
Credit: Source link