
High voltage electric power lines at sunset. imaginima
As a dividend growth investor, I’m always open to examining companies that I believe fit my quality standards and could continue to be great dividend growers.
It’s not an accident that many of the companies that I highlight here on Seeking Alpha are regulated utilities. It’s true that regulated utilities are vulnerable to regulators and typically don’t grow rapidly, but these businesses tend to have the following attractive characteristics:
- Since regulated utilities usually operate in a service area with no other competitors, they benefit from a captive customer base. If customers aren’t happy with their utility services, there’s not much they can do besides simply give up those services. That’s generally not something anyone is going to do.
- Regulated utilities also can periodically obtain higher rates from regulators.
- These factors often lead to consistent earnings growth for utilities, which can support sustainable dividend growth.
Another utility that has come onto my radar is Michigan’s largest electric and natural gas utility, CMS Energy (NYSE:CMS). Today, I’ll be discussing the company’s fundamentals and valuation to explain why I am beginning coverage with a buy rating.
Dividend Kings Zen Research Terminal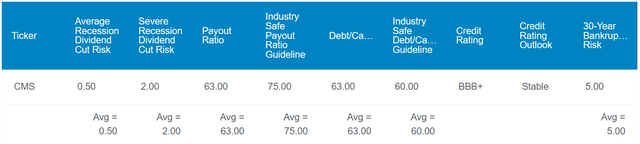
CMS’ 3.5% forward dividend yield is slightly below the utility sector’s median forward dividend yield of 3.8%. This is why Seeking Alpha’s Quant System gives it a C- grade for forward dividend yield. It also looks likely that dividend growth can continue for the foreseeable future.
CMS’ 63% EPS payout ratio is below the 75% EPS payout ratio that rating agencies prefer from utilities. The company’s 63% debt-to-capital ratio is slightly above the 60% debt-to-capital ratio that rating agencies prefer but is still manageable.
That’s how CMS possesses a BBB+ credit rating from S&P on a stable outlook. This puts the company at a 5% risk of going bankrupt in the next 30 years.
The Zen Research Terminal forecasts that there is a 0.5% probability of a dividend cut from CMS in the next average recession. In the next severe recession, this risk rises to 2%. For perspective, these are both the lowest dividend cut probabilities possible within the Zen Research Terminal.
Dividend Kings Zen Research Terminal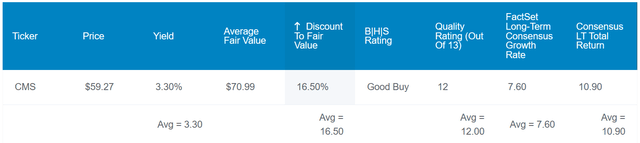
CMS’ appeal doesn’t end with its fundamentals, either. The stock appears to offer value at the current $59 share price (as of April 5, 2024).
CMS’ five-year average dividend yield of 2.9% could mean shares are worth $70 apiece. Because the company’s growth potential remains intact, I believe a reversion to this dividend yield is realistic.
CMS’ 10-year normal blended P/E ratio is 21.5 per FAST Graphs. Using the $3.34 non-GAAP diluted EPS consensus for 2024, this would give a fair value of $72 a share.
Averaging out these fair values, CMS’ shares could be worth $71 each. That implies shares are 17% undervalued from the current share price.
If CMS can match the growth consensus and revert to fair value, these are the total returns that it could generate in the coming decade:
- 3.5% yield + 7.6% FactSet Research annual growth consensus + a 1.9% annual valuation multiple expansion = 13% annual total return potential or a 239% 10-year cumulative total return versus the 9.8% annual total return potential of the S&P 500 (SP500) or a 155% 10-year cumulative total return
About As Steady As Utilities Come
CMS Q4 2023 Earnings Presentation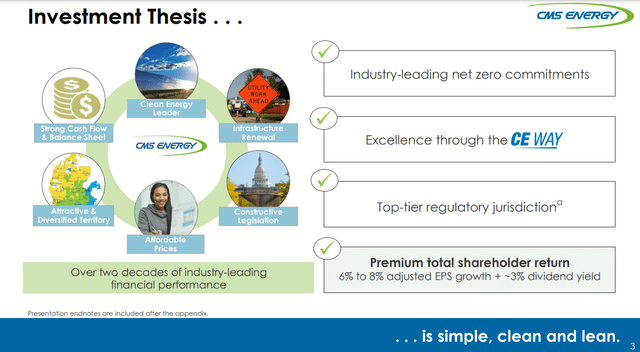
In 2023, CMS provided electric and natural gas services to 6.8 million of Michigan’s 10 million residents (concentrated in the Lower Peninsula). That makes the company not only the largest utility in Michigan but one of the largest utilities throughout the United States.
Although the company as it is known today was formed in 1987, it traces its roots back to 1886 through its Consumers Electric Utility operations. This made up $4.7 billion of the company’s operating revenue in 2023. The split for this operating revenue by customer class was 47% residential, 33% commercial, 14% industrial, and 6% other.
The company’s Consumers Gas Utility operations contributed to another $2.4 billion in operating revenue last year. CMS’ split for gas operating revenue was 60% residential, 15% commercial, 15% Gas Customer Choice (allowing gas customers to purchase gas from alternative suppliers), 5% industrial, and 5% other.
Last but not least, the NorthStar Clean Energy business is involved in the development and operation of renewable generation, as well as the marketing of independent power production. This business chipped in the remaining $297 million in operating revenue in 2023 (all details in the previous paragraphs were sourced from pages 19-32 of 270 of CMS’ 10-K filing).
FAST Graphs, FactSet
Over the past decade, CMS has delivered reliable non-GAAP diluted EPS growth to shareholders. The company’s non-GAAP diluted EPS surged 87.3% higher from $1.66 in 2013 to $3.11 in 2023 according to data from FAST Graphs – – a 6.5% compound annual growth rate.
CMS Q4 2023 Earnings Presentation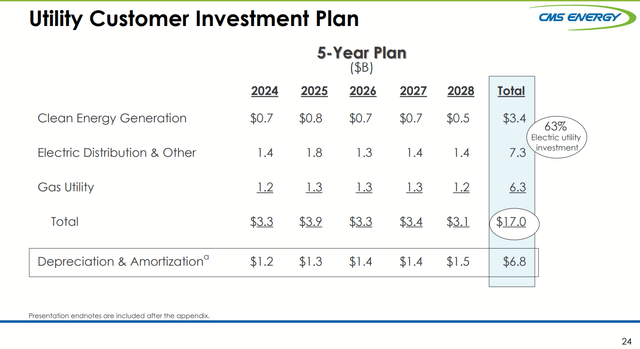
Moving forward, the company expects 6% to 8% annual non-GAAP diluted EPS to keep up. The company anticipates that it will invest $17 billion in clean energy generation, electric distribution, and gas utility infrastructure upgrades and expansion in the coming five years. These investments are expected to help the rate base compound by 7.5% annually from $24.6 billion in 2023 to $35.2 billion by 2028.
Along with a constructive regulatory environment, I believe these growth targets to be reasonable. CMS has managed to consistently grow its business through recessions, two Democratic governors, a Republican governor, and the COVID-19 pandemic.
As far as funding this growth is concerned, the company should have the means to do so. That’s because CMS thinks that it will generate $13.2 billion in operating cash flow from 2024 through 2028. The utility can leverage its BBB+ credit rating with S&P to bridge the gap between operating cash flow and its $17 billion in capital spending ambitions over that time (unless otherwise noted or hyperlinked, all info was according to CMS’ Q4 2023 Earnings Presentation).
More Dividend Growth Lies Ahead
Since 2019, CMS’ quarterly dividend per share has cumulatively compounded by 34.6% to the current rate of $0.515. That’s equivalent to a 6.1% compound annual growth rate.
Looking ahead, I would be surprised if similar dividend growth didn’t continue. The company is expected to generate $3.34 in non-GAAP diluted EPS in 2024 per the FAST Graphs consensus. Against the $2.06 in dividends per share slated to be paid during that time, this equates to a 61.7% non-GAAP diluted EPS payout ratio.
For context, that’s close to the company’s conservative targeted payout ratio of 60% (per slide 8 of 33 of CMS’ Q4 2023 Earnings Presentation). This should allow the dividend to grow about as fast as non-GAAP diluted EPS in the years to come.
Risks To Consider
CMS is a proven electric and gas utility, but there are still elements that could present risks to the investment thesis.
As a regulated utility, the company’s operations are governed by the Michigan Public Service Commission and the Federal Energy Regulatory Commission. To date, CMS has navigated the regulatory environment quite well. But if it is handed down unfavorable outcomes in future rate cases, that could hurt the company’s growth prospects. This could also result in a potential credit downgrade, which would harm CMS’ ability to raise capital on attractive terms.
CMS’ concentration in the Lower Peninsula of Michigan also comes with natural disaster risk. Major natural disasters could interrupt the company’s service to its customers, which would weigh on short-term results. If these natural disasters were severe enough, the damage done could also be beyond the scope of CMS’ commercial insurance coverage. Additionally, if the company were found liable for any wildfires, that could result in potentially substantial legal settlements.
Summary: CMS Is Worth A Look Here
FAST Graphs, FactSet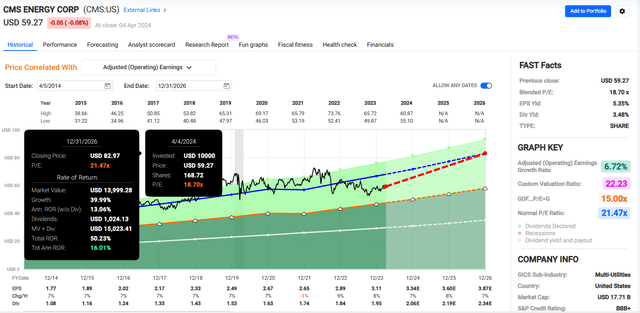
CMS is a business with an established track record of producing regular earnings growth for shareholders. The company’s capital spending plan should help to keep that going. What’s more, CMS’ spending can be backed up by its robust operating cash flows and balance sheet.
Finally, shares could currently be moderately undervalued. If CMS can grow as predicted and return to its 10-year normal P/E ratio of 21.5 as interest rates head lower, cumulative total returns of up to 50% could be possible through 2026. Thus, why I’m starting my coverage with a buy rating for the electric and gas utility.
Credit: Source link