
FatCamera
Chicago Atlantic Real Estate Finance (NASDAQ:REFI) is a lender to US cannabis operators with total loan commitments of roughly $401.3 million across 28 portfolio investments and with a weighted average yield to maturity of 19.4% as of the end of its fiscal 2024 first quarter. The outstanding principal was at $377.6 million. The cannabis mortgage REIT is flat on a total return basis year to date and is currently trading at an 8.4x multiple to annualized first-quarter EPS. Earnings were $0.47 per share in the first quarter, dipping by 13 cents versus its year-ago comp. The mREIT is also trading at a small 4.9% premium to its book value of $14.97 per share at the end of the first quarter.
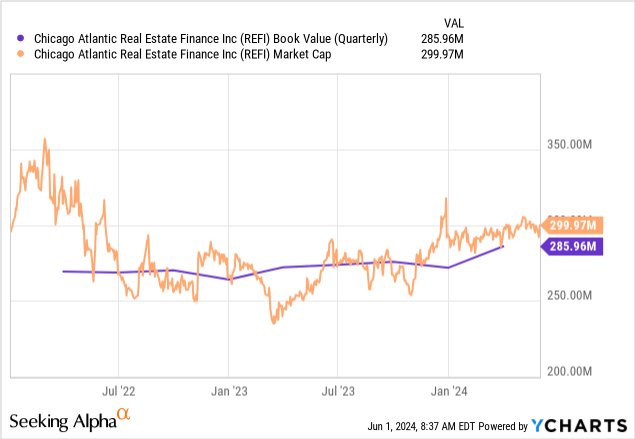
The premium to book value has allowed REFI to tap its equity for capital, with the mREIT issuing roughly 896,000 shares through its ATM program at an average price of $15.93 for $13.9 million in net proceeds. REFI last declared a quarterly cash dividend of $0.47 per share, kept unchanged from its prior quarter and $1.88 per share annualized for a 12% dividend yield. The mREIT has kept its base quarterly dividend distributions stable, but augmented with end-of-year special payouts. However, the current dividend forms a 100% payout ratio against EPS following the year-over-year dip, dampening the prospect of a year-end payment in 2024 and opening the specter of a possible near-term cut.
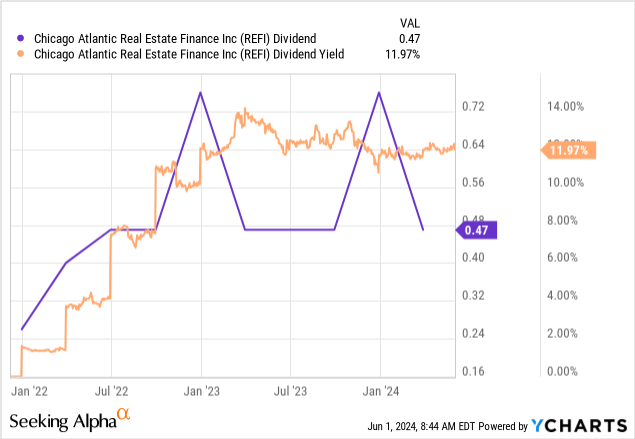
Dividend, Balance Sheet, And Liquidity
Chicago Atlantic Real Estate Finance Fiscal 2024 First Quarter Supplemental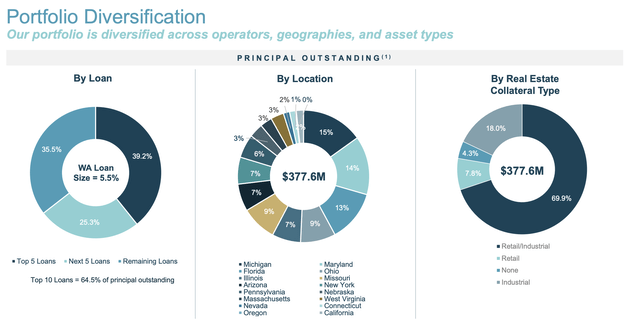
The uncertainty for REFI shareholders is whether the current dividend faces a near-term reduction, with the payout running at 100%. First quarter net interest income at $13.24 million dipped from $14.91 million a year ago with the per share figure at $0.47 representing a 7.8% dip sequentially versus the fourth quarter. The fall in net interest income came with commitments up nearly 22% versus $328.1 million in its year-ago comp, but with interest income falling and interest expenses up 30% year-over-year. REFI’s outstanding principal is concentrated on retail-industrial cannabis properties which form 70% of collateral, with purely industrial properties at 18% as the second-largest collateral allocation.
Chicago Atlantic Real Estate Finance Fiscal 2024 First Quarter Form 10-Q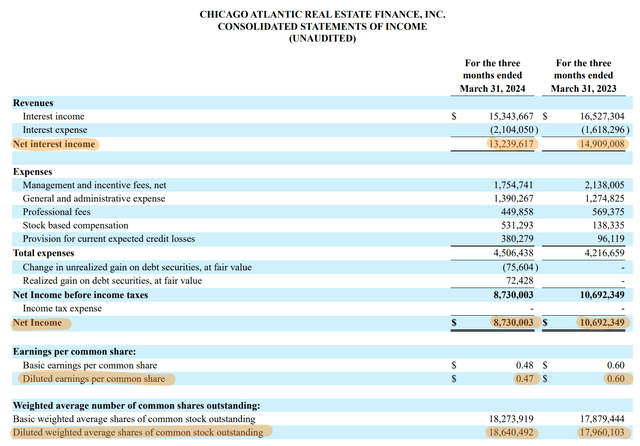
REFI’s first quarter total reserve for current expected credit losses increased to $5.4 million, up nearly $400,000 sequentially. The mREIT’s main loan collateral coverage metric did see some deterioration, with its real estate collateral coverage at 1.3x dipping from 1.5x sequentially in the fourth quarter. However, the REIT’s loan to enterprise value, at 40.5%, had improved from 44.1% in the fourth quarter. This metric is derived from dividing the outstanding principal balance by the total value of collateral on a weighted average basis.
Chicago Atlantic Real Estate Finance Fiscal 2024 First Quarter Supplemental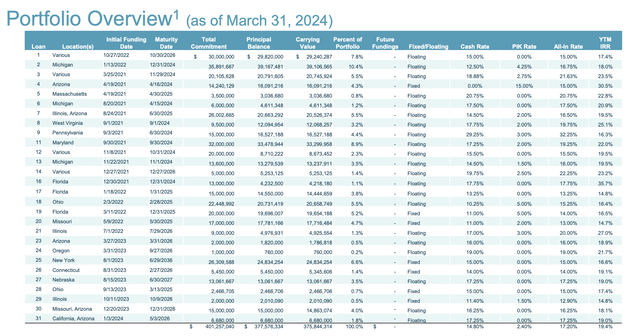
While REFI has a $24.8 million loan maturing in 2036, the majority of the mREIT’s loans are set to mature over the next three years. Gross originations during the first quarter came in at $22.5 million, with $15.8 million of this funding to existing borrowers. The current expected credit loss reserve at $5.4 million was 1.4% of REFI’s outstanding principal balance. The REIT’s non-GAAP distributable earnings of $9.7 million, around $0.52 per share, is also covering the dividend by 110%.
Chicago Atlantic Real Estate Finance Fiscal 2024 First Quarter Form 10-Q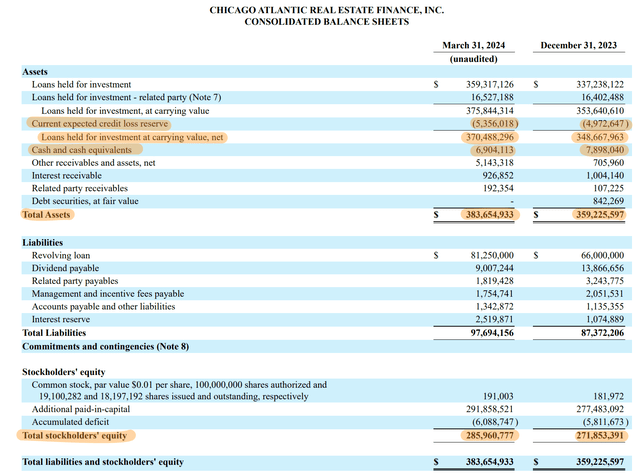
Reclassification And The Fed
Cannabis reclassification will present the most salient evolution of the US cannabis landscape in the absence of federal legalization. Reclassification will see cannabis moved from a Schedule I to the Schedule III category. Critically, the move to a lower-risk tier will expand the range of banking services for cannabis firms as well as allow operators to take standard tax deductions which are currently prohibited for businesses that generate revenue from Schedule I drugs. This is as the cannabis industry is being forecasted to grow to reach $71 billion in sales by 2030. The tax benefits from reclassification would embed more liquidity within the industry, possibly improving the overall solvency of cannabis operators, and should generally be interpreted as a positive for REFI.
CME FedWatch Tool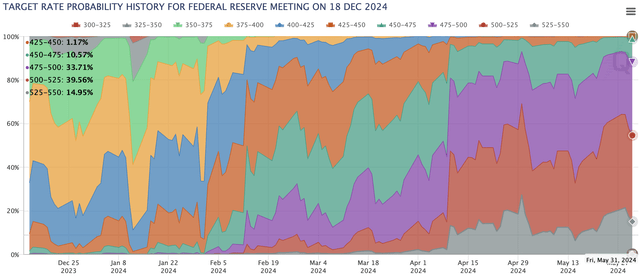
This comes as the Fed delays interest rate cuts into the second half of the year, with market expectations now just settling for a single rate cut of 25 basis points to exit 2024, down from as much as three rate cuts earlier this year. REFI has 76.6% of its outstanding principal balance priced at a variable interest rate, down from 80.5% in the prior quarter, but at a level where cuts to base interest rates would dramatically impact its weighted average yield to maturity. The REIT remains a hold against its premium to NAV and double-digit dividend yield.
Credit: Source link