
bkindler
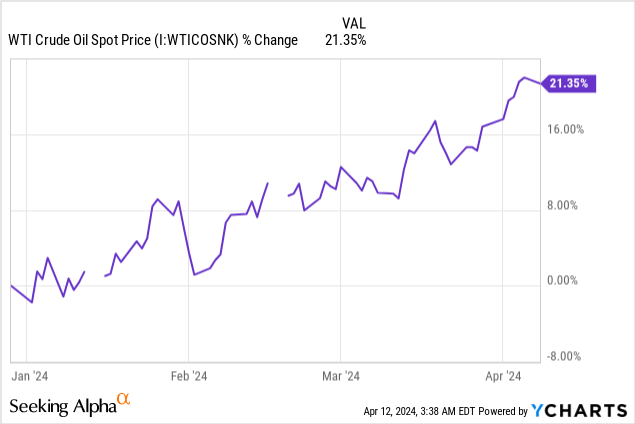
Chevron (NYSE:CVX) is scheduled to release earnings on April 26, 2024 and given that petroleum prices have repriced to $85 per barrel, I believe the petroleum company is set for a very strong earnings report later this month. Additionally, OPEC+ countries, led by Russian, recently decided to extend supply cuts into the second-quarter, which should provide additional pricing support for petroleum-focused energy firms. As a result, I expect Chevron to sail past earnings estimates and EPS revisions also show some robust upside momentum. I believe Chevron has a lot of surprise potential for its upcoming Q1 report and the risk profile is, despite a strong revaluation in FY 2024, still favorable!
Previous rating
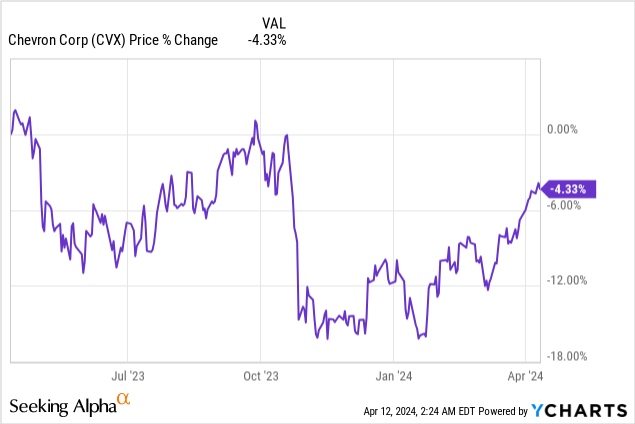
After OPEC+ Countries, mainly Saudi Arabia and Russia, extended supply restrictions in October, I recommended aggressively for investors to buy the drop for Chevron’s shares: Time To Be Greedy. Last month, OPEC+ countries doubled down on their supply cuts, which we already see provides additional pricing support and is set to provide a lift for Chevron’s average realized petroleum prices. With higher free cash flow around the corner, the company may also decide to return more cash to shareholders this year.
A strong Q1 earnings report is coming up
A robust U.S. economy and concerted OPEC efforts to keep petroleum prices high, are providing substantive support for petroleum prices. With WTI reaching $85 per barrel (and currently seeming to close in on $86 per barrel), large, production-focused energy companies like Chevron are set for strong earnings releases in the near future. Analysts will likely continue to incorporate higher petroleum prices into their Q1 EPS forecasts as the earnings date approaches. Currently, analysts expect $2.93 per-share in adjusted earnings for Chevron, which compares against an actual $3.45 per-share in EPS in Q4’23.
Seeking Alpha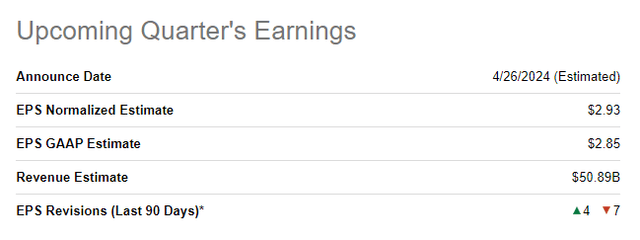
Expect to see a significant boost to free cash flow
The uptick in energy prices is obviously a favorable development for Chevron and other production-minded petroleum firms. Pricing support comes chiefly from OPEC+’s decision in March to extend additional voluntary supply restrictions by 2.2M barrels per day until the end of the second-quarter. This resulted in a nice boost to WTI petroleum prices, which producers like Chevron are now benefiting from.
In FY 2023, Chevron generated $19.8B in free cash flow and returned a ton of cash to shareholders. The company’s board of directors authorized a massive $75.0B stock buyback last year as well, which resulted in Chevron accelerating share repurchases throughout the year. In the fourth-quarter, Chevron repurchased $3.4B of its own shares in the open market, with total stock buybacks for the full-year totaling $14.9B. With OPEC+’s supply restrictions providing incremental pricing support in Q1’24, I believe Chevron is going to report a significant Q/Q improvement in both its earnings and its free cash flow later this month. Besides pricing support from OPEC+, Chevron guided for 10% production growth from its Permian assets (+75 MBOED) in FY 2024, so net production growth itself may be a catalyst for higher net earnings and free cash flow on a full-year basis for Chevron.
Chevron 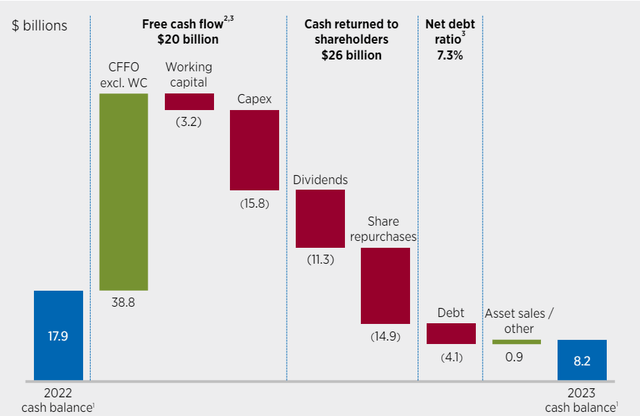
As a result, investors may see an acceleration of capital returns in FY 2024, including both a higher dividend as well as aggressive stock buybacks. In the last three years, Chevron reduced the amount of its outstanding shares by 4.5%.

Chevron’s valuation
Chevron and Exxon Mobil (XOM) are by far the two largest, diversified petroleum companies in the US. Both companies are obviously hugely profitable right now and return a significant amount of cash to shareholders through buybacks and dividends.
Chevron is currently trading at a price-to-earnings ratio of 11.2X, which is 1) Below the industry average ratio of 12.3X and 2) Only slightly (+12%) above the 3-year average P/E ratio. I believe Chevron could reasonably trade at 13-14X forward earnings under the assumption that petroleum prices remain above the $80 per barrel price level for longer and that the firm raises its dividend this year again. With a 12-13X forward earnings multiple, Chevron’s valuation would also be much more in-line with ExxonMobil’s. A 12-13X P/E ratio, which in my opinion is justifiable during the current bull market run as the company sees significant earnings growth, implies a fair value of up to $188.

Risks with Chevron
The biggest risk for Chevron, as I see it, relates to a significant contraction of the US economy and weakening demand for petroleum products, which would negatively affect Chevron’s average prices. From a commercial point of view, lower petroleum prices will immediately affect the company’s production margins as well as its free cash flow potential. In this scenario, Chevron would likely also want to slow its stock buybacks and return less cash overall to its shareholders.
Final thoughts
Chevron is a promising long-term investment for investors because the company is one of the largest, diversified fossil companies in the US petroleum industry. Chevron generates a ton of free cash flow from its core exploration business (~$20B in FY 2023) and the company is set to see a significant Q/Q boost to its earnings and free cash flow when it reports Q1 results later this month. Positive EPS revision momentum ahead of the Q1 earnings report could also indicate that Chevron is set to sail past current consensus estimates. With a P/E valuation ratio of only 11.2X, I believe Chevron is an attractive capital return play for FY 2024 and has a very attractive risk profile for investors!
Credit: Source link